
Market Overview:
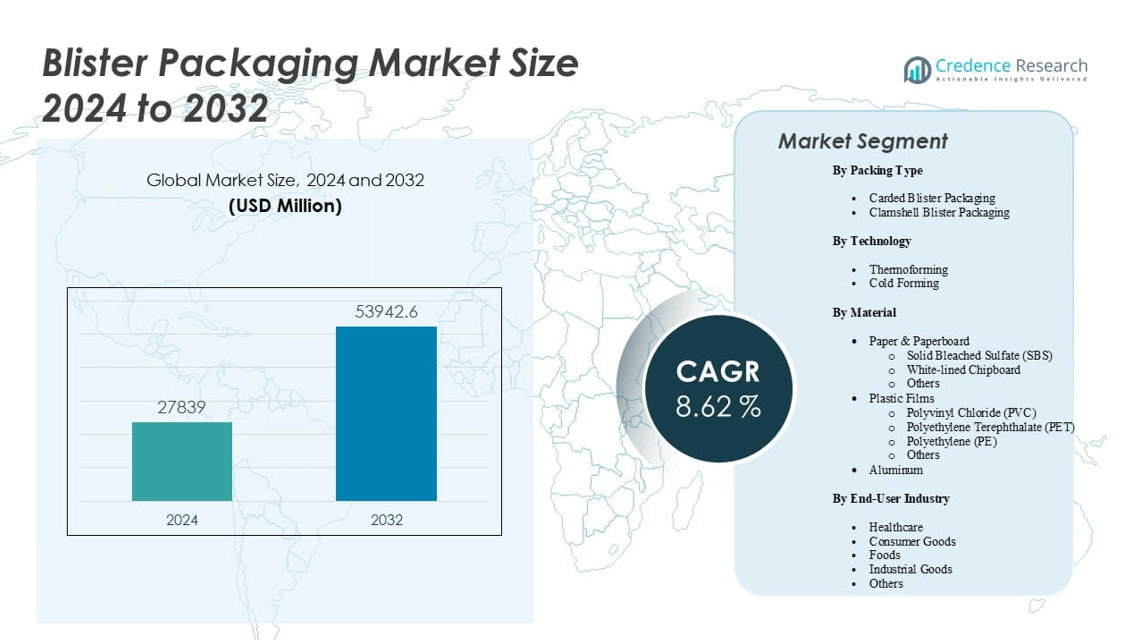
The Blister Packaging Market Size is projected to grow from USD 27,839 million in 2024 to an estimated USD 53,942.6 million by 2032, with a compound annual growth rate (CAGR) of 8.62% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Blister Packaging Market Size 2024 | USD 27,839 million |
| Blister Packaging Market, CAGR | 8.62% |
| Blister Packaging Market Size 2032 | USD 53,942.6 million |
The blister packaging market is driven by the rising demand for safe, convenient, and tamper-evident packaging across pharmaceuticals, consumer goods, and food sectors. Manufacturers are increasingly adopting blister packs due to their cost efficiency, product protection, and enhanced shelf appeal. The growing pharmaceutical industry, driven by aging populations and increased healthcare access, has particularly boosted demand. Technological advancements in thermoforming and cold-forming techniques, along with heightened regulatory emphasis on unit-dose packaging and anti-counterfeit features, continue to support sustained market growth globally.
Regionally, North America leads the blister packaging market due to its advanced pharmaceutical infrastructure, strong regulatory standards, and widespread use of unit-dose formats. Europe follows closely, benefiting from stringent packaging regulations and high adoption in healthcare and consumer goods. Meanwhile, Asia Pacific is emerging rapidly as a key growth region, supported by its expanding middle-class population, increasing healthcare expenditures, and the booming manufacturing sector in countries like China and India. Latin America and the Middle East & Africa are gradually gaining momentum, driven by improving industrial capabilities and growing demand for secure, modern packaging solutions.
Market Insights:
- The Blister Packaging Market Size is projected to grow from USD 27,839 million in 2024 to USD 53,942.6 million by 2032, registering a CAGR of 8.62%.
- Growing demand for tamper-evident and unit-dose packaging in pharmaceuticals is driving consistent market expansion.
- Rising focus on consumer convenience and enhanced product visibility boosts adoption in food and consumer goods sectors.
- High raw material costs and complex recycling of multi-layered materials pose challenges to widespread sustainable adoption.
- North America leads the market with 32.5% share, driven by regulatory compliance and pharmaceutical dominance.
- Asia Pacific emerges as the fastest-growing region due to healthcare access expansion and manufacturing scale.
- Europe holds a 28.4% share, supported by strong sustainability mandates and advanced packaging infrastructure.
Market Drivers:
Rising Demand from the Pharmaceutical Industry Reinforces Market Growth
The increasing use of blister packaging in the pharmaceutical sector plays a pivotal role in propelling the Blister Packaging Market Size. Blister packs provide unit-dose packaging, safeguard product integrity, and offer clear visibility, which is essential for regulatory compliance. Pharmaceutical companies prefer blister formats due to their ability to prevent contamination and extend shelf life. The growing elderly population and the rising incidence of chronic diseases have increased medication consumption globally. It has created consistent demand for efficient and tamper-evident packaging. Governments and healthcare agencies support the use of blister packaging to promote patient safety. Compliance packaging is gaining traction due to its ability to support accurate dosing. These factors combined continue to push adoption across developed and emerging pharmaceutical markets.
Cost-Effectiveness and Material Efficiency Drive Packaging Preferences
The cost advantages of blister packaging significantly contribute to market expansion across sectors. Compared to traditional packaging forms, blister packs use less material while maintaining protection and presentation. Manufacturers benefit from reduced packaging weight and lower transportation costs. It enables companies to optimize supply chains and achieve sustainability goals. The format supports high-speed automation, which improves production efficiency. Blister packs also allow for easy customization to meet branding and product-specific requirements. The ability to print on backing materials enhances marketing communication. Companies across consumer goods and healthcare leverage these benefits to gain competitive advantage.
- For example, SÜDPACK’s PharmaGuard® uses polypropylene (PP) mono-material films that are fully recyclable. The company’s partnership with IMA ensures that these films run at standard line speeds without major retrofitting, maintaining output rates of over 400 packs/minute while reducing material consumption by as much as 30% compared with traditional PVC/Alu blisters.
Strong Demand for Tamper-Evident and Anti-Counterfeit Solutions
Heightened concerns around product security and authenticity drive increased use of blister packaging. The tamper-evident nature of the format helps protect sensitive items such as medicines, batteries, and electronic components. Counterfeit drugs remain a global concern, especially in low- and middle-income regions. It encourages regulatory bodies to enforce stricter packaging standards. Blister packs support integration of features like holograms, barcodes, and RFID tags. These elements enhance traceability and verification across the supply chain. The format also ensures better compliance with serialization requirements. Major industries prioritize safety and authentication, which fosters consistent demand for secure packaging formats.
- Amcor’s AmSky™ HDPE mono-material blister for example, eliminates PVC and aluminum, enhancing recyclability while maintaining high moisture barrier performance. It operates on standard thermoforming blister machines with minimal adjustments and meets U.S. FDA’s 21 CFR 211.132 requirement for tamper-evident packaging through its push-through design.
Growing Consumer Preference for Convenience and Transparency
Consumer preference for easy-to-use, portable, and visually accessible packaging continues to shape the market. Blister packaging enables users to view product quantity and quality without opening the package. It facilitates informed purchasing decisions and builds consumer trust. For healthcare users, the ease of pushing tablets from blisters supports dosage adherence. Food, electronics, and personal care sectors also adopt blister packs to enhance product presentation and convenience. It helps retailers improve product merchandising and shelf management. Compact designs reduce storage space and packaging waste. This alignment with evolving consumer behavior positively influences the Blister Packaging Market Size.
Market Trends
Adoption of Eco-Friendly and Recyclable Blister Packaging Solutions
Sustainability has emerged as a leading trend across the packaging sector. Companies are shifting to recyclable and biodegradable materials in blister packaging. It includes paper-based substrates and recyclable plastics that reduce environmental impact. Regulatory pressure and consumer expectations have accelerated this transition. Brands position eco-friendly packaging as a differentiator in competitive markets. Innovation in compostable and mono-material blisters continues to gain traction. Packaging manufacturers focus on reducing plastic content without compromising performance. The trend supports circular economy goals and enhances brand image. It contributes to long-term transformation in the Blister Packaging Market Size.
- For example, Bayer, in collaboration with Liveo Research, developed a PET-based mono-material blister pack that eliminates PVC and enhances sustainability. The new design reduces package weight by 18%, water usage by 78%, and cuts carbon footprint by 38% per unit compared to traditional PVC blisters.
Technological Advancements in Manufacturing and Printing Techniques
Advancements in thermoforming and cold-forming technologies are elevating production efficiency and precision. Automated equipment enables high-speed blister formation with minimal errors. It ensures dimensional accuracy and consistent seal integrity. Digital and flexographic printing methods allow brands to personalize packaging and comply with serialization norms. High-resolution printing improves visual appeal and anti-counterfeit capabilities. Machine learning and robotics are being integrated into packaging lines to boost throughput. The use of laser marking and UV inks enhances traceability. It supports a data-driven supply chain and strengthens the packaging ecosystem across multiple industries.
Integration of Smart and Connected Packaging Features
Smart packaging has gained traction with growing demand for real-time data access and product tracking. Blister packs now feature QR codes, NFC tags, and embedded sensors. These elements enable end-users to verify product authenticity and access usage instructions. Healthcare providers use smart blister packs to monitor medication adherence and patient behavior. It also supports remote patient engagement in clinical trials. Smart features reduce risks associated with dosing errors and counterfeit drugs. This trend aligns with digital health strategies and tech-enabled retail packaging. It elevates the functional value of blister packs beyond containment.
Shift Toward Customized, Aesthetic, and Market-Specific Packaging Designs
Customization has become central to packaging strategies across sectors. Brands design blister packs to match regional preferences, regulatory needs, and brand positioning. Personalization supports direct-to-consumer strategies in pharmaceuticals and supplements. Aesthetic designs improve shelf impact in retail spaces. Companies launch seasonal or limited-edition packs to create exclusivity. Blister packaging manufacturers collaborate with clients to create size-efficient, visually distinctive formats. It supports differentiation in crowded product categories. The Blister Packaging Market Size benefits from the rising emphasis on flexible design and product-specific packaging architecture.
- Arcade Beauty, for instance, utilizes highly customized cosmetic blister packs allowing brand-specific shapes and seasonal graphics that connect with consumers at a personal level
Market Challenges Analysis
Fluctuating Raw Material Costs and Regulatory Complexities Limit Market Stability
The volatility in raw material prices, particularly plastics and aluminum, creates cost uncertainty across the blister packaging industry. Packaging manufacturers face challenges in cost planning and procurement strategies. It impacts profitability and delays production schedules for some small and medium enterprises. Regulatory compliance adds further complexity, especially across markets with differing packaging standards. Pharmaceutical blister packaging must meet stringent requirements for barrier properties, labeling, and traceability. Constant updates to global packaging mandates require companies to invest in testing and reformulation. These factors impose high operational costs and hinder smooth market expansion for some participants in the Blister Packaging Market Size.
Sustainability Pressure and Limited Recycling Infrastructure Pose Obstacles
The rising demand for sustainable blister packaging is met with infrastructure gaps in recycling systems. Multi-material blister packs often lack compatibility with standard recycling streams. Separation of plastic films and aluminum foils requires specialized facilities, which are not available in many regions. It limits the scalability of eco-friendly blister packaging adoption. Consumers and regulators increasingly expect circular packaging models, but current technologies and systems fall short. Packaging firms must balance sustainability goals with performance and cost. Developing fully recyclable and biodegradable solutions at scale remains a technical challenge. These issues slow down the transition toward greener blister formats.
Market Opportunities
Expansion in Emerging Markets with Rising Healthcare and Consumer Spending
Emerging economies present strong opportunities for blister packaging expansion. Countries in Asia Pacific, Latin America, and Africa show rising demand for packaged pharmaceuticals, electronics, and personal care items. The growing middle class and urbanization create favorable consumption patterns. It enables global and local companies to introduce blister packaging in high-volume, affordable formats. Healthcare investments and access to over-the-counter drugs further amplify the need for safe and cost-efficient packaging solutions. The Blister Packaging Market Size stands to gain significantly from this regional growth momentum.
Innovation in Mono-Material and Biodegradable Blister Solutions
There is growing opportunity for manufacturers investing in recyclable and compostable blister formats. Research and development efforts are focused on creating mono-material blisters that meet performance and sustainability benchmarks. Companies are exploring materials such as PET, PLA, and cellulose-based films. These innovations aim to meet regulatory demands while aligning with corporate ESG commitments. It allows packaging producers to attract environmentally conscious consumers and expand market share across industries.
Market Segmentation Analysis:
The Blister Packaging Market Size is structured across diverse segments, each contributing uniquely to market growth.
By packing type, carded blister packaging dominates due to its wide use in pharmaceuticals and retail consumer goods, while clamshell blister packaging finds application in electronics and hardware products for its enhanced protection and visibility.
- For example, Amcor’s AmSky™ blister system eliminates PVC and uses a high-density polyethylene (HDPE) mono-material design that maintains barrier performance while improving recyclability.
By technology, thermoforming remains the most widely adopted method for its cost efficiency and adaptability, whereas cold forming is preferred for applications requiring superior barrier properties, especially in healthcare.
By material, plastic films account for the largest share, led by polyvinyl chloride (PVC) and polyethylene terephthalate (PET), which offer clarity and strength. Polyethylene (PE) and other films provide flexibility and durability across formats. Paper & paperboard including solid bleached sulfate (SBS) and white-lined chipboard are gaining traction for their eco-friendly profiles. Aluminum remains essential in cold-formed packs due to its excellent barrier properties.
- For example, TekniPlex developed high-barrier blister films that maintain less than 0.05 g/m²/day moisture vapor transmission rate (MVTR), enabling extended shelf life for moisture-sensitive drugs.
By end-user, the healthcare sector leads with strong demand for safe, compliant packaging. Consumer goods, foods, and industrial applications follow, supporting broad adoption across industries. The Blister Packaging Market Size continues to evolve with growing demand for secure, sustainable, and visually appealing packaging solutions.
Segmentation:
By Packing Type
- Carded Blister Packaging
- Clamshell Blister Packaging
By Technology
- Thermoforming
- Cold Forming
By Material
- Paper & Paperboard
- Solid Bleached Sulfate (SBS)
- White-lined Chipboard
- Others
- Plastic Films
- Polyvinyl Chloride (PVC)
- Polyethylene Terephthalate (PET)
- Polyethylene (PE)
- Others
- Aluminum
By End-User Industry
- Healthcare
- Consumer Goods
- Foods
- Industrial Goods
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America accounts for 32.5% of the global Blister Packaging Market Size, driven by advanced pharmaceutical manufacturing, strong regulatory frameworks, and high demand for unit-dose packaging formats. The United States leads the regional market due to its mature healthcare infrastructure, focus on patient safety, and widespread use of OTC medications. Demand from the consumer electronics and nutraceutical sectors supports market stability. Blister packs are favored for their tamper-evident properties and compatibility with automated packaging systems. Regulatory compliance with FDA and serialization norms sustains long-term adoption. Companies in this region invest in recyclable and smart packaging technologies to meet environmental and traceability goals.
Europe holds a 28.4% share of the global market, supported by stringent EU regulations, strong pharmaceutical production, and rising sustainability mandates. Germany, France, and the UK are key contributors, leveraging automation and eco-friendly packaging formats. Demand for cold-form and high-barrier blister packaging remains high across prescription and OTC drugs. The region’s advanced R&D environment enables innovation in material science and barrier coatings. Manufacturers focus on recyclable and mono-material solutions in response to the EU’s circular economy targets. The Blister Packaging Market Size in Europe continues to grow steadily with strong public-private collaboration in packaging technology development.
Asia Pacific captures 26.1% of the market, representing the fastest-growing regional segment due to expanding healthcare access, rising population, and growing consumer markets. China and India drive significant volume growth across pharmaceuticals and consumer goods. Local manufacturers adopt cost-effective blister formats to meet rising demand in urban and rural areas. The region benefits from increasing government support for domestic pharmaceutical production and investments in packaging infrastructure. It offers scalable production capabilities and competitive cost advantages. Southeast Asia and South Korea are emerging hubs, contributing to the region’s strengthening global footprint in blister packaging.
Key Player Analysis:
- Amcor plc
- WestRock Company
- Sonoco Products Company
- Constantia Flexibles
- Klöckner Pentaplast Group
- Honeywell International Inc.
- Tekni-Plex
- UFlex Limited
- WINPAK LTD.
- SteriPack Group
- ACG
- DuPont (E.I. du Pont de Nemours and Company)
- Display Pack
Competitive Analysis:
The Blister Packaging Market Size features a competitive landscape with the presence of global and regional players focusing on innovation, material sustainability, and automation. Leading companies such as Amcor plc, Sonoco Products Company, Constantia Flexibles, and WestRock Company hold significant market shares through extensive product portfolios and strategic partnerships. It encourages investments in recyclable materials, high-barrier films, and smart packaging technologies to meet evolving industry demands. Companies emphasize enhancing speed-to-market and customization capabilities. Mergers, acquisitions, and capacity expansions remain central to their growth strategies. Competitive intensity is high, particularly in pharmaceutical and consumer goods segments where regulatory compliance and quality assurance are critical.
Recent Developments:
- In May 2025, Constantia Flexiblesintroduced EcoVerHighPlus, a recyclable-ready mono PP laminate for coffee packaging. Developed in close collaboration with Delica AG, this innovative packaging delivers robust barrier properties and recyclability, meeting growing industry demands for sustainability. The launch showcases Constantia's commitment to high-performance, eco-friendly packaging solutions.
- In March 2025, Amcor plcunveiled an industry-first 2oz retort bottle for nutritional shots, featuring proprietary StormPanel™ technology, designed in partnership with Insymmetry. This innovation targets the growing market for durable, shelf-stable packaging for low-acid beverages and is the first of its kind to offer extended 12-month shelf stability for products like energy and wellness shots.
- In June 2024, Sonoco Products Companyannounced the acquisition of Eviosys for approximately $3.9billion. This deal is set to create the world's largest metal food can and aerosol packaging platform, accelerating Sonoco's strategy and expanding its global reach.
Market Concentration & Characteristics:
The Blister Packaging Market Size is moderately concentrated, with key players accounting for a large share through integrated manufacturing capabilities and global distribution networks. It exhibits characteristics of innovation-driven competition, regulated quality standards, and demand for customization. Entry barriers remain high due to capital requirements, compliance obligations, and the need for advanced forming and sealing technologies. Companies with in-house design, material development, and automation capabilities maintain a competitive edge. The market favors firms that can offer scalable solutions and meet sustainability targets across multiple regions. Continuous investment in R&D and localization strategies further defines competitive success in this sector.
Report Coverage:
The research report offers an in-depth analysis based on Packing Type, Technology, Material and End-User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will see increased adoption of sustainable materials to align with global environmental regulations.
- Pharmaceutical demand for unit-dose and tamper-evident packaging will continue driving volume growth.
- Technological advancements in cold-forming and thermoforming will enhance production efficiency and customization.
- Growing use of smart packaging features will support product authentication and patient compliance.
- Expansion in emerging markets will create new opportunities across healthcare, personal care, and food sectors.
- Manufacturers will invest more in recyclable mono-material designs to meet circular economy goals.
- Automation and digitization of packaging lines will improve scalability and operational efficiency.
- E-commerce growth will boost demand for protective and consumer-friendly blister formats.
- Regulatory pressures will intensify, prompting higher investment in compliance-ready packaging solutions.
- Strategic mergers and capacity expansions will shape competitive dynamics and global market positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Pharmaceutical Industry Expansion
The growing pharmaceutical sector, driven by aging populations and increased healthcare access, is fueling demand for blister packaging due to its unit-dose, tamper-evident, and contamination-resistant properties. Regulatory mandates for patient safety and accurate dosing further reinforce adoption in both developed and emerging markets.
Cost-Effectiveness and Material Efficiency
Blister packaging uses less material than traditional packaging, reducing costs for manufacturers and enabling efficient supply chain management. Its lightweight nature lowers transportation expenses, while high-speed automation and easy customization support scalability and branding.
Demand for Tamper-Evident and Anti-Counterfeit Solutions
Heightened concerns over product security, especially in pharmaceuticals and electronics, are driving the adoption of blister packs with tamper-evident features and anti-counterfeit technologies such as holograms and RFID tags. These solutions help ensure product authenticity and regulatory compliance.
Sustainability and Eco-Friendly Packaging Trends
Increasing regulatory and consumer pressure for sustainable packaging is prompting manufacturers to develop recyclable, biodegradable, and mono-material blister solutions. Innovations in materials like PET and PP mono-films are helping companies meet circular economy goals and differentiate in the market.
Consumer Preference for Convenience and Transparency
Blister packaging offers easy-to-use, portable, and visually accessible formats that appeal to consumers in healthcare, food, and consumer goods. The ability to view product quality and quantity without opening the package enhances trust and supports informed purchasing decisions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Blister Packaging Market Size?
What are the key segments within the Blister Packaging Market Size?
What are some challenges faced by the Blister Packaging Market Size?
Who are the major players in the Blister Packaging Market Size?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Plastic Films (PVC, PET, PE, Others)
- 1.2.2 Paper & Paperboard (SBS, White-lined Chipboard, Others)
- 1.2.3 Aluminum
- 1.3 By Technology
- 1.3.1 Thermoforming
- 1.3.2 Cold Forming
- 1.4 By Packing Type
- 1.4.1 Carded Blister Packaging
- 1.4.2 Clamshell Blister Packaging
- 1.5 By End-User Industry
- 1.5.1 Healthcare
- 1.5.2 Consumer Goods
- 1.5.3 Foods
- 1.5.4 Industrial Goods
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,839 million → 2032: USD 53,942.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Blister Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Blister Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Blister Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Blister Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Blister Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Blister Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Blister Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Blister Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,839 million → 2032: USD 53,942.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Blister Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic Films (PVC, PET, PE, Others)
- 12.3.7.2 Paper & Paperboard (SBS, White-lined Chipboard, Others)
- 12.3.7.3 Aluminum
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Thermoforming
- 12.4.7.2 Cold Forming
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packing Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Carded Blister Packaging
- 12.5.7.2 Clamshell Blister Packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Healthcare
- 12.6.7.2 Consumer Goods
- 12.6.7.3 Foods
- 12.6.7.4 Industrial Goods
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Blister Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Blister Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Blister Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Blister Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 WestRock Company
- 18.4 Sonoco Products Company
- 18.5 Constantia Flexibles
- 18.6 Klöckner Pentaplast Group
- 18.7 Honeywell International Inc.
- 18.8 Tekni-Plex
- 18.9 UFlex Limited
- 18.10 WINPAK LTD.
- 18.11 ACG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

