
Bone Metastasis Market Overview:
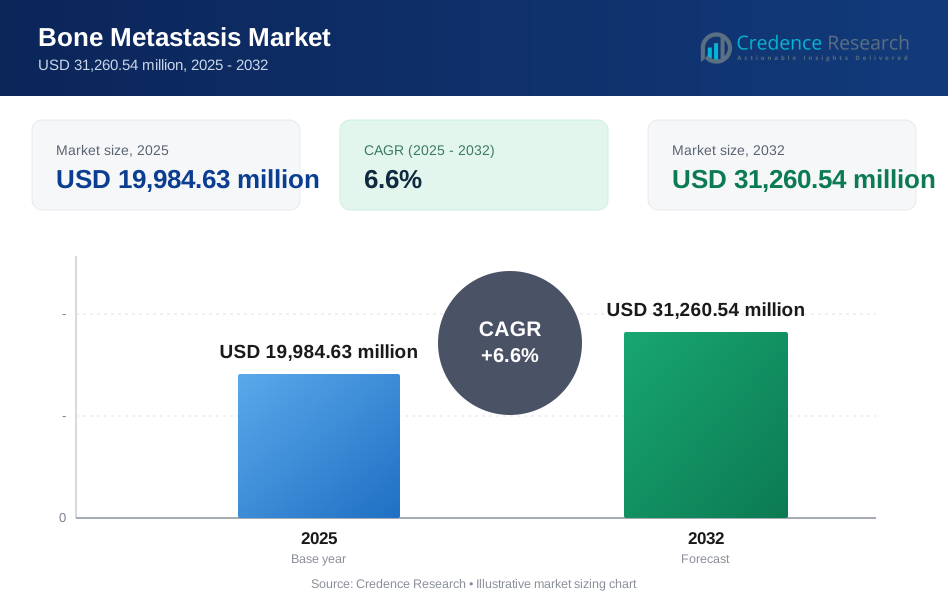
The global Bone Metastasis Market size was estimated at USD 19,984.63 million in 2025 and is expected to reach USD 31,260.54 million by 2032, growing at a CAGR of 6.6% from 2025 to 2032. Growth is primarily driven by the rising treated prevalence of advanced solid tumors and longer survival in metastatic settings, which increases the duration and intensity of bone-directed management across therapy lines. North America remains the largest regional market due to broad access to advanced imaging, systemic oncology therapies, and multidisciplinary care pathways that support earlier detection and sustained treatment.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Bone Metastasis Market Size 2025 | USD 19,984.63 million |
| Bone Metastasis Market, CAGR | 6.6% |
| Bone Metastasis Market Size 2032 | USD 31,260.54 million |
Key Market Trends & Insights
- The Bone Metastasis Market expands from USD 19,984.63 million (2025) to USD 31,260.54 million (2032) at a 6.6% CAGR (2025–2032).
- Imaging leads the diagnosis mix with an estimated 72.9% share in 2025, reflecting imaging-led detection, staging, and monitoring pathways.
- Osteolytic bone metastasis represents an estimated 48.7% share in 2025, supported by high clinical volume across multiple common primary tumors.
- Systemic medical therapy accounts for an estimated 41.6% share in 2025, indicating broad utilization across primaries and multiple lines of treatment.
- North America holds an estimated 36.2% share in 2025, followed by Europe at 29.4% and Asia Pacific at 21.1%, highlighting concentration of treated prevalence in higher-access regions.

Segment Analysis
Bone metastasis care pathways remain anchored in early detection, symptom control, and prevention of skeletal-related events, with demand shaped by the incidence and survivorship of breast, prostate, lung, renal, and thyroid cancers. Bone metastasis management increasingly blends systemic regimens with localized interventions, reflecting a growing emphasis on maintaining function and quality of life across extended treatment timelines. Care delivery is supported by multidisciplinary coordination across oncology, radiology, radiation oncology, orthopedic surgery, and palliative services, which expands addressable utilization across settings of care.
Adoption trends indicate continued expansion of imaging utilization for detection and longitudinal assessment, alongside broader use of systemic therapies that control primary disease while reducing progression-related skeletal complications. Procedural innovations also support a shift toward minimally invasive and outpatient pathways for selected patients, improving recovery timelines and enabling more frequent follow-up. Reimbursement variability and uneven access remain differentiators across regions, shaping the pace of uptake for advanced imaging and therapy combinations.
By Type Insights
Osteolytic Bone Metastasis accounted for the largest share of 48.7% in 2025. Osteolytic disease leads due to strong representation across high-incidence primary cancers and frequent association with clinically significant skeletal complications that require active intervention. Osteolytic lesion biology increases use of bone-modifying agents, pain management, and local control approaches, supporting sustained demand. Longer survival in metastatic settings also increases treated prevalence of osteolytic disease, expanding follow-on utilization across imaging, supportive care, and orthopedic stabilization where needed.
By Origin / Primary Cancer Insights
Breast Cancer accounted for the largest share of 34.2% in 2025. Breast cancer contributes a large share of bone metastasis burden because of high incidence and relatively long metastatic treatment durations that increase cumulative prevalence of bone involvement. Therapy sequencing across endocrine, targeted, and immunotherapy approaches can extend management timelines, increasing the need for supportive bone care and periodic reassessment. Clinical pathways also emphasize maintaining mobility and minimizing skeletal events, which expands demand for imaging-led monitoring and multidisciplinary interventions.
By Diagnosis Insights
Imaging accounted for the largest share of 72.9% in 2025. Imaging dominates diagnosis because detection, staging, and response monitoring in bone metastasis are imaging-led across most solid tumors. Cross-sectional and molecular imaging approaches support whole-body assessment and enable evaluation of treatment response over time. Imaging also guides local therapy selection, such as radiation planning and surgical decision-making, which increases repeat utilization. Biopsy and blood tests remain important adjuncts for confirmation and monitoring, but imaging remains the clinical workflow anchor.
By Treatment / Therapy Insights
Systemic Medical Therapy accounted for the largest share of 41.6% in 2025. Systemic regimens lead because systemic control of the underlying malignancy remains central to reducing progression-related skeletal complications and extending survival. Systemic therapy utilization spans multiple primary cancers and treatment lines, supporting broad applicability across patient populations. Combination approaches with radiation and supportive care are frequently used to manage pain and function, which increases total therapy intensity per patient. Expanding use of targeted, immune-based, and radiopharmaceutical modalities also supports continued diversification within systemic treatment mixes.
By End User Insights
Hospitals & Cancer Centers accounted for the largest share of 52.4% in 2025. Hospitals and cancer centers lead because multidisciplinary resources are concentrated in these settings, including oncology, advanced imaging, radiation oncology, and orthopedic surgery capabilities. Complex case management, inpatient stabilization, and advanced procedures are more frequently performed in hospital-based environments, sustaining higher utilization. Referral flows from community clinics to tertiary centers for escalation of care also reinforce concentration. Integrated care pathways support coordinated treatment plans and repeated follow-ups, further strengthening hospital and cancer center share.
Bone Metastasis Market Drivers
Rising metastatic cancer prevalence and longer survival in advanced disease
Rising incidence of major solid tumors and longer survival in metastatic settings increase the cumulative number of patients living with bone involvement. Bone metastasis treatment spans long timelines, increasing utilization of imaging, systemic therapy, radiation, and supportive care per patient. Longer disease duration raises demand for skeletal-related event prevention, pain control, and mobility preservation. Multiline therapy sequencing also increases the frequency of monitoring and care intensification, supporting sustained market expansion.
- For instance, a retrospective analysis of 5,246 breast cancer patients at MD Anderson Cancer Center reported that 28% developed bone metastases, and among these, median overall survival after bone involvement exceeded 3 years in hormone receptor–positive disease, significantly extending the time patients required ongoing imaging, systemic therapy adjustments, and skeletal-related event prevention.
Expansion of systemic oncology therapy options and deeper therapy-line utilization
Systemic treatment innovation expands the number of patients receiving active therapy across more lines, including targeted regimens, immunotherapy, and radiopharmaceutical approaches in selected indications. Broader systemic utilization increases the managed prevalence of bone metastasis and elevates demand for adjunctive supportive interventions. Systemic therapy use often triggers follow-on need for imaging reassessment and symptom-directed therapies. More personalized regimens also increase the role of multidisciplinary decision-making, supporting higher overall treatment intensity.
- For instance, the introduction of ^177Lu-PSMA-617 radioligand therapy in metastatic castration-resistant prostate cancer produced a complete response in 9.2% and partial response in 41.8% of treated patients versus 0% and 3% in the control arm, expanding the pool of patients benefitting from late-line active treatment.
Imaging-driven diagnosis, staging, and response monitoring workflows
Imaging-led detection and longitudinal monitoring remain central to clinical decision-making, supporting high utilization across the patient journey. More frequent staging and therapy-response assessments increase imaging volumes in both hospital and outpatient settings. Imaging also enables more precise selection of local therapies such as targeted radiation, ablation, and surgical stabilization. As care pathways standardize, imaging becomes increasingly protocolized, improving consistency of utilization across institutions.
Multidisciplinary care pathways and growth in supportive bone management
Bone metastasis management relies on coordination across oncology, radiology, radiation oncology, orthopedics, and palliative care, which expands the addressable treatment mix. Supportive therapies aimed at preventing skeletal events and maintaining function increase adoption across patient populations. Improved procedural techniques and perioperative pathways also expand intervention eligibility for stabilization and pain control. Structured follow-up frameworks increase repeat utilization across supportive care and monitoring services.
Bone Metastasis Market Challenges
Access and affordability constraints remain a persistent challenge, particularly for advanced imaging, radiopharmaceuticals, and specialized interventions that require experienced centers and reliable reimbursement. Differences in coverage policies and treatment availability create variation in care pathways, limiting standardized adoption across regions. Capacity limitations in specialist services, including nuclear medicine and orthopedic oncology, can delay treatment and reduce throughput for time-sensitive interventions.
- For instance, an IAEA-led global survey found that the number of nuclear medicine physicians ranges from 0 to 26.2 per million population across high‑income countries, highlighting severe workforce and access disparities between centers even within the same income group.
Clinical complexity also constrains scalability, as treatment selection depends on primary cancer type, extent of disease, patient performance status, and symptom burden. Treatment-related adverse events and contraindications can limit utilization of specific drug classes and procedures, requiring careful monitoring and therapy switching. Fragmentation between oncology and orthopedic pathways can create coordination gaps, affecting outcomes and increasing resource burden. Data integration limitations across imaging and clinical records further complicate longitudinal management in multi-site care networks.
Bone Metastasis Market Trends and Opportunities
Theranostics and radiopharmaceutical expansion represents a major opportunity as more targeted radioligand programs progress across oncology, particularly in prostate cancer populations frequently associated with bone disease. Increased availability of molecular imaging and improved patient selection workflows can support broader clinical adoption and more consistent monitoring. Combination strategies that pair systemic regimens with supportive bone management and localized control are also expanding, which increases total therapy intensity per patient.
Minimally invasive and outpatient-oriented approaches are gaining traction, supported by procedural innovation and demand for faster recovery and lower inpatient burden. Growth in ambulatory pathways for selected interventions can increase accessibility and throughput, particularly in markets pursuing value-based care. Improved coordination between community oncology clinics and tertiary centers also supports referral optimization and earlier escalation for stabilization and pain control. Digitalization of imaging workflows and treatment planning provides additional opportunities to improve efficiency and consistency across institutions.
- For instance, interventional radiology services that replace open surgery with image-guided procedures have demonstrated typical hospital stays of 0–1 day compared with 2–5 days for traditional surgery, while reducing recovery times to about 1–3 days versus 4–7 days, thereby allowing higher case volumes without proportional bed expansion.
Regional Insights
North America
North America represents an estimated 36.2% share in 2025, supported by strong access to advanced imaging, systemic therapies, and multidisciplinary oncology infrastructure. Care pathways are often standardized across large health systems, enabling repeat monitoring and consistent use of supportive bone management. Higher specialist density supports complex interventions such as targeted radiation, surgical stabilization, and selected minimally invasive therapies. Market performance is also supported by broader availability of novel systemic options and supportive care integration within oncology networks.
Europe
Europe accounts for an estimated 29.4% share in 2025, reflecting mature cancer care networks and guideline-driven management across major markets. The region supports robust utilization of imaging for staging and monitoring and maintains strong adoption of radiation therapy and supportive care pathways. Access differences across countries influence the pace of advanced modality uptake, but overall infrastructure remains strong. Continued investments in oncology services and pathway standardization support stable demand growth.
Asia Pacific
Asia Pacific holds an estimated 21.1% share in 2025, supported by expanding diagnostic capacity and rising oncology treatment volumes in large-population markets. Growth is reinforced by increasing adoption of standardized imaging workflows and broader availability of systemic oncology therapies. Infrastructure improvements in tertiary centers support multidisciplinary care and expansion of complex interventions. Variation in access and reimbursement remains a constraint, but capacity expansion supports steady share gains over time.
Latin America
Latin America represents an estimated 8.6% share in 2025, driven by concentrated oncology demand in major urban centers and referral hubs. Utilization is shaped by reimbursement variability and uneven access to advanced imaging and specialized therapies across countries. Private sector capacity and leading academic centers often anchor advanced care availability. Continued investment in oncology infrastructure and improved access to systemic therapies can expand treated prevalence and monitoring volumes.
Middle East & Africa
Middle East & Africa holds an estimated 4.7% share in 2025, reflecting uneven access to advanced oncology care outside key hubs. Specialized imaging and complex interventions remain concentrated in select countries and metropolitan centers. Gradual capacity buildout supports improving access, but reimbursement limitations and specialist availability remain constraints. Expansion of tertiary oncology centers and improved referral networks can increase adoption of structured bone metastasis management pathways.
Competitive Landscape
Competition in the Bone Metastasis Market is shaped by therapy portfolio depth, integration of supportive bone management with systemic oncology regimens, and the ability to fit into multidisciplinary clinical pathways. Companies compete through lifecycle management, clinical evidence generation, and alignment with evolving standards of care in metastatic settings. Differentiation is also driven by investments in imaging and theranostics ecosystems, procedural innovation for local control, and partnerships that expand access, workflow integration, and treatment sequencing.
Amgen Inc. remains a key participant through bone-directed supportive therapy positioning and continued efforts to defend and differentiate core assets amid shifting pricing and biosimilar dynamics. Amgen Inc. strategies emphasize sustaining clinical relevance through evidence, contracting discipline, and integration into oncology supportive care pathways that prioritize skeletal-event prevention and patient quality of life. Amgen Inc. also benefits from established provider familiarity in metastatic care settings, supporting stable utilization in high-access regions. Competitive pressure increasingly reflects contracting dynamics and evolving treatment algorithms that combine systemic control with supportive bone management.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Amgen Inc.
- Novartis AG
- F. Hoffmann-La Roche Ltd (Roche)
- Pfizer Inc.
- Merck & Co., Inc.
- Bayer AG
- Eli Lilly and Company
- Johnson & Johnson / Janssen (incl. DePuy Synthes, etc.)
- Medtronic plc
- Boston Scientific Corporation
- GE Healthcare
- Siemens Healthineers
- Koninklijke Philips N.V.
- BTG plc
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In February 2026, Bayer AG disclosed updated Phase III PEACE 3 trial results showing that its radiopharmaceutical XOFIGO (radium 223 dichloride), when combined with enzalutamide, provided a significant overall survival benefit versus enzalutamide alone in men with metastatic castration resistant prostate cancer with bone metastases
- In December 2025, in India, Zydus Lifesciences Ltd. announced the launch of Zyrifa, a biosimilar version of denosumab 120 mg (subcutaneous), a therapy used widely to reduce and delay skeletal related events in patients with solid tumors and multiple myeloma, thereby addressing complications that often include bone metastases and significantly affect cancer outcomes.
- In March 2025, in the United States, Fresenius Kabi Biopharma received FDA approval for its denosumab biosimilars Conexxence and Bomyntra (denosumab bnht), expanding access to lower cost biologic options for patients with bone metastases and other bone related conditions.
- In May 2024, in Melbourne, Australia, Telix Pharmaceuticals Limited completed the acquisition of QSAM Biosciences, gaining control of its lead radiopharmaceutical candidate Samarium 153 DOTMP (153Sm DOTMP), a targeted therapy being developed for primary and metastatic bone cancer and intended to strengthen Telix’s prostate cancer and bone metastasis care franchise.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 19,984.63 million |
| Revenue forecast in 2032 | USD 31,260.54 million |
| Growth rate (CAGR) | 6.6% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Type Outlook: Osteolytic Bone Metastasis, Osteoblastic Bone Metastasis, Mixed Bone Metastasis; By Origin / Primary Cancer Outlook: Breast Cancer, Prostate Cancer, Lung Cancer, Kidney (Renal) Cancer, Thyroid Cancer, Other Primary Cancers; By Diagnosis Outlook: Imaging, Biopsy, Blood Tests, Other; By Treatment / Therapy Outlook: Pharmacological Therapy, Radiation Therapy, Systemic Medical Therapy, Minimally Invasive/Local Ablation Therapies, Surgical & Orthopedic Interventions, Supportive & Palliative Care; By End User Outlook: Hospitals & Cancer Centers, Specialty & Orthopedic Clinics, Community Oncology Clinics, Ambulatory Surgical Centers, Homecare Settings |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Amgen Inc., Novartis AG, F. Hoffmann-La Roche Ltd (Roche), Pfizer Inc., Merck & Co., Inc., Bayer AG, Eli Lilly and Company, Johnson & Johnson / Janssen (incl. DePuy Synthes, etc.), Medtronic plc, Boston Scientific Corporation, GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., BTG plc |
| No. of pages | 325 |
Segmentation
By Type
- Osteolytic Bone Metastasis
- Osteoblastic Bone Metastasis
- Mixed Bone Metastasis
By Origin / Primary Cancer
- Breast Cancer
- Prostate Cancer
- Lung Cancer
- Kidney (Renal) Cancer
- Thyroid Cancer
- Other Primary Cancers
By Diagnosis
- Imaging
- Biopsy
- Blood Tests
- Other
By Treatment / Therapy
- Pharmacological Therapy
- Radiation Therapy
- Systemic Medical Therapy
- Minimally Invasive/Local Ablation Therapies
- Surgical & Orthopedic Interventions
- Supportive & Palliative Care
By End User
- Hospitals & Cancer Centers
- Specialty & Orthopedic Clinics
- Community Oncology Clinics
- Ambulatory Surgical Centers
- Homecare Settings
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Bone Metastasis Market in 2025 and the forecast for 2032?
What is the CAGR of the Bone Metastasis Market during 2025–2032?
What is the largest segment in the Bone Metastasis Market?
What factors are driving growth in the Bone Metastasis Market?
Which companies are leading participants in the Bone Metastasis Market?
Which region leads the Bone Metastasis Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 19,984.63 million → 2032: USD 31,260.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Bone Metastasis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Bone Metastasis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Bone Metastasis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Bone Metastasis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Bone Metastasis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Bone Metastasis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Bone Metastasis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Bone Metastasis Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 19,984.63 million → 2032: USD 31,260.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Bone Metastasis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Bone Metastasis Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Bone Metastasis Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Bone Metastasis Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

