
Market Overview
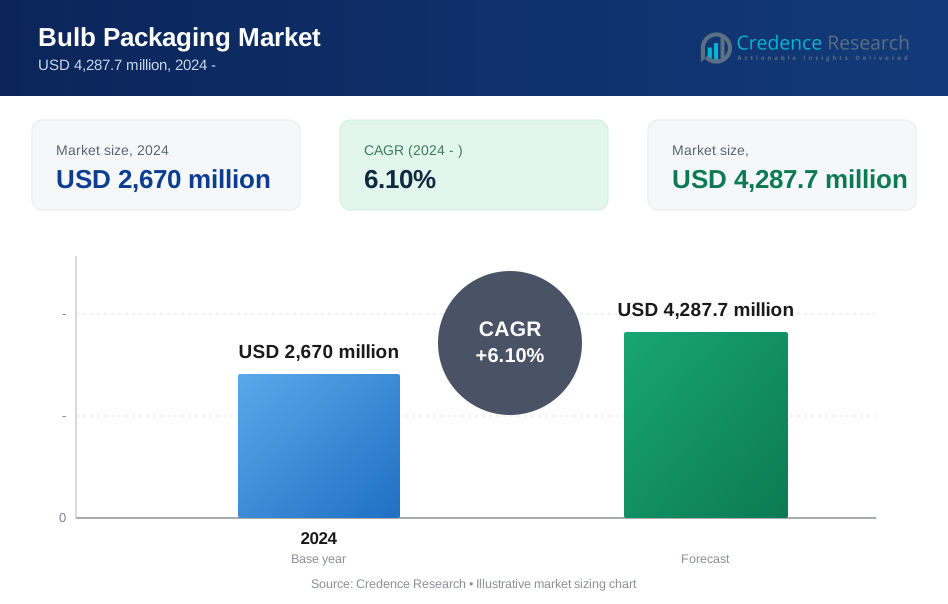
The bulb packaging market is projected to grow from USD 2,670 million in 2024 to USD 4,287.7 million by 2032, registering a CAGR of 6.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Bulb Packaging Market Size 2024 | USD 2,670 million |
| Bulb Packaging Market, CAGR | 6.1% |
| Bulb Packaging Market Size 2032 | USD 4,287.7 million |
The bulb packaging market is driven by rising global demand for energy-efficient lighting solutions, particularly LED bulbs, which require protective and sustainable packaging formats. Increased urbanization, infrastructure development, and smart home adoption are boosting the consumption of lighting products, thereby fueling the need for reliable and cost-effective packaging. Manufacturers are prioritizing eco-friendly materials and compact, recyclable designs to meet regulatory standards and consumer preferences for sustainable packaging. Growth in e-commerce and retail distribution channels is encouraging the development of tamper-proof, shock-resistant, and visually appealing packaging formats to ensure product integrity during transit. Trends shaping the market include the integration of smart labels and QR codes for product authentication and information access, along with advances in molded pulp and biodegradable packaging alternatives. The shift toward minimalistic, branded, and user-friendly packaging formats is also supporting premiumization strategies among lighting manufacturers. As sustainability gains prominence, companies are innovating in reusable and plastic-free packaging to align with circular economy goals.
The bulb packaging market spans North America, Europe, Asia Pacific, and other regions, with North America holding the largest share due to strong demand for LED lighting and robust e-commerce infrastructure. Europe follows with strict environmental regulations driving the adoption of recyclable packaging formats. Asia Pacific is rapidly expanding, led by manufacturing hubs in China and India and increasing demand for energy-efficient lighting. Key players operating in this market include Philips Lighting, Cree, Inc., Feit Electric Company, Inc., Acuity Brands, Inc., Havells India Ltd., Eaton Corporation, Hubbell Incorporated, General Electric Company, Nichia Corporation, Panasonic Corporation, Osram Licht AG, Zumtobel Group AG, and Toshiba Lighting & Technology Corporation. These companies focus on innovation in sustainable materials, smart packaging features, and protective designs to meet diverse regional needs and regulatory standards while maintaining strong global distribution capabilities.
Market Insights
- The bulb packaging market is projected to grow from USD 2,670 million in 2024 to USD 4,287.7 million by 2032, registering a CAGR of 6.1%.
- Rising adoption of energy-efficient LED bulbs is increasing the need for durable, eco-friendly packaging solutions that protect fragile components during transit.
- E-commerce growth is driving demand for tamper-proof, visually appealing, and compact packaging formats suitable for digital and retail distribution.
- Manufacturers are shifting toward recyclable, biodegradable, and molded pulp materials to meet regulatory requirements and consumer sustainability preferences.
- Volatile raw material prices and global supply chain disruptions are pressuring profit margins and slowing innovation, particularly for SMEs.
- North America leads the market with 34% share in 2024, followed by Europe at 28% and Asia Pacific at 25%, each region driven by distinct regulations and consumer behavior.
- Key players including Philips Lighting, Cree, Acuity Brands, Panasonic, and Havells are focusing on smart labeling, premium designs, and protective innovations to strengthen market position.
Market Drivers
Rising Demand for Energy-Efficient Lighting Solutions
The bulb packaging market is expanding due to the global transition toward energy-efficient lighting, particularly LED bulbs. Governments and regulatory agencies are enforcing stringent energy consumption standards, encouraging the replacement of conventional bulbs. This shift has increased the need for protective, durable, and eco-friendly packaging to ensure safe transportation and display of fragile lighting products. Manufacturers are responding with innovative packaging solutions that align with modern sustainability and efficiency expectations.
- For instance, major LED manufacturer Osram partnered with manufacturers of biodegradable packaging derived from plant-based sources, offering packaging that not only protects bulbs during shipping but also breaks down naturally post-use, catering to eco-conscious consumers and stricter environmental regulations.
Growth of E-Commerce and Retail Distribution Channels
The rapid growth of e-commerce platforms and organized retail outlets is driving the demand in the bulb packaging market. Online sales of lighting products require robust, tamper-resistant packaging to ensure product safety during last-mile delivery. Retailers also demand visually appealing and compact packaging for optimized shelf display. It is creating new opportunities for manufacturers to develop packaging that combines aesthetics with strength, catering to both digital and physical storefronts.
- For instance, brands like Otherland use custom, visually striking packaging for their candles that delivers a consistent and Instagram-worthy experience both on the shelf and through direct-to-consumer e-commerce, making their products attractive in retail displays and memorable for online customers alike.
Focus on Sustainability and Recyclable Materials
Increasing environmental concerns and regulatory pressures are prompting manufacturers in the bulb packaging market to shift toward recyclable and biodegradable materials. Consumers prefer packaging that aligns with green values and reduces plastic waste. It is pushing companies to adopt paper-based, molded pulp, and compostable options. Sustainable packaging not only enhances brand reputation but also ensures compliance with eco-labeling and waste reduction regulations across key global markets.
Product Fragility and Need for Impact-Resistant Packaging
Bulbs remain highly fragile and require packaging that minimizes breakage risks during handling and transport. The bulb packaging market is responding with innovations such as multi-layer corrugated boxes, air-filled compartments, and foam inserts. These designs protect bulbs from shocks, vibrations, and pressure fluctuations. It supports safe product delivery, reduces return rates, and improves customer satisfaction. The rising emphasis on quality assurance is sustaining demand for protective packaging technologies.
Market Trends
Increased Use of Sustainable and Biodegradable Packaging Materials
Sustainability is shaping product innovation in the bulb packaging market, with companies replacing plastic-based formats with recyclable, biodegradable, or compostable alternatives. Paperboard, molded pulp, and corrugated fiberboard are gaining traction due to their low environmental impact and compliance with global regulations. It promotes brand credibility and helps reduce landfill contribution. Manufacturers are also developing packaging with minimal ink usage and fewer non-recyclable coatings to simplify the recycling process and support circular economy initiatives.
- For instance, Tetra Pak conducted a 15-month commercial validation of a fiber-based barrier to replace aluminum layers in aseptic cartons, which achieved a significant reduction in CO₂ emissions while maintaining shelf life and protection standards.
Emphasis on Minimalistic and Shelf-Optimized Packaging Design
Retailers and manufacturers are emphasizing compact, minimalistic designs that reduce material usage while enhancing product visibility and branding. The bulb packaging market is aligning with retail demands for space efficiency, easy stacking, and clean aesthetics. Packaging innovations now focus on flat or stackable designs with die-cut windows that allow product inspection without opening. It helps drive impulse purchases and supports streamlined logistics by maximizing load capacity and reducing warehousing costs.
- For instance, Apple’s packaging uses clean lines and a limited color palette, focusing on the logo and product visibility, all while utilizing recycled paper and cardboard for reduced material waste.
Adoption of Smart Labels and Interactive Packaging Technologies
Smart packaging features such as QR codes, NFC tags, and augmented reality markers are entering the bulb packaging market to improve consumer engagement and product traceability. These technologies provide real-time product data, installation guidance, and authenticity checks. It enables brands to strengthen customer trust and streamline returns or replacements. Smart packaging also supports inventory tracking and logistics automation, creating operational efficiencies across the supply chain for both retailers and manufacturers.
Rising Customization and Private Label Packaging Demand
Brands are investing in customized packaging solutions tailored to specific product dimensions, wattages, and bulb types. The bulb packaging market is witnessing a surge in private-label and contract packaging activity driven by e-commerce growth. It supports brand differentiation and faster time-to-market for new product lines. Customized inserts, unique color schemes, and user-focused unboxing experiences are becoming essential elements in capturing customer attention and reinforcing product value across digital and physical sales channels.
Market Challenges Analysis
Fluctuating Raw Material Costs and Supply Chain Disruptions
The bulb packaging market faces significant pressure from volatile raw material prices, particularly for paperboard, plastics, and recycled content. Global supply chain disruptions, freight cost spikes, and shortages in sustainable materials increase production expenses and impact profit margins. It forces manufacturers to constantly adjust sourcing strategies and reevaluate supplier partnerships. Small and medium enterprises struggle to maintain price competitiveness amid fluctuating costs. This instability hinders long-term planning and weakens investment confidence across the packaging ecosystem.
Balancing Protection with Environmental Regulations
Packaging for bulbs must strike a careful balance between durability and sustainability, which remains a technical and cost challenge. The bulb packaging market must develop solutions that are lightweight, shock-resistant, and compliant with environmental regulations. Integrating protective features without relying on non-recyclable materials creates design and cost limitations. It requires ongoing R&D and innovation, which can delay product rollouts and increase time to market. Regulatory complexity across regions also complicates standardization efforts for eco-friendly packaging formats.
Market Opportunities
Expansion in Smart and Connected Lighting Solutions
The rapid growth of smart home technologies and connected lighting systems is creating new demand in the bulb packaging market. Products like smart LED bulbs, which often include electronics and sensors, require specialized packaging with added protection and tamper resistance. It opens opportunities for manufacturers to develop tailored solutions that meet the evolving technical needs of these products. Brands seek packaging that not only secures the device but also highlights smart features through integrated visuals and QR codes. This shift supports premium packaging formats that enhance consumer experience and perceived value.
Growing Demand for Eco-Friendly and Retail-Ready Formats
Sustainability trends and retail merchandising needs are driving innovation in eco-friendly, shelf-ready packaging across the bulb packaging market. Retailers prefer packaging that minimizes waste while ensuring ease of stocking, clear labeling, and strong shelf impact. It creates room for solutions like plastic-free blister packs, foldable cartons, and molded pulp inserts. Government mandates on recyclable content further accelerate the shift toward compliant and biodegradable materials. Companies that invest in scalable green packaging designs can access growing opportunities in both emerging and developed markets.
Market Segmentation Analysis:
By Material Type
The bulb packaging market segments by material into plastic, paper, glass, metal, and others, with plastic and paper leading due to their versatility and cost efficiency. Plastic offers high durability and transparency, supporting secure and visible packaging for retail. Paper-based materials are gaining traction due to their recyclability and alignment with sustainability mandates. Glass and metal are used in niche segments requiring aesthetic appeal or enhanced protection. It reflects a clear shift toward environmentally responsible materials in both primary and secondary packaging formats.
- For instance, Manik Printpack India Pvt. Ltd. manufactures LED bulb packaging boxes using recyclable cardboard, designed for protection against dust, water, and shock, and emphasizing eco-friendly, personalized prints to enhance brand visibility.
By Packaging Type
Boxes, blisters, clamshells, tubes, and others define the packaging type segments in the bulb packaging market. Boxes dominate due to their compatibility with multiple bulb types and efficient branding surfaces. Blisters and clamshells serve retail needs for visibility and tamper resistance, especially for single units. Tubes offer compactness and strength, suited for specialized or bulk packaging. It allows flexibility in design while ensuring shock absorption and ease of stacking across distribution channels.
- For instance, Philips redesigned its LED bulb packaging to be multifunctional and eco-friendly—its plastic packaging transforms into a reusable lampshade and uses no glue to minimize environmental impact.
By Application
Based on application, the bulb packaging market includes LED bulbs, incandescent bulbs, CFL bulbs, and others, with LED bulbs holding the largest share. Rising adoption of LED lighting drives demand for tailored packaging that offers thermal insulation, shock resistance, and eco-friendly properties. Incandescent and CFL bulbs still require traditional formats but are witnessing slower demand. It highlights the market’s ongoing shift toward energy-efficient and technologically advanced lighting solutions that require modernized packaging strategies.
Segments:
Based on Material Type
- Plastic
- Paper
- Glass
- Metal
- Others
Based on Packaging Type
- Boxes
- Blisters
- Clamshells
- Tubes
- Others
Based on Application
- LED Bulbs
- Incandescent Bulbs
- CFL Bulbs
- Others
Based on Distribution Channel
- Online Retail
- Offline Retail
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the bulb packaging market with a 34% share in 2024, supported by high demand for energy-efficient lighting and strong e-commerce infrastructure. The United States drives regional growth with widespread adoption of LED bulbs and strict environmental regulations on packaging waste. Retailers favor eco-friendly, shelf-ready designs, pushing innovation in recyclable and biodegradable formats. It benefits from established supply chains, advanced packaging technologies, and strong investments in smart lighting systems. Canada follows with similar trends in sustainable packaging and regulatory compliance. Manufacturers in the region focus on product protection, design aesthetics, and premium branding formats.
Europe
Europe holds 28% of the global bulb packaging market, driven by environmental directives and a well-developed lighting manufacturing base. Countries such as Germany, France, and the UK promote strict compliance with recyclable material use and minimal plastic content. Retailers demand sustainable formats that balance visual appeal with protective strength. It supports innovation in paper-based and molded pulp packaging, reducing landfill impact. Rising demand for LED lighting and smart bulbs is also boosting packaging customization. Local companies leverage automation and eco-labeling to meet regulatory benchmarks and retailer requirements.
Asia Pacific
Asia Pacific accounts for 25% of the bulb packaging market, fueled by rapid urbanization, infrastructure development, and strong production volumes of lighting products in China and India. Regional manufacturers are scaling packaging operations to meet both domestic and international demand. It witnesses increasing adoption of protective and cost-effective formats suited for high-volume exports. Government-led energy efficiency initiatives support the growth of LED bulb consumption, further expanding packaging needs. Japan and South Korea contribute to smart lighting and compact packaging innovation. Low-cost manufacturing advantages and expanding retail networks sustain regional growth.
Key Player Analysis
- Cree, Inc.
- Toshiba Lighting & Technology Corporation
- Feit Electric Company, Inc.
- Acuity Brands, Inc.
- Havells India Ltd.
- Eaton Corporation
- Hubbell Incorporated
- General Electric Company
- Nichia Corporation
- Panasonic Corporation
- Osram Licht AG
- Zumtobel Group AG
- Philips Lighting
Competitive Analysis
The bulb packaging market features a competitive landscape shaped by global lighting manufacturers and specialized packaging providers. Companies such as Philips Lighting, Cree, Inc., and Havells India Ltd. focus on integrating durable, eco-friendly, and retail-ready packaging into their product strategies. It drives innovation in recyclable materials, smart labeling, and compact formats tailored to LED and smart bulb technologies. Players like Feit Electric and Acuity Brands emphasize private-label and e-commerce-ready designs to expand their market reach. Osram Licht AG, Panasonic Corporation, and Nichia Corporation invest in automation and sustainable packaging to meet rising regulatory and consumer expectations. General Electric and Eaton Corporation prioritize tamper-resistant and high-strength packaging formats to support large-scale distribution. The market remains fragmented with regional players offering customizable and cost-effective solutions, while global leaders leverage brand recognition and supply chain efficiency. Strategic collaborations, material innovations, and differentiation through design remain central to maintaining competitiveness.
Recent Developments
- In December 2024, Berry partnered with VOID Technologies to introduce a high-performance recyclable PE film using VO+ technology for pet food packaging applications.
- In April 2025, Mondi completed the acquisition of Schumacher Packaging’s Western European operations, expanding its corrugated and solid board packaging capacity by over 1 billion square meters.
- In November 2024, Amcor entered into a partnership with Kolon Industries to co-develop sustainable flexible packaging materials, including chemically recycled PET (crPET) and biomass-based PEF.
- In April 2025, Amcor finalized its all-stock merger with Berry Global, forming a global packaging powerhouse with strengthened capabilities across consumer and healthcare sectors.
Market Concentration & Characteristics
The bulb packaging market exhibits moderate market concentration, with a mix of global lighting manufacturers and specialized packaging companies competing across regions. Leading players such as Philips Lighting, Cree, Havells India Ltd., and Acuity Brands maintain strong influence through large-scale operations, integrated supply chains, and continuous innovation in eco-friendly and protective packaging solutions. It features characteristics such as high demand elasticity driven by evolving lighting technologies and consumer preference for sustainable products. The market supports both standardized and custom packaging formats, addressing diverse requirements across smart LEDs, CFLs, and traditional bulbs. Companies compete on design functionality, material efficiency, regulatory compliance, and visual appeal. Innovation cycles are short due to rapid changes in lighting form factors and e-commerce distribution models. Small and mid-sized enterprises contribute through niche offerings and regional customization. The market rewards responsiveness to regulatory trends and packaging sustainability, while global distribution capabilities and automation remain key to scaling operations efficiently.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Packaging Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for eco-friendly and recyclable packaging materials will continue to rise due to tightening environmental regulations.
- Smart lighting growth will drive innovation in protective and feature-rich packaging for connected LED bulbs.
- E-commerce expansion will increase the need for tamper-proof and durable packaging formats.
- Companies will invest in automation to enhance packaging speed, accuracy, and cost-efficiency.
- Minimalistic and compact packaging designs will gain popularity across retail and digital shelves.
- Paper-based and molded pulp materials will replace conventional plastic in many product lines.
- Custom packaging solutions tailored to bulb type, wattage, and smart features will see higher demand.
- Brands will adopt smart labels, QR codes, and digital packaging to improve user engagement and product authentication.
- Regional players will expand by offering localized, sustainable, and cost-effective packaging formats.
- Regulatory compliance will shape design choices and material sourcing strategies across global markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the bulb packaging market?
What are the key segments within the bulb packaging market?
What are some challenges faced by the bulb packaging market?
Who are the major players in the bulb packaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bulb Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bulb Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,670 million → forecast year: USD 4,287.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bulb Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bulb Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bulb Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bulb Packaging Market Drivers
- 3.3 Bulb Packaging Market Restraints & Challenges
- 3.4 Bulb Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bulb Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bulb Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bulb Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bulb Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bulb Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bulb Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bulb Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bulb Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bulb Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bulb Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bulb Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bulb Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bulb Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bulb Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bulb Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bulb Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bulb Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bulb Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bulb Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
