
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
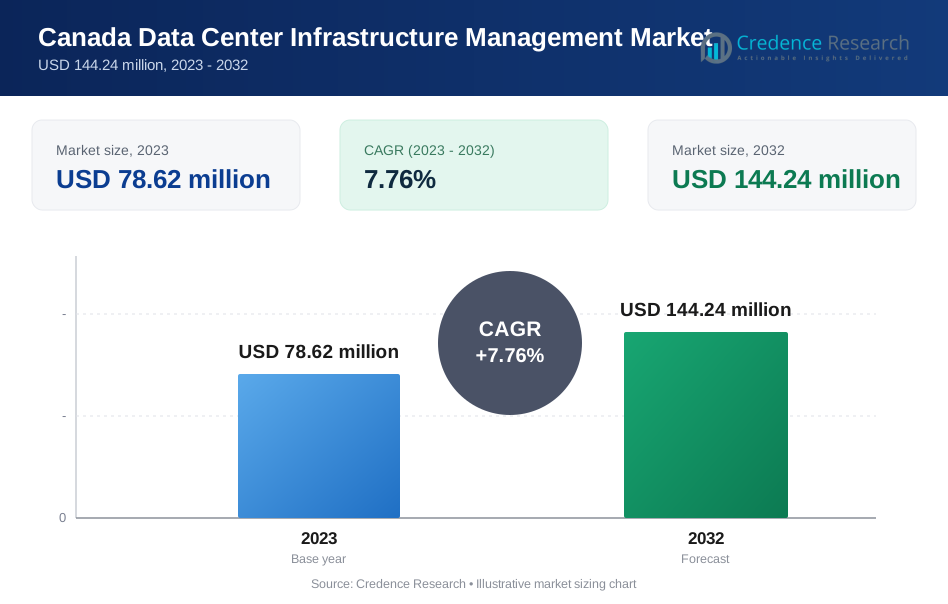
| Canada Data Center Infrastructure Management Market Size 2024 | USD 78.62 Million |
| Canada Data Center Infrastructure Management Market, CAGR | 7.76% |
| Canada Data Center Infrastructure Management Market Size 2032 | USD 144.24 Million |
Market Overview
The Canada Data Center Infrastructure Management Market is projected to grow from USD 78.62 million in 2023 to USD 144.24 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.76%.
The Canada Data Center Infrastructure Management Market is experiencing robust growth, driven by the increasing demand for cloud services and the need for efficient data management solutions in light of escalating data volumes from various digital sources. Trends such as the adoption of AI and IoT technologies are propelling the market forward by enhancing data center operational efficiencies and sustainability. Moreover, the push towards energy-efficient and environmentally friendly data center practices is becoming increasingly significant, as businesses seek to reduce energy consumption and adhere to stringent environmental regulations, ensuring sustained growth in the sector.
The Canada Data Center Infrastructure Management Market is geographically concentrated in regions like Ontario and Quebec, which are hubs for technological innovation and sustainable practices. Key players such as ABB, Schneider Electric, and IBM dominate the market, driving forward with robust solutions that cater to the rising demand for efficient and environmentally friendly data center operations. These companies lead in developing and implementing advanced management technologies that optimize data center performance and energy usage, aligning with Canada's focus on sustainability and high-tech infrastructure development. Their efforts are critical in shaping the competitive landscape and setting industry standards across the region.
Market Drivers
Rapid Digital Transformation Driving Infrastructure Demand
Canada's data center market is vigorously expanding, primarily driven by the increasing reliance on cloud services. The surge in cloud computing necessitates robust data centers designed to support extensive cloud infrastructure effectively. For instance, the Government of Canada’s “cloud-first” strategy prioritizes cloud services for IT investments, which has significantly increased the demand for scalable data storage solutions. Moreover, the proliferation of data-intensive applications, including AI, IoT, and big data analytics, further compels the need for advanced data center capabilities. These technologies require substantial data processing resources, thus pushing the demand for well-equipped data centers that can handle high-volume, complex data operations efficiently.
Government Initiatives Boosting Data Center Developments
Government-led initiatives aimed at enhancing digital infrastructure significantly contribute to the growth of data centers in Canada. Investments by the government to bolster digital infrastructure are intended to propel economic growth and technological advancement. Additionally, the increasing focus on data sovereignty compels organizations to establish data centers within Canada. For instance, the Data Centre Consolidation Initiative by Shared Services Canada aims to modernize IT infrastructure by closing aging data centers and migrating applications to modern hosting solutions. This trend is driven by the need to comply with local regulations that mandate data to be stored and processed within national borders, ensuring regulatory compliance and data security.
Emphasis on Energy Efficiency in Data Center Operations
As energy costs rise, data center operators in Canada are increasingly turning to Data Center Infrastructure Management (DCIM) solutions to optimize energy consumption and minimize operational expenditures. The integration of renewable energy sources presents a viable opportunity for data centers to leverage green energy, aligning with global sustainability trends. This shift not only reduces the environmental impact but also enhances the energy efficiency of data center operations, making them more cost-effective and less reliant on traditional energy sources.
Advancements and Consolidation in Data Center Management
Organizations are focusing on consolidating their data center infrastructure to streamline operations and improve overall efficiency. This consolidation allows for significant cost reductions and enhances the management capabilities of data centers. Furthermore, advancements in DCIM technology, such as the integration of AI and machine learning, provide predictive analytics and proactive maintenance, enhancing operational efficiency. The use of IoT-enabled sensors and automation technologies also plays a crucial role in improving data center operations by minimizing human error and optimizing performance.
Market Trends
Sustainable Practices and Technological Integration in Data Centers
Sustainability initiatives are becoming increasingly critical in the operation of data centers in Canada. Operators are focusing more on implementing energy-efficient practices and integrating renewable energy sources to not only reduce operating costs but also minimize environmental impact. For instance, a recent survey of 825 multi-tenant data center operators by S&P found that 43 percent have sustainability initiatives in place, with some targeting a 50 percent reduction in carbon emissions from data center construction by 2025. These green data centers utilize DCIM solutions to monitor and manage their carbon footprint effectively. Concurrently, the rise of edge computing is reshaping the landscape, driving the demand for micro data centers that bring computing capabilities closer to data sources. These developments necessitate specialized DCIM solutions tailored for managing the unique challenges of edge computing environments. Additionally, the integration of IoT and smart infrastructure into DCIM platforms is transforming data center operations. This integration facilitates real-time monitoring and control, providing operators with enhanced visibility and improved control over their data center environments, thus optimizing performance and reliability.
Advancements in DCIM Technology Enhance Efficiency and Security
The rapid adoption of cloud-based DCIM solutions marks a significant trend within the Canada Data Center Infrastructure Management Market. These solutions offer unparalleled scalability and flexibility, accommodating the dynamic needs of modern data centers without the burden of substantial upfront investments. Additionally, the integration of AI and machine learning has revolutionized data center management by enabling predictive analytics. This technology not only anticipates potential system failures but also optimizes energy usage and overall operational efficiency. AI-powered automation further streamlines processes and reduces the incidence of human error, setting a new standard for operational excellence in data center management. Moreover, robust cybersecurity measures are now integral to DCIM platforms, enhancing the security of data centers against increasing cyber threats while ensuring compliance with stringent data privacy regulations such as GDPR and PIPEDA.
Market Challenges Analysis
Navigating Regulatory and Resource Challenges in Data Center Operations
The Canadian Data Center Infrastructure Management Market is increasingly impacted by a complex regulatory landscape, particularly concerning data privacy and security. Compliance with stringent regulations is both complex and costly, necessitating continuous oversight and adaptation by data center operators. Additionally, cross-border data transfer regulations pose further challenges, complicating operations for data centers that handle international data flows. This regulatory environment requires robust compliance strategies to mitigate potential legal and operational risks. Furthermore, infrastructure constraints significantly affect data center functionality. Ensuring a reliable power supply, especially in more remote or less developed regions, remains a critical challenge. Similarly, the availability of high-speed internet connectivity, crucial for efficient data center operations, is not consistent across all areas, posing significant barriers to operational efficiency and expansion.
Addressing Talent Scarcity and the Cost of Technological Advancements
The sector also grapples with a notable talent shortage, where specialized skills in data analytics, cloud computing, and cybersecurity are in high demand but scarce supply. This scarcity is exacerbated by intense competition for skilled professionals, particularly in major urban centers, driving up recruitment costs and complicating talent retention and development. For instance, CBRE Canada reports that the average monthly asking rate for a 250- to 500-kW requirement across primary markets increased by 14.5% year-over-year, reflecting the high cost of suitable real estate and energy expenses. High operating costs further compound these challenges, with energy expenses and the high cost of suitable real estate in urban locales significantly impacting profitability and operational scalability. As data centers are inherently energy-intensive, there is also growing concern over their environmental impact, prompting a push towards more sustainable operational practices. However, implementing these green initiatives can be costly and complex, particularly for existing data centers that need to retrofit or upgrade legacy systems to newer, more energy-efficient technologies. This rapid pace of technological advancement requires continuous investment to keep up with industry standards and innovations, further straining resources and emphasizing the need for strategic planning in technology adoption and energy management.
Market Segmentation Analysis:
By Component:
In the Canada Data Center Infrastructure Management Market, the segmentation by component underscores the growing reliance on both solutions and services. Solutions within this segment encompass a range of software tools designed to optimize data center operations, including monitoring, management, and automation functionalities. These solutions are crucial for enhancing operational efficiency and ensuring high availability and reliability of data center resources. On the other hand, services play a pivotal role in the deployment, operation, and maintenance of these solutions. Services include consulting, integration, support, and managed services that help organizations tailor their data center operations to meet specific needs and challenges, thereby enhancing overall operational effectiveness and scalability.
By Application:
The application-based segmentation of the Canada Data Center Infrastructure Management Market covers several crucial areas. Asset management and capacity management are central to ensuring that data centers can scale resources effectively and maintain optimal utilization rates without compromising service delivery. Power and environment monitoring are equally important, providing data centers with the ability to optimize energy usage and maintain the necessary environmental conditions for equipment safety and efficiency. Additionally, BI and analytics applications offer valuable insights into operations, improving decision-making and operational foresight. The 'Others' category typically includes security and network management, underscoring the comprehensive approach needed in modern data center operations to address all facets of infrastructure management and data security.
Segments:
Based on Component:
- Solutions
- Services
Based on Application:
- Asset Management
- Capacity Management
- Power Monitoring
- Environment Monitoring
- BI and Analytics
- Others
Based on End-user:
- Enterprise Data Center
- Managed Data Center
- Colocation Data Center
- Cloud and Edge Data Center
Based on Deployment:
- On-premise
- Cloud
Based on Enterprise:
- Small and Medium-Sized Enterprises (SMEs)
- Large-Sized Enterprise
Based on Distribution Channel:
- BFSI
- Government and Public Sector
- IT and ITeS
- Healthcare and Life Sciences
- Others
Based on the Geography:
- Western Provinces (British Columbia, Alberta, Saskatchewan, Manitoba)
- Ontario
- Eastern Provinces (Quebec, Nova Scotia, New Brunswick, Prince Edward Island, Newfoundland and Labrador)
- Northern Territories (Yukon, Northwest Territories, Nunavut)
Regional Analysis
Ontario stands out, commanding approximately 40% of the market share. The province's economic vibrancy and the dense clustering of technology firms and financial institutions, particularly in Toronto, fuel the demand for advanced data management solutions. This high concentration of tech-driven enterprises generates considerable data traffic, necessitating robust data handling capabilities and sophisticated infrastructure management solutions. Ontario's market dominance is further reinforced by its role as a critical node in Canada’s overall tech and innovation strategy, positioning it as a central hub for technological advancements and data center developments.
Quebec captures around 25% of the market share, setting a benchmark with its emphasis on renewable energy and sustainable practices. This focus is strategically aligned with the global shift towards sustainability, attracting companies dedicated to greener data center operations. Quebec's proactive government policies and incentives designed to foster tech investments create a nurturing environment for the growth and development of data center infrastructures. The region's commitment to integrating eco-friendly practices into its technological growth not only enhances its appeal to environmentally conscious companies but also cements its role as an influential market player in fostering sustainable innovations within the Canada Data Center Infrastructure Management Market.
Key Player Analysis
- ABB
- Schneider Electric
- Vertiv Group Corp.
- Nlyte Software
- FNT Software
- Siemens
- IBM
- Sunbird Software, Inc.
- Intel Corporation
- Fujitsu
- Microsoft
Competitive Analysis
In the competitive landscape of the Canada Data Center Infrastructure Management Market, leading players such as ABB, Schneider Electric, IBM, Vertiv Group Corp., Nlyte Software, FNT Software, Siemens, Sunbird Software, Inc., Intel Corporation, Fujitsu, and Microsoft are instrumental in shaping market dynamics. These companies leverage their extensive product portfolios and technological expertise to meet the diverse needs of data centers, emphasizing innovations in efficiency and sustainability. Their strategic initiatives, including mergers, acquisitions, and collaborations, enhance their market reach and service offerings, allowing them to effectively compete and maintain their leadership positions. By continuously evolving their DCIM solutions to incorporate the latest in AI, machine learning, and IoT technologies, these key players not only address the current demands of data center operations but also anticipate future trends, thereby securing a competitive edge in the Canadian market.
Recent Developments
- In July 2024, Vertiv launched the MegaMod™ CoolChip, a high-density prefabricated modular data center solution designed to accelerate global deployment of AI compute.
- In August 2024, FNT Software released FNT Command 14, a platform with sustainability enhancements and improved usability features for managing IT, data center, and telecommunication infrastructures.
- In July 2024, Siemens strengthened its data center presence with the launch of a new Center of Competence in the APAC region.
- In April 2024, IBM announced plans to open a new Cloud Multizone Region (MZR) in Montreal, Quebec, to help Canadian enterprises leverage generative AI and address data sovereignty requirements.
- In November 2023, Schneider Electric announced a $3 billion multi-year agreement with Compass Datacenters to expand their partnership and manufacture prefabricated modular data center solutions.
Market Concentration & Characteristics
The Canada Data Center Infrastructure Management Market exhibits a high level of market concentration, dominated by a few major players such as ABB, Schneider Electric, and IBM. These leading companies wield significant influence over market dynamics through their comprehensive product offerings and robust technological capabilities. The market is characterized by a strong focus on innovation and sustainability, with top firms investing heavily in research and development to integrate advanced technologies like AI and IoT into their solutions. This concentration fosters a competitive environment where continual improvements in data center efficiency and energy management are paramount. Additionally, the presence of these key players drives the adoption of high standards and practices across the industry, ensuring that Canadian data centers align with global trends towards smarter, more sustainable infrastructure management.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-user, Deployment, Enterprise, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in cloud services adoption will drive demand for sophisticated DCIM solutions.
- Expansion of AI and machine learning integration will enhance predictive maintenance and operational efficiency.
- Increased focus on sustainability will push for further adoption of green data center technologies.
- Growth in IoT adoption will lead to more complex data management needs, boosting DCIM demand.
- Rising energy costs will emphasize the importance of energy-efficient DCIM solutions.
- Regulatory changes regarding data privacy and security will necessitate updates in DCIM implementations.
- Expansion of edge computing will require new approaches to DCIM for managing distributed infrastructure.
- Technological advancements in networking and connectivity will improve DCIM real-time monitoring capabilities.
- Larger investment in cyber security measures within DCIM tools to safeguard data integrity.
- Ongoing digital transformation across industries will continue to drive the overall market growth for DCIM solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Data Center Infrastructure Management Market?
What factors are driving the growth of the Canada Data Center Infrastructure Management Market?
What are the key segments within the Canada Data Center Infrastructure Management Market?
What are some challenges faced by the Canada Data Center Infrastructure Management Market?
Who are the major players in the Canada Data Center Infrastructure Management Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Data Center Infrastructure Management Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Data Center Infrastructure Management Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 78.62 million → 2032: USD 144.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Data Center Infrastructure Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Data Center Infrastructure Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Data Center Infrastructure Management Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Data Center Infrastructure Management Market Drivers
- 3.3 Canada Data Center Infrastructure Management Market Restraints & Challenges
- 3.4 Canada Data Center Infrastructure Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Data Center Infrastructure Management Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Data Center Infrastructure Management Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Data Center Infrastructure Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Data Center Infrastructure Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Data Center Infrastructure Management Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Data Center Infrastructure Management market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Data Center Infrastructure Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Data Center Infrastructure Management Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Data Center Infrastructure Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Data Center Infrastructure Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Data Center Infrastructure Management Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Data Center Infrastructure Management Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Data Center Infrastructure Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Data Center Infrastructure Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Data Center Infrastructure Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Data Center Infrastructure Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Data Center Infrastructure Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Data Center Infrastructure Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Data Center Infrastructure Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
