
Market Overview
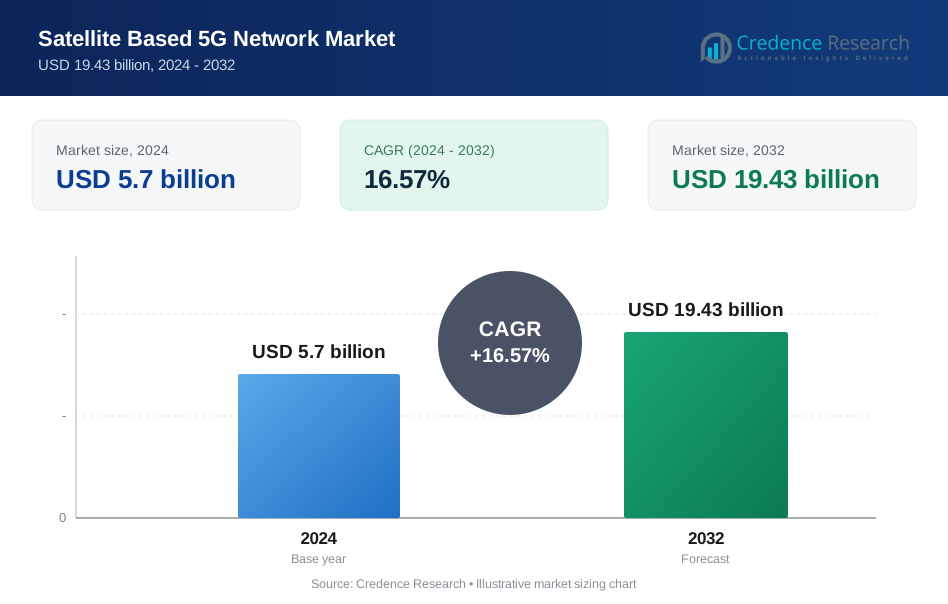
Satellite Based 5G Network Market size was valued USD 5.7 billion in 2024 and is anticipated to reach USD 19.43 billion by 2032, at a CAGR of 16.57% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Based 5G Network Market Size 2024 | USD 5.7 Billion |
| Satellite Based 5G Network Market, CAGR | 16.57% |
| Satellite Based 5G Network Market Size 2032 | USD 19.43 Billion |
The Satellite Based 5G Network Market is driven by top players including Anritsu Corporation, MediaTek Inc., Echostar Corporation, Softbank Group, Telefonaktiebolaget LM Ericsson, Thales, Qualcomm Technologies, Inc., ZTE Corporation, Keysight Technologies, and Intelsat. These companies focus on technological innovation, multi-orbit satellite deployment, and strategic collaborations to strengthen network coverage and reduce latency. Advanced payloads, IoT-enabled solutions, and integrated hardware-software offerings enhance service reliability and scalability. North America leads the market, holding a 36% share, supported by robust infrastructure, high adoption of 5G services, and early satellite-terrestrial integration initiatives. The combination of regional technological maturity, investment in R&D, and strong presence of leading market players positions North America as a key hub for satellite-based 5G commercialization, influencing global market trends and competitive dynamics.
Market Insights
- The Satellite Based 5G Network Market was valued at USD 5.7 billion in 2024 and is expected to reach USD 19.43 billion by 2032, growing at a CAGR of 16.57% during the forecast period.
- Market growth is driven by technological innovation, multi-orbit satellite deployment, and IoT-enabled solutions, enhancing network coverage and reducing latency.
- Key trends include strategic partnerships, integrated hardware-software offerings, and increasing adoption of satellite-terrestrial hybrid networks for enterprise and consumer broadband.
- Competitive intensity is high, with top players like Anritsu Corporation, MediaTek Inc., Echostar Corporation, Softbank Group, Ericsson, Thales, Qualcomm, ZTE, Keysight Technologies, and Intelsat focusing on R&D, network expansion, and advanced payload development.
- North America leads with a 36% market share, followed by Europe and Asia Pacific; LEO satellites dominate the satellite type segment, and consumer broadband holds the largest application share, reflecting high regional adoption and technology maturity.

Market Segmentation Analysis:
By Satellite Type
Low Earth Orbit (LEO) satellites dominate the satellite-based 5G network market, accounting for over 53% of the market share in 2024. Their low latency and high data transfer speeds make them ideal for 5G applications. Companies like SpaceX and OneWeb heavily invest in LEO satellites to provide seamless global internet connectivity and support 5G networks.Medium Earth Orbit (MEO) satellites are the fastest-growing segment, with a projected CAGR of over 52% from 2024 to 2032. They offer reliable, low-latency communication solutions, crucial for isolated and underserved areas. MEO satellites are used by companies such as SES's O3b Networks to provide dependable, low-latency communication solutions.
- For instance, LEO satellites are pivotal in satellite-based 5G networks, offering low latency and high data transfer speeds. Anritsu has developed the MT8000A, a 5G NR test platform that supports NTN testing, enabling the validation of LEO satellite communications.
By Frequency Band
The Ka-band leads the satellite-based 5G network market, holding the largest revenue share of 25.9% in 2024. Its ability to support high-throughput data transmission and provide wide bandwidth makes it ideal for high-speed internet services. Ka-band operates at higher frequencies, typically between 26.5 GHz and 40 GHz, allowing for significantly faster internet speeds and greater data capacity compared to lower frequency bands.The Ku-band segment dominated the market in 2024, covering frequencies ranging from 10.7 to 14.5 GHz. Its application in fixed satellite television data services drives market growth. The Ku-band is ideal for delivering high-quality broadcast signals, making it an ideal choice for fixed satellite television services.
- For instance, MediaTek's MT6825 chipset, compliant with 3GPP Release-17, operates in the L- and S-bands, facilitating two-way satellite communication for IoT applications.
By Application
The Consumer Broadband segment is projected to contribute 47.3% of the market revenue in 2025, holding the largest share among applications. Growth in this segment has been propelled by rising demand for high-speed internet access in remote and rural areas where terrestrial 5G coverage is limited. Consumers increasingly require reliable broadband for streaming, telecommuting, and online education, creating a strong market for satellite-based 5G services.The Enterprise Broadband segment is also significant, driven by the need for reliable and secure communication networks. Satellite-based 5G networks offer enterprises the ability to maintain connectivity in remote locations, enhancing business continuity and operational efficiency. This segment is expected to witness substantial growth as businesses increasingly adopt satellite-based solutions for their communication needs.
Key Growth Drivers
Rising Demand for Global Connectivity
The surge in demand for reliable high-speed connectivity across urban and remote regions drives the satellite-based 5G network market. Businesses, governments, and consumers seek uninterrupted broadband for enterprise operations, e-learning, and telemedicine. For instance, SpaceX’s Starlink expansion provides low-latency internet to rural areas, enhancing digital inclusion. Telecommunications providers invest in LEO satellite constellations to bridge network gaps. This demand encourages partnerships between satellite operators and mobile network providers, expanding coverage and fostering innovations in satellite-ground integration. Market expansion is fueled by continuous infrastructure development.
- For instance, SoftBank launched Eutelsat OneWeb satellite connectivity services in Japan, offering eight service plans with communication speeds up to 195 Mbps downlink and 32 Mbps uplink.
Technological Advancements in Satellite Communications
Advancements in satellite technologies, including miniaturized LEO satellites, high-throughput Ka-band payloads, and AI-driven network optimization, boost market growth. For instance, OneWeb deploys over 600 LEO satellites to enhance latency and coverage for enterprise broadband. Enhanced satellite antennas and beamforming techniques allow higher data rates and efficient spectrum usage. Continuous innovation in ground stations and inter-satellite links strengthens network reliability. These developments attract telecom operators to integrate satellite 5G networks with terrestrial systems, increasing service offerings and creating new revenue streams globally.
- For instance, Ericsson, Qualcomm Technologies, and Thales Alenia Space achieved a significant milestone by establishing a 3GPP-based end-to-end New Radio (NR) 5G non-terrestrial network (NTN) call using a lab-emulated low Earth orbit (LEO) satellite.
Expansion of Enterprise and Government Applications
Enterprise and governmental adoption of satellite 5G networks drives growth across sectors like defense, logistics, and maritime. Governments use satellite networks for disaster management, border monitoring, and secure communications. For instance, SES Networks enables maritime broadband for shipping fleets, supporting navigation and operational data exchange. Enterprises leverage satellite 5G for remote site connectivity and IoT deployments. Growing demand for industrial automation and cloud-based operations across remote locations reinforces the need for high-capacity, low-latency satellite communication solutions, expanding the market footprint worldwide.
Key Trends & Opportunities
Integration with IoT and Edge Computing
Integration of satellite 5G networks with IoT and edge computing creates significant opportunities. For instance, Viasat’s satellite-enabled IoT solutions enhance monitoring of remote assets with low-latency connectivity. Industrial applications such as smart agriculture, oil and gas, and transportation increasingly adopt satellite 5G for real-time data transmission. Edge computing allows local data processing, reducing network congestion and latency. Providers are exploring hybrid satellite-terrestrial models to serve enterprise clients efficiently. This trend unlocks new applications, stimulates investments, and increases market potential for satellite-enabled intelligent networks globally.
- For instance, Qualcomm launched the 212S and 9205S modem chipsets, enabling satellite IoT connectivity and designed for ultra-low-power operations in applications such as remote monitoring and asset tracking.
Adoption of Low Earth Orbit (LEO) Constellations
LEO satellite constellations dominate market opportunities due to lower latency and higher bandwidth capabilities. For instance, Telesat’s LEO network targets enterprise and government sectors, providing faster data transmission than GEO satellites. The proliferation of LEO networks encourages telecom operators to partner with satellite providers, expanding broadband access to underserved areas. Companies focus on satellite miniaturization, launch efficiency, and constellation density to reduce costs. This trend accelerates global satellite 5G deployment, enabling new services in education, healthcare, and emergency response while reducing digital divides in remote regions.
- For instance, ZTE has developed a 3GPP-compliant 5G NTN solution that facilitates direct communication between existing mobile terminals and satellites without requiring hardware modifications.
Key Challenges
High Capital Expenditure and Infrastructure Costs
Deploying satellite-based 5G networks requires significant capital investment in satellite manufacturing, launches, and ground infrastructure. High upfront costs limit participation to major players, restricting market competitiveness. For instance, SpaceX invested billions to deploy and maintain its Starlink constellation, covering launch vehicles, satellite design, and ground terminals. Smaller operators face barriers due to limited funding and technical expertise. Additionally, maintaining large constellations requires continuous operational expenditure. These financial and logistical challenges may delay network expansion, especially in emerging economies, and restrict adoption across price-sensitive segments.
Regulatory and Spectrum Management Challenges
Complex international regulations and spectrum allocation constraints hinder rapid satellite 5G deployment. Different countries have varying licensing requirements, orbital slot restrictions, and spectrum policies. For instance, coordinating Ka-band frequencies across regions requires negotiation with multiple regulatory bodies. Interference with terrestrial networks and neighboring satellite systems further complicates operations. Navigating compliance while maintaining low-latency services increases operational complexity. Such regulatory and spectrum management challenges slow deployment schedules, limit market entry for new players, and may impact overall adoption of satellite-based 5G networks globally.
Regional Analysis
North America
North America leads the satellite-based 5G network market, holding a 35.4% share by 2035. This dominance stems from significant technological advancements and a supportive regulatory environment. The U.S. and Canada are investing heavily in satellite infrastructure to enhance connectivity in underserved areas. Key players like SpaceX's Starlink and OneWeb are expanding their Low Earth Orbit (LEO) satellite constellations, aiming to provide high-speed internet across remote regions. These initiatives are expected to drive substantial growth in the region's market share over the forecast period.
Europe
Europe is witnessing rapid growth in the satellite-based 5G network sector, with Germany leading the market. The European Commission's IRIS² program, which includes 270 LEO satellites, is a significant driver of this expansion. Countries like the UK and France are investing in satellite infrastructure to enhance rural connectivity. Collaborations among satellite operators and telecom providers are accelerating the deployment of 5G services, aiming to bridge digital divides and improve service quality across the continent.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for satellite-based 5G networks, driven by increasing demand for high-speed internet in rural and remote areas. Countries like China and India are investing heavily in satellite infrastructure to enhance connectivity. The deployment of LEO satellites is a key strategy to provide reliable internet services in underserved regions. Public and private sector collaborations are accelerating the rollout of satellite-based 5G networks, positioning the region for significant market share growth.
Latin America
Latin America is experiencing steady growth in the satellite-based 5G network market, with Brazil at the forefront. The country's telecom sector is characterized by high mobile penetration, with over 250 million subscriptions serving a population of 215 million. The expansion of 5G services, launched in major cities in 2022, has accelerated data consumption, increasing demand for satellite-based connectivity solutions. Strategic partnerships and investments are expected to drive further market development in the region.
Middle East & Africa
The Middle East and Africa region is witnessing significant growth in the satellite-based 5G network market, driven by investments in infrastructure and increasing demand for high-speed internet. Countries like Saudi Arabia, South Africa, and the UAE are leading the market, with robust satellite infrastructure supporting military, commercial, and government sectors. The trend toward LEO satellites is reshaping the satellite communications landscape, enhancing connectivity in remote and underserved areas.
Market Segmentations:
By Satellite Type:
- Low Earth Orbit (LEO) satellites
- Medium Earth Orbit (MEO) satellites
By Frequency Band:
- Ku-band
- Ka-band
By Application:
- Consumer broadband
- Enterprise broadband
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Satellite Based 5G Network Market players such as Anritsu Corporation, MediaTek Inc., Echostar Corporation, Softbank Group, Telefonaktiebolaget LM Ericsson, Thales, Qualcomm Technologies, Inc., ZTE Corporation, Keysight Technologies, and Intelsat dominate. The Satellite Based 5G Network Market is highly competitive, driven by rapid technological advancements and growing demand for seamless global connectivity. Companies are focusing on developing high-throughput satellite systems, multi-orbit network integration, and low-latency solutions to meet consumer and enterprise requirements. Strategic collaborations, joint ventures, and spectrum-sharing agreements are increasingly adopted to expand coverage and improve service reliability. Investment in research and development ensures continuous innovation in satellite payloads, ground infrastructure, and signal processing technologies. Market players prioritize scalability, energy efficiency, and compatibility with terrestrial 5G networks to gain a competitive edge. Additionally, the emphasis on enterprise broadband, IoT applications, and remote connectivity solutions accelerates market growth. Continuous improvement in satellite testing, measurement, and deployment practices strengthens service quality, enhances operational efficiency, and positions providers to capture emerging opportunities in both consumer and industrial segments.
Key Player Analysis
- Anritsu Corporation
- MediaTek Inc.
- Echostar Corporation
- Softbank Group
- Telefonaktiebolaget LM Ericsson
- Thales
- Qualcomm Technologies, Inc.
- ZTE Corporation
- Keysight Technologies
- Intelsat
Recent Developments
- In June 2025, Rohde & Schwarz will host its fifth Satellite Industry Day, spotlighting the intersection of 5G NTN and satellite testing. The event will feature industry experts addressing key challenges in NTN evolution and the transition toward 6G.
- In April 2025, Amazon's Project Kuiper announced the deployment of its first batch of operational satellites, a significant step in the market. This initiative aims to enhance global connectivity using a constellation of LEO satellites, delivering high-speed internet to underserved regions.
- In February 2025, Eutelsat Group conducted a successful global 5G NTN trial, leveraging its Eutelsat OneWeb’s LEO satellite constellation and executing the test in line with 3GPP Release 17 standards.
- In February 2025, Ericsson, in collaboration with Grupo Oesía and Universidad Carlos III de Madrid (UC3M), demonstrated the integration of 5G technologies and Non-Terrestrial Networks (NTN) using Eutelsat OneWeb’s LEO constellation for satellite backhaul.
Report Coverage
The research report offers an in-depth analysis based on Satellite Type, Frequency Band, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Expansion of low-earth orbit (LEO) satellite constellations will enhance global 5G coverage.
- Integration with terrestrial 5G networks will reduce latency and improve service reliability.
- Increasing demand for enterprise broadband and IoT applications will drive market growth.
- Advancements in satellite payload and antenna technologies will boost network capacity.
- Strategic partnerships and joint ventures will accelerate infrastructure deployment worldwide.
- Focus on energy-efficient satellite systems will reduce operational costs and environmental impact.
- Enhanced spectrum management and frequency allocation will optimize network performance.
- Growth in remote and underserved regions will expand market adoption.
- Continuous innovation in signal processing and network orchestration will improve quality of service.
- Regulatory support and international collaborations will facilitate large-scale satellite-based 5G rollouts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Satellite Based 5G Network Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite Based 5G Network Market projected to grow between 2025 and 2032?
Which Satellite Based 5G Network Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Satellite Based 5G Network Market?
Who are the leading companies in the Satellite Based 5G Network Market?
Which region commanded the largest share of the Satellite Based 5G Network Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Satellite Based 5G Network Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Satellite Based 5G Network Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5.7 billion → 2032: USD 19.43 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Satellite Based 5G Network Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Satellite Based 5G Network Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Satellite Based 5G Network Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Satellite Based 5G Network Market Drivers
- 3.3 Satellite Based 5G Network Market Restraints & Challenges
- 3.4 Satellite Based 5G Network Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Satellite Based 5G Network Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Satellite Based 5G Network Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Satellite Based 5G Network category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Satellite Based 5G Network Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Satellite Based 5G Network Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Satellite Based 5G Network market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Satellite Based 5G Network Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Satellite Based 5G Network Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Satellite Based 5G Network Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Satellite Based 5G Network (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Satellite Based 5G Network Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Satellite Based 5G Network Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Satellite Based 5G Network Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Satellite Based 5G Network Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Satellite Based 5G Network Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Satellite Based 5G Network Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Satellite Based 5G Network Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Satellite Based 5G Network Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Satellite Based 5G Network Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
