
Cardiac Safety Service Market Overview:
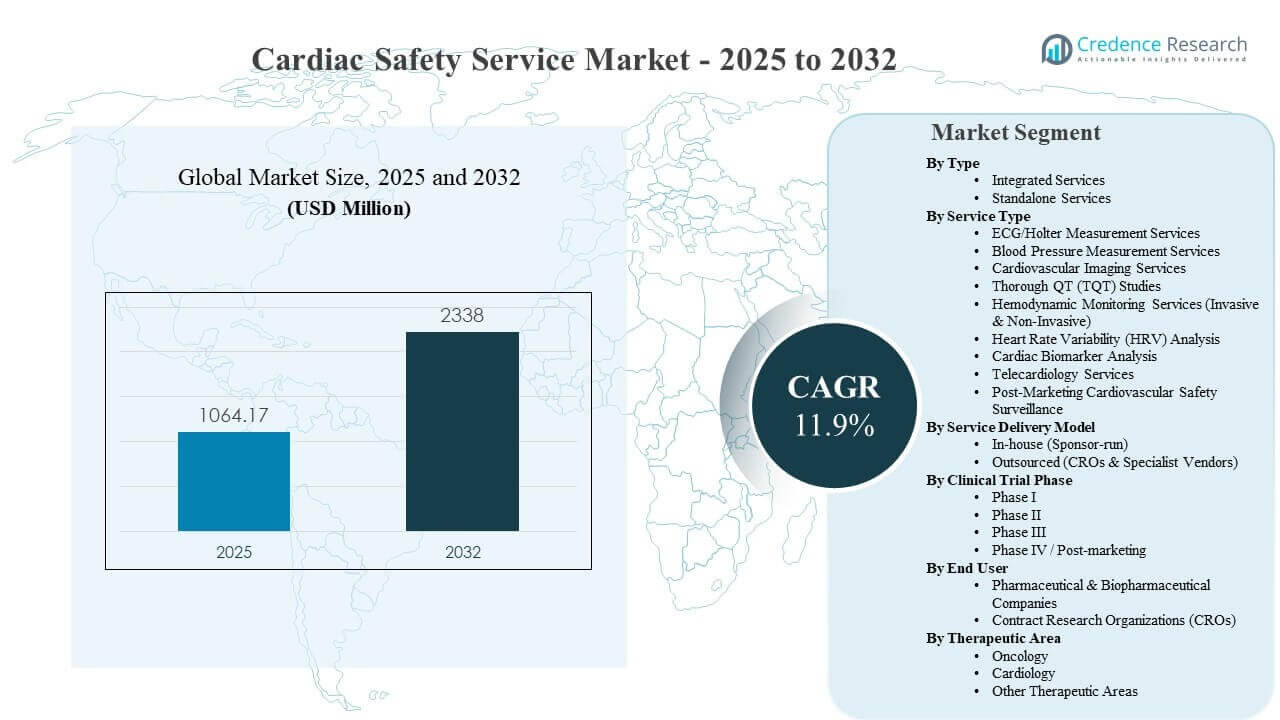
The global Cardiac Safety Service Market size was estimated at USD 1,064.17 million in 2025 and is expected to reach USD 2,338 million by 2032, growing at a CAGR of 11.9% from 2025 to 2032. Cardiac Safety Service Market growth is primarily driven by rising regulatory scrutiny on cardiac risk, which is increasing the frequency and depth of ECG/QT, biomarker, and hemodynamic monitoring across drug development programs. North America and Europe remain central demand hubs due to strong sponsor concentration and mature clinical research infrastructure, supported by rapid outsourcing of specialized cardiac safety workflows.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cardiac Safety Service Market Size 2025 | USD 1,064.17 million |
| Cardiac Safety Service Market, CAGR | 11.9% |
| Cardiac Safety Service Market Size 2032 | USD 2,338 million |
Key Market Trends & Insights
- The Cardiac Safety Service Market is projected to expand at 11.9% CAGR (2025–2032), reaching USD 2,338 million by 2032 from USD 1,064.17 million in 2025.
- Phase III accounted for the largest clinical trial phase share of 32.4% in 2025, reflecting higher monitoring intensity in pivotal programs.
- Pharmaceutical & Biopharmaceutical Companies represented 42.6% in 2025, supported by high trial volumes and regulated safety evidence requirements.
- ECG/Holter Measurement Services held 27.8% in 2025, supported by scalable deployment across multi-site trials and standardized QT/rhythm assessment.
- North America represented 36.2% in 2025, supported by high sponsor density and broad adoption of specialized cardiac safety service providers.
Segment Analysis
Cardiac Safety Service Market demand is shaped by clinical trial complexity, protocol requirements for QT/QTc risk evaluation, and expansion of decentralized monitoring workflows. Cardiac safety assessments increasingly rely on standardized acquisition, centralized review, and harmonized reporting to reduce variability across multi-country studies. Cardiac Safety Service Market adoption is also supported by higher use of continuous monitoring approaches that improve detection of intermittent arrhythmias and subtle safety signals.
Cardiac Safety Service Market purchasing behavior increasingly favors operational reliability, audit-ready data handling, and faster turnaround times for safety decision-making. Sponsors and CROs commonly prioritize vendors that can integrate multiple modalities, including ECG, blood pressure, biomarkers, imaging, and hemodynamic monitoring, within consistent quality systems. Post-marketing cardiovascular safety surveillance continues to gain importance as real-world monitoring volumes rise and safety signal management becomes more continuous.
By Type Insights
Standalone Services are gaining momentum as sponsors seek modular cardiac safety capabilities aligned to specific protocol endpoints and budget constraints. Standalone Services adoption is supported by trial designs that use multiple specialist vendors across endpoints and geographies. Integrated Services remain relevant for programs that require coordinated delivery across multiple cardiac modalities and standardized reporting formats. Cardiac Safety Service Market procurement decisions for type selection are strongly influenced by internal capabilities, trial scale, and the need for vendor interoperability.
By Service Type Insights
ECG/Holter Measurement Services accounted for the largest share of 27.8% in 2025 due to broad applicability across phases and therapeutic areas where rhythm and QT/QTc monitoring is required. ECG/Holter Measurement Services are widely adopted because non-invasive workflows support high patient throughput and repeat assessments without major operational burden. Growth in continuous monitoring and remote acquisition strengthens demand for telemetry-enabled pathways and centralized review. Cardiac Safety Service Market service mix is also supported by rising use of biomarkers, imaging, and hemodynamic monitoring in higher-risk programs.
By Service Delivery Model Insights
Outsourced (CROs & Specialist Vendors) demand is rising as sponsors prioritize scalability, standardization, and access to specialized cardiac safety expertise. Outsourced delivery improves consistency across sites by using validated processes for acquisition, adjudication, and reporting. Outsourced workflows also support faster study execution by reducing sponsor operational load and improving access to global networks. In-house (Sponsor-run) models remain relevant for organizations with mature internal platforms and strong centralized monitoring teams.
By Clinical Trial Phase Insights
Phase III accounted for the largest share of 32.4% in 2025 because pivotal trials require extensive characterization of cardiac risk across broader populations and longer durations. Phase III protocols typically increase monitoring frequency and expand the scope of endpoints, strengthening demand for centralized review and consistent data handling. Earlier-phase programs are increasingly emphasizing structured monitoring to detect signals sooner and support benefit-risk decisions before pivotal investment. Cardiac Safety Service Market phase demand is reinforced by the need to generate submission-ready safety evidence.
By End User Insights
Pharmaceutical & Biopharmaceutical Companies accounted for the largest share of 42.6% in 2025 due to high pipeline activity and regulated cardiac safety assessment requirements. Pharmaceutical & Biopharmaceutical Companies commonly embed cardiac monitoring into trial governance and risk management planning, supporting recurring demand. Contract Research Organizations (CROs) are expanding delivery as outsourcing increases and sponsors seek integrated operational execution. Cardiac Safety Service Market end-user growth is also supported by broader adoption of technology-enabled monitoring and centralized analytics.
By Therapeutic Area Insights
Oncology accounted for the largest share of 25.9% in 2025 due to frequent cardiovascular risk monitoring needs associated with multiple oncology modalities. Oncology programs often require sustained ECG and biomarker monitoring to manage QT prolongation, arrhythmias, and therapy-associated cardiac impacts. Cardiology programs continue to expand demand as monitoring becomes more continuous and remote-friendly across chronic disease management pathways. Cardiac Safety Service Market therapeutic growth is reinforced by expansion of telecardiology services and multi-modality safety surveillance.
Cardiac Safety Service Market Drivers
Increasing regulatory focus on cardiac risk assessment in drug development
Cardiac Safety Service Market expansion is supported by heightened regulatory expectations for cardiac monitoring and risk mitigation during clinical development. Sponsors increasingly incorporate structured ECG/QT monitoring, biomarker testing, and hemodynamic assessments to support safer protocol execution. Cardiac Safety Service Market workflows also strengthen compliance by improving audit readiness and traceability across multi-site trials. Standardized processes for acquisition and centralized review reduce variability and strengthen confidence in safety endpoints.
- For instance, Medpace states that its Phase I unit uses a 12-lead telemetry system that provides continuous high-resolution ECG data capable of detecting a 1 ms change, while a 10 ms shift from baseline is treated as the threshold for regulatory concern.
Expansion of outsourced clinical research and specialized service ecosystems
Cardiac Safety Service Market growth is reinforced by outsourcing trends as sponsors prioritize speed and operational efficiency. CROs and specialist vendors provide scalable capacity, standardized systems, and dedicated expertise across ECG analysis, imaging review, and safety surveillance. Cardiac Safety Service Market outsourcing also supports consistent delivery across regions where site capability levels vary. Technology-enabled platforms further strengthen outsourced delivery by accelerating data flow and improving quality control.
Rising complexity of trial designs and increased monitoring intensity
Cardiac Safety Service Market demand benefits from more complex protocols, broader inclusion criteria, and higher monitoring intensity in pivotal studies. Larger trials increase data volume and require robust workflows for signal detection and clinical adjudication. Cardiac Safety Service Market services help streamline monitoring by integrating multi-modality data capture and centralized reporting. Program teams increasingly rely on these services to reduce cycle time and improve the reliability of safety decisions.
Growth in remote monitoring and technology-enabled evidence generation
Cardiac Safety Service Market momentum is supported by wider adoption of remote monitoring tools and digital workflows. Continuous ECG telemetry, cloud-based acquisition, and centralized analytics improve coverage and enable faster detection of intermittent events. Cardiac Safety Service Market platforms also improve patient convenience and site efficiency by reducing on-site burden for repeat assessments. Technology-enabled delivery supports broader scalability and strengthens post-marketing surveillance workflows.
- For instance, AliveCor reported that in a UK trial involving 243 patients across 10 hospitals, KardiaMobile-enabled follow-up helped clinicians diagnose 56% of patients in an average of 9.5 days, compared with 10% diagnosed in 43 days under standard care. Cardiac Safety Service Market platforms also improve patient convenience and site efficiency by reducing on-site burden for repeat assessments.
Cardiac Safety Service Market Challenges
Cardiac Safety Service Market delivery faces operational challenges tied to multi-site variability, device heterogeneity, and differences in site capability across countries. Data harmonization can be difficult when acquisition methods differ across sites or when multiple vendors support overlapping endpoints. Cardiac Safety Service Market programs also require strict adherence to quality systems to maintain audit readiness and submission-grade data integrity. Short timelines and protocol amendments can increase rework, raising operational burden for sponsors and vendors.
Cardiac Safety Service Market growth is also constrained by budget pressure and procurement complexity in studies using multiple specialist vendors. Vendor interoperability and integration into sponsor or CRO systems can extend study setup timelines. Cardiac Safety Service Market providers must maintain strong cybersecurity and privacy controls as remote monitoring expands and data flows become more continuous. Talent availability in specialized ECG interpretation, clinical adjudication, and advanced analytics can create capacity bottlenecks.
- For instance, IQVIA reports that it has delivered a 30-minute ECG review turnaround since 2012 for a cardiac safety monitoring program, while Clario reports completion of a SOC 2 Type II audit covering January 1, 2023 through December 31, 2023 and announced ISO 27001:2022 certification in February 2024, showing how rapid specialist review capacity and formally audited security controls are becoming critical operational differentiators.
Cardiac Safety Service Market Trends and Opportunities
Cardiac Safety Service Market trends increasingly favor modular service models that allow sponsors to select specific modalities, analytics, and reporting components aligned to protocol needs. Centralized review and standardized reporting are becoming more widely adopted to improve cross-site consistency and accelerate safety decisions. Cardiac Safety Service Market providers are expanding technology-enabled workflows that support continuous monitoring, remote acquisition, and scalable data processing. Growth opportunities strengthen in programs that require multi-modality monitoring and integrated endpoint strategies.
- For instance, Clario states that its SafePatient ECG model has been used across more than 11,500 cardiac safety studies and 580+ cardiac safety-related drug approvals, offers expedited ECG analysis within four hours from collection, and is complemented by an AI-powered ECG Quality Score trained on over 80,000 Phase 1 healthy-volunteer ECGs to support near-real-time quality remediation.
Cardiac Safety Service Market opportunities are rising in post-marketing cardiovascular safety surveillance as monitoring volumes increase and safety signal management becomes more continuous. Telecardiology services and remote device ecosystems support wider real-world monitoring adoption across broader populations. Cardiac Safety Service Market vendors that combine operational execution with analytics capabilities can differentiate through faster signal detection and improved decision support. Expansion in emerging regions is supported by growth in clinical trial activity and increasing outsourcing penetration.
Regional Insights
North America
North America accounted for 36.2% in 2025, supported by strong sponsor concentration, mature clinical research infrastructure, and broad adoption of specialized cardiac safety workflows. Cardiac Safety Service Market demand in North America is strengthened by consistent use of ECG/QT monitoring across regulated programs and by wide availability of endpoint technology platforms. Outsourcing levels remain high as sponsors seek validated processes and scalable capacity. Remote monitoring adoption continues to expand, supporting continuous data capture and faster safety decision-making.
Europe
Europe accounted for 28.4% in 2025, supported by established CRO ecosystems, strong clinical trial execution capacity, and broad adoption of centralized monitoring approaches. Cardiac Safety Service Market demand in Europe is reinforced by multi-country trial activity that benefits from standardized acquisition and review workflows. Service providers increasingly support multi-modality programs that combine ECG, biomarkers, imaging, and hemodynamic monitoring. Vendor selection in Europe commonly emphasizes quality systems, interoperability, and consistent reporting across sites.
Asia Pacific
Asia Pacific accounted for 24.1% in 2025, supported by rising clinical trial volumes, strong recruitment capabilities, and growing outsourcing penetration. Cardiac Safety Service Market expansion in Asia Pacific is strengthened by sponsor focus on cost-effective execution and scalable monitoring capacity. Centralized review and cloud-enabled acquisition models support consistency across diverse site networks. Demand is increasing for telecardiology and remote-friendly workflows that reduce operational friction and support broader geographic coverage.
Latin America
Latin America accounted for 6.9% in 2025, supported by participation in global clinical trials and growing CRO activity. Cardiac Safety Service Market adoption is shaped by the need to ensure consistent quality across sites with varied infrastructure levels. Service providers commonly support standardized acquisition and centralized analysis to improve data integrity and comparability. Growth opportunities increase as regional trial activity expands and sponsors adopt more consistent safety monitoring standards.
Middle East & Africa
Middle East & Africa accounted for 4.4% in 2025, supported by expanding clinical research networks in select countries and increasing interest in outsourced trial services. Cardiac Safety Service Market delivery in the region often prioritizes vendor support for consistent training, standardized workflows, and centralized review. Infrastructure variability and limited specialist footprints can constrain adoption for complex modalities. Growth is supported by gradual maturation of clinical trial ecosystems and increasing cross-border study participation.
Competitive Landscape
Cardiac Safety Service Market competition is characterized by a mix of global CROs, endpoint technology providers, and specialist vendors offering ECG analysis, imaging review, biomarker support, and safety surveillance. Competitive differentiation commonly centers on validated quality systems, global operational scale, interoperability with sponsor ecosystems, and technology-enabled acquisition and centralized analytics. Cardiac Safety Service Market providers also compete through turnaround time, data integrity performance, and the ability to support complex, multi-modality programs across regions.
Laboratory Corporation of America (Labcorp) is positioned to support cardiac safety needs through broad clinical service capabilities and integrated clinical trial support infrastructure. Laboratory Corporation of America (Labcorp) can support sponsor requirements for reliable testing access and coordinated operational execution in multi-site programs. Cardiac Safety Service Market partnerships that expand access and streamline service delivery can strengthen operational scale and reinforce sponsor confidence. Laboratory Corporation of America (Labcorp) strategy aligns with demand for dependable, compliant, and scalable evidence-generation support.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Laboratory Corporation of America (Labcorp)
- Medpace Holdings, Inc.
- IQVIA
- PPD, Inc. (Thermo Fisher Scientific)
- Clario
- Certara, Inc.
- Celerion, Inc.
- Koninklijke Philips N.V. (BioTelemetry)
- Ncardia AG
- Banook Group Limited
- Biotrial S.A.
- Charles River Laboratories
- ICON plc
- WuXi AppTec
- Eurofins Scientific
- Richmond Pharmacology Limited
- SGS S.A.
- PhysioStim
- NEXEL Co., Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In April 2025, Clario announced a multi-year agreement with Amazon Web Services (AWS) to advance its generative AI platform for clinical trials. The collaboration is aimed at processing complex clinical documents and trial data faster and more accurately, and AWS specifically noted support for endpoint data analysis across imaging, cardiac safety, eCOA, and respiratory assessments, making it relevant to the cardiac safety service market.
- In April 2025, Philips and Myocardial Solutions teamed up to advance AI-enabled cardiac MR imaging. Their collaboration focuses on bringing technologies such as Fast-SENC and MyoStrain into cardiac care to help detect early signs of cardiotoxicity and measure subtle heart-function changes quickly, which supports broader cardiac monitoring and safety assessment needs in the market.
- In January 2025, ActiGraph announced the acquisition of the Biofourmis Life Science business to expand its clinical trial technology offering. According to the announcement, the deal strengthens ActiGraph’s device-agnostic digital health platform by adding support for medical-grade devices including ECG, alongside pulse oximetry, spirometry, and blood pressure monitoring, which is relevant for cardiac safety-related clinical research services.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1,064.17 million |
| Revenue forecast in 2032 | USD 2,338 million |
| Growth rate (CAGR) | 11.9% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Type Outlook: Integrated Services, Standalone Services; By Service Type Outlook: ECG/Holter Measurement Services, Blood Pressure Measurement Services, Cardiovascular Imaging Services, Thorough QT (TQT) Studies, Hemodynamic Monitoring Services (Invasive & Non-Invasive), Heart Rate Variability (HRV) Analysis, Cardiac Biomarker Analysis, Telecardiology Services, Post-Marketing Cardiovascular Safety Surveillance; By Service Delivery Model Outlook: In-house (Sponsor-run), Outsourced (CROs & Specialist Vendors); By Clinical Trial Phase Outlook: Phase I, Phase II, Phase III, Phase IV / Post-marketing; By End User Outlook: Pharmaceutical & Biopharmaceutical Companies, Contract Research Organizations (CROs); By Therapeutic Area Outlook: Oncology, Cardiology, Other Therapeutic Areas |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Laboratory Corporation of America (Labcorp); Medpace Holdings, Inc.; IQVIA; PPD, Inc. (Thermo Fisher Scientific); Clario; Certara, Inc.; Celerion, Inc.; Koninklijke Philips N.V. (BioTelemetry); Ncardia AG; Banook Group Limited; Biotrial S.A.; Charles River Laboratories; ICON plc; WuXi AppTec; Eurofins Scientific; Richmond Pharmacology Limited; SGS S.A.; PhysioStim; NEXEL Co., Ltd. |
| No. of Pages | 345 |
Segmentation
By Type
- Integrated Services
- Standalone Services
By Service Type
- ECG/Holter Measurement Services
- Blood Pressure Measurement Services
- Cardiovascular Imaging Services
- Thorough QT (TQT) Studies
- Hemodynamic Monitoring Services (Invasive & Non-Invasive)
- Heart Rate Variability (HRV) Analysis
- Cardiac Biomarker Analysis
- Telecardiology Services
- Post-Marketing Cardiovascular Safety Surveillance
By Service Delivery Model
- In-house (Sponsor-run)
- Outsourced (CROs & Specialist Vendors)
By Clinical Trial Phase
- Phase I
- Phase II
- Phase III
- Phase IV / Post-marketing
By End User
- Pharmaceutical & Biopharmaceutical Companies
- Contract Research Organizations (CROs)
By Therapeutic Area
- Oncology
- Cardiology
- Other Therapeutic Areas
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the Cardiac Safety Service Market size in 2025 and the forecast for 2032?
What is the CAGR for the Cardiac Safety Service Market during 2025–2032?
Which segment is the largest within service type in 2025?
What factors are driving growth in the Cardiac Safety Service Market?
Which companies are leading participants in the Cardiac Safety Service Market?
Which region leads the Cardiac Safety Service Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1,064.17 million → 2032: USD 2,338 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiac Safety Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiac Safety Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Cardiac Safety Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Cardiac Safety Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiac Safety Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiac Safety Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiac Safety Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiac Safety Service Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1,064.17 million → 2032: USD 2,338 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiac Safety Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiac Safety Service Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cardiac Safety Service Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2025-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cardiac Safety Service Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

