
Oral Syringes Market Overview:
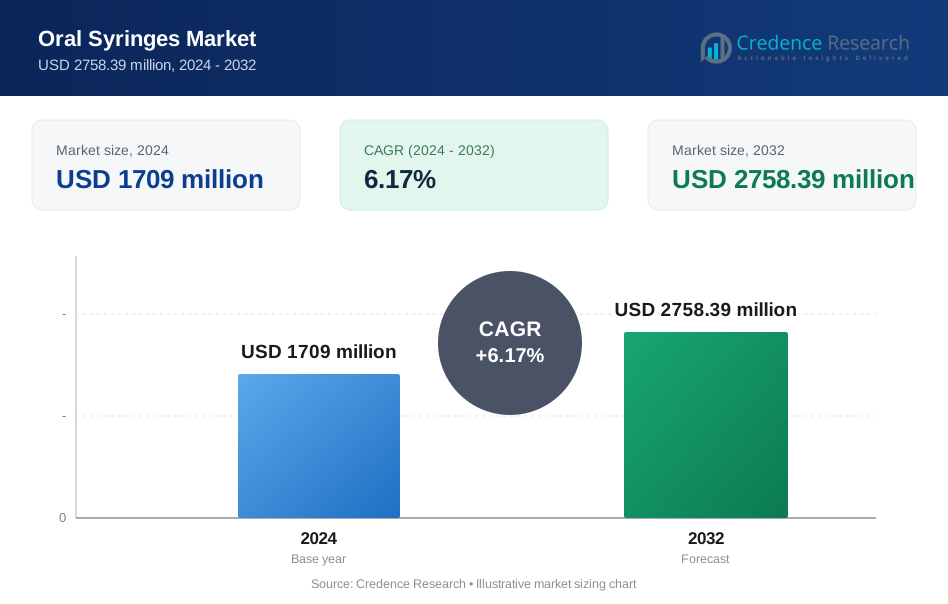
The oral syringes market was valued at USD 1709 million in 2024 and is projected to reach USD 2758.39 million by 2032, growing at a CAGR of 6.17% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Oral Syringes Market Size 2024 | USD 1709 million |
| Oral Syringes Market, CAGR | 6.17% |
| Oral Syringes Market Size 2032 | USD 2758.39 million |
Oral Syringes Market Insights
- Market growth is driven by demand for accurate oral dosing and infection control, with disposable oral syringes leading the product type segment at a market share of 63.4%.
- Key trends include expansion of home healthcare and improved syringe design, while polypropylene dominates materials with a market share of 46.7% due to durability and clarity.
- Competitive activity centers on safety, scale, and distribution strength, while environmental concerns and price sensitivity act as key restraints in cost-focused regions.
- North America leads with a market share of 36.2%, followed by Europe at 28.7% and Asia Pacific at 24.1%, supported by healthcare access, safety standards, and demographic demand.

Oral Syringes Market Segmentation Analysis:
By Product Type
By product type, disposable oral syringes dominate the oral syringes market with a market share of 63.4%. Healthcare providers prefer disposable options to reduce cross-contamination risk and improve patient safety. Single-use syringes support infection control protocols in hospitals and clinics. Rising medication administration in pediatric and geriatric care increases demand. Cost efficiency and ease of disposal further support adoption. Reusable oral syringes remain relevant in controlled home settings but face sterilization concerns. Disposable oral syringes maintain leadership due to regulatory focus on hygiene, high patient turnover, and growing emphasis on safe drug delivery practices.
- For instance, BD manufactures disposable oral syringes designed for the accurate measurement and administration of non-injectable liquid medications. These syringes are validated for quality and accuracy to ensure reliable dosing and prevent leakage when used according to their intended single-use labeling.
By Material
By material, polypropylene holds the largest share at 46.7% of the oral syringes market. Manufacturers favor polypropylene for durability, chemical resistance, and clarity. The material supports accurate dosage markings and smooth plunger movement. Polypropylene syringes suit liquid medications and repeated handling. Polyethylene follows due to flexibility and lower cost, while silicone remains niche for premium applications. Regulatory acceptance and compatibility with pharmaceutical formulations strengthen polypropylene usage. This material remains dominant due to consistent performance, manufacturing efficiency, and wide acceptance across healthcare and pharmaceutical applications.
- For instance, B. Braun Melsungen AG produces polypropylene oral syringes that meet ISO 7886 requirements and withstand autoclave exposure up to 121 °C in validation tests.
By End User
By end user, hospitals and clinics account for a market share of 52.8%, leading oral syringe consumption. High patient volumes and frequent oral medication administration drive demand. Hospitals rely on oral syringes for accurate dosing, especially in pediatrics. Infection prevention standards favor single-use products. Home healthcare follows due to chronic care and aging populations. Pharmaceutical companies use oral syringes for packaging and clinical trials. Hospitals and clinics retain dominance due to continuous usage cycles, safety protocols, and standardized medication administration practices.
Key Growth Drivers
Rising Demand for Accurate Oral Drug Administration
Healthcare systems increasingly prioritize precise dosing for liquid medications to reduce treatment errors. Oral syringes enable accurate measurement compared with cups or spoons, improving medication safety. Pediatric and geriatric patients benefit the most from controlled dosing. Hospitals rely on oral syringes for antibiotics, pain relief, and nutritional supplements. Regulatory guidelines promote safe oral drug delivery practices. Growing use of liquid formulations further supports demand. Clinicians and caregivers prefer oral syringes for consistency and ease of use. This driver continues to support steady adoption across hospitals, clinics, and outpatient care settings worldwide.
- For instance, Terumo Corporation designed oral syringes with precise graduation intervals and validated consistent plunger movement during internal performance tests to ensure accurate medication delivery.
Expansion of Pediatric and Geriatric Care Services
Global demographic trends strongly influence oral syringe demand. Pediatric care requires precise dosing due to low tolerance for dosage errors. Geriatric patients often use liquid medicines because of swallowing difficulties. Hospitals use oral syringes in neonatal, pediatric, and elderly wards. Home caregivers rely on oral syringes for daily medication routines. Rising life expectancy increases chronic disease prevalence among older adults. Pediatric population growth in developing regions also contributes. This driver expands usage across institutional and home healthcare environments. Demographic shifts ensure long-term demand growth for oral syringes.
- For instance, Baxter International supplies specialized enteral syringes and infusion systems designed for use in neonatal and geriatric care settings, ensuring precise medication delivery and compatibility with safety-focused connectors to prevent misconnections.
Increased Focus on Infection Control and Patient Safety
Infection prevention remains a top priority in healthcare settings. Disposable oral syringes reduce cross-contamination risks compared with reusable devices. Hospitals adopt single-use syringes to comply with hygiene standards. Regulatory authorities promote safer medication administration tools. Growing awareness of hospital-acquired infections supports disposable product adoption. Patient safety programs emphasize error reduction and cleanliness. This driver strengthens demand across hospitals and clinics. Focus on infection control continues to influence procurement policies and supports sustained market growth.
Key Trends & Opportunities
Growth of Home Healthcare and Self-Administration
Home healthcare services expand due to aging populations and chronic disease management. Patients increasingly administer medications at home. Oral syringes support safe and accurate self-administration. Caregivers value clear markings and ease of handling. Home treatment reduces hospital visits and healthcare costs. This trend creates opportunities for consumer-focused designs. Manufacturers target home users with simple, ergonomic products. Expansion of home healthcare broadens the oral syringes market beyond institutional buyers.
- For instance, Medline Industries supplies oral syringes for home use featuring easy-to-read graduations and clear labeling to distinguish them from other medical devices. These syringes are designed with low-dose reservoirs and specific tip styles to assist with the accurate measurement and delivery of liquid medication.
Product Innovation in Materials and Design
Manufacturers focus on improving syringe usability and safety. Innovations include smoother plungers, clearer graduations, and better grip designs. Child-resistant features attract pediatric care providers. Material advancements improve durability and chemical compatibility. Silicone and advanced polymers gain attention for premium products. Design innovation helps brands differentiate in competitive markets. This trend supports value-added offerings and strengthens product portfolios. Continuous innovation creates opportunities for premium pricing and wider adoption.
- For instance, Nipro Corporation developed oral syringes featuring low-friction plungers and specialized gaskets designed to maintain seal integrity and dimensional stability during use.
Key Challenges
Environmental Concerns Related to Disposable Products
Widespread use of disposable oral syringes increases medical plastic waste. Environmental regulations pressure healthcare providers to reduce waste. Sustainable alternatives remain limited and costly. Disposal and recycling challenges affect hospital operations. Environmental concerns influence procurement decisions in some regions. Manufacturers face pressure to develop eco-friendly materials. This challenge may limit long-term growth of disposable products. Balancing safety and sustainability remains a key industry issue.
Price Sensitivity in Developing Regions
Cost remains a major concern in low- and middle-income countries. Healthcare budgets often prioritize essential medicines over devices. Reusable oral syringes compete due to lower upfront costs. Price sensitivity affects large-scale procurement decisions. Limited reimbursement restricts adoption of premium products. Manufacturers must balance affordability and quality. This challenge slows market penetration in cost-sensitive regions and impacts overall growth pace.
Regional Analysis
North America
North America holds a market share of 36.2% in the oral syringes market, driven by strong healthcare infrastructure and strict patient safety standards. Hospitals and clinics widely use oral syringes for pediatric and geriatric medication delivery. High awareness of dosing accuracy supports steady demand. Regulatory focus on infection control increases preference for disposable oral syringes. Home healthcare adoption also supports market growth. The United States leads regional demand due to high healthcare spending and advanced clinical practices, while Canada contributes through expanding elderly care services and rising use of home-based medication administration devices.
Europe
Europe accounts for a market share of 28.7%, supported by well-established healthcare systems and strong regulatory oversight. Countries such as Germany, France, and the United Kingdom drive demand for accurate oral drug delivery devices. Hospitals emphasize patient safety and hygiene, supporting disposable syringe adoption. Aging populations increase medication usage across long-term care facilities. Home healthcare services continue to expand. Environmental considerations influence material selection and waste management. Europe benefits from standardized healthcare protocols, steady pharmaceutical activity, and consistent demand for safe and precise oral medication administration solutions.
Asia Pacific
Asia Pacific holds a market share of 24.1%, reflecting rising healthcare access and growing population base. Increasing pediatric care needs and expanding elderly populations drive demand for oral syringes. Governments invest in healthcare infrastructure and maternal care programs. Hospitals and clinics adopt oral syringes to improve medication accuracy. Home healthcare usage grows in urban areas. Countries such as China, India, and Japan lead regional growth. Cost-effective products gain traction. Asia Pacific shows strong growth potential due to expanding healthcare services and rising awareness of safe medication delivery.
Rest of the World
The Rest of the World region accounts for a market share of 11.0%, supported by gradual healthcare development. Latin America shows growing demand due to improving hospital infrastructure and pediatric care services. The Middle East benefits from healthcare modernization and hospital expansion. Africa remains at an early adoption stage with limited access in rural areas. International aid programs support medication safety initiatives. Demand focuses on affordable and disposable oral syringes. Although smaller in scale, the region offers long-term growth opportunities driven by improving healthcare access and medication safety awareness.
Oral Syringes Market Segmentations:
By Product Type
- Disposable oral syringes
- Reusable oral syringes
By Material
- Polypropylene
- Polyethylene
- Silicone
By End User
- Hospitals and clinics
- Home healthcare
- Pharmaceutical companies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights competition led by BD (Becton, Dickinson and Company), B. Braun Melsungen AG, Terumo Corporation, Cardinal Health, and Medline Industries. These companies compete on product quality, safety compliance, and large-scale manufacturing capability. Market leaders focus on disposable oral syringes to meet infection control standards and regulatory expectations. Strong hospital and pharmaceutical distribution networks provide competitive advantage. Manufacturers invest in material innovation, clear dosage markings, and ergonomic designs to improve usability. Pricing efficiency remains critical in public healthcare procurement. Regional players compete through cost-effective offerings and local supply contracts. Partnerships with hospitals and pharmaceutical firms support stable demand. Overall competition remains moderately consolidated, driven by patient safety focus, regulatory compliance, and growing demand for accurate oral medication delivery devices.
Key Player Analysis
- BD (Becton, Dickinson and Company)
- Braun Melsungen AG
- Terumo Corporation
- Cardinal Health
- Smiths Medical
- Nipro Corporation
- Medline Industries
- Hindustan Syringes & Medical Devices
- Baxter International
- Fresenius Kabi
Recent Developments
- In July 2025, Terumo Corporation announced a commercial launch for an injection delivery system. The update reflects ongoing syringe-based delivery innovation.
- In January 2025, BD (Becton, Dickinson and Company) announced new U.S. investments to add capacity for critical devices, including syringes.
- In February 2024, Cardinal Health announced a voluntary recall expansion for Monoject sterile syringes, including ENFit enteral syringes.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Oral Syringes market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Oral Syringes market projected to grow between 2024 and 2032?
Which Oral Syringes market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Oral Syringes market?
Who are the leading companies in the Oral Syringes market?
Which region commanded the largest share of the Oral Syringes market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Oral Syringes Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Oral Syringes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1709 million → 2032: USD 2758.39 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Oral Syringes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Oral Syringes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Oral Syringes Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Oral Syringes Market Drivers
- 3.3 Oral Syringes Market Restraints & Challenges
- 3.4 Oral Syringes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Oral Syringes Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Oral Syringes Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Oral Syringes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Oral Syringes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Oral Syringes Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Oral Syringes. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Oral Syringes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Oral Syringes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Oral Syringes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Oral Syringes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Oral Syringes
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Oral Syringes Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Oral Syringes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Oral Syringes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Oral Syringes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Oral Syringes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Oral Syringes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Oral Syringes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Oral Syringes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
