
Cardiac Sutures Market Overview:
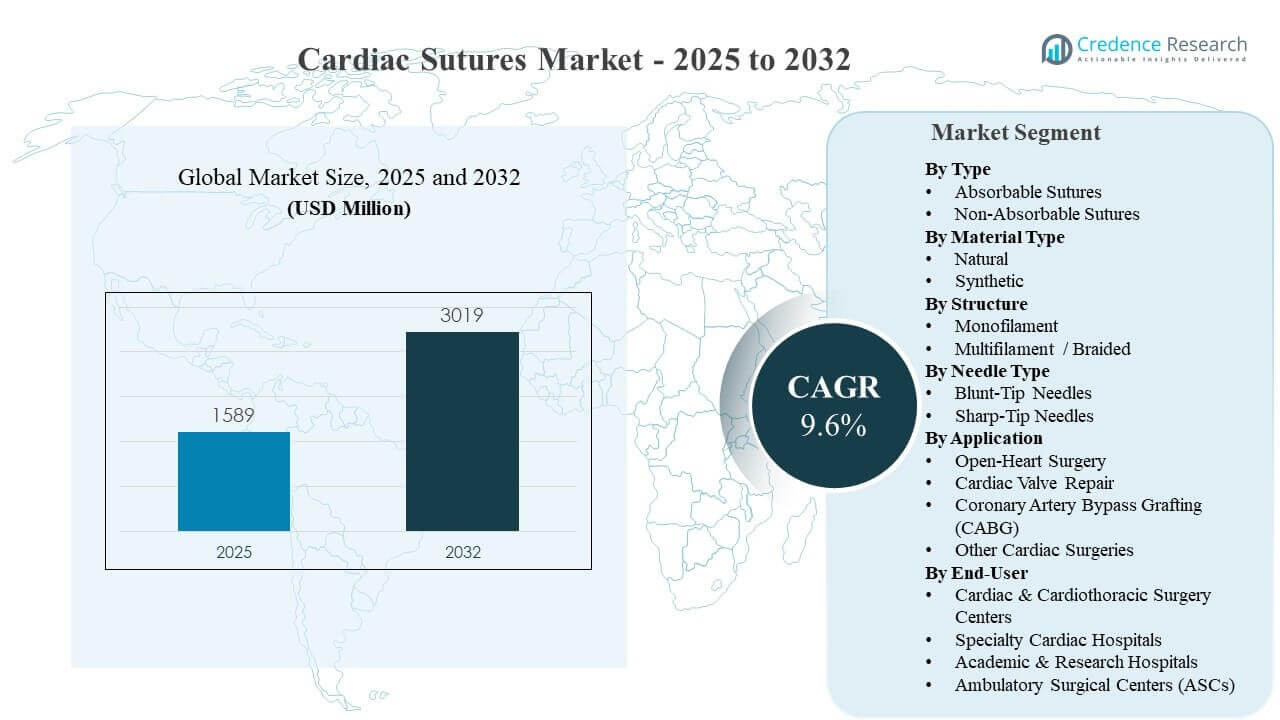
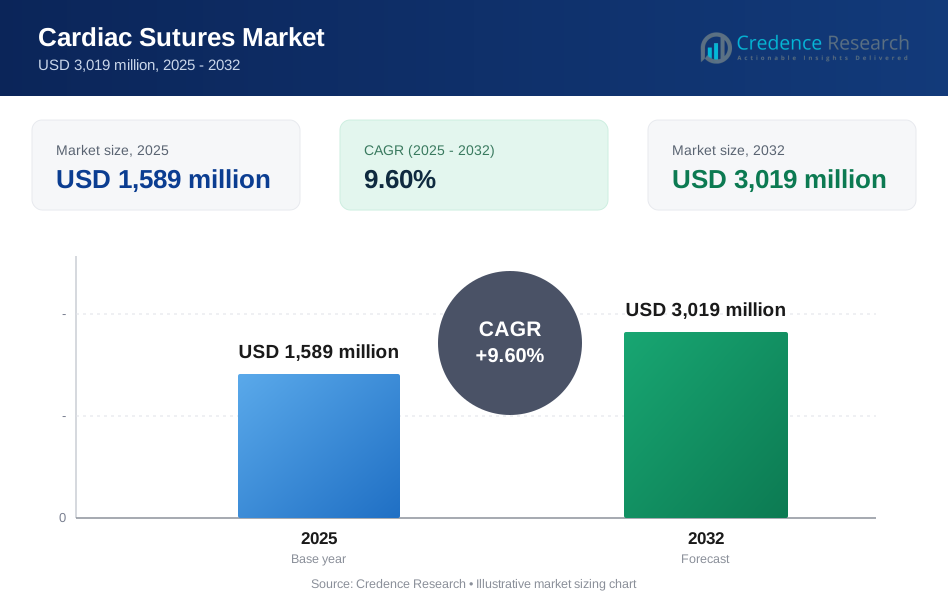
The global Cardiac Sutures Market size was estimated at USD 1,589 million in 2025 and is expected to reach USD 3,019 million by 2032, growing at a CAGR of 9.6% from 2025 to 2032. Growth is primarily supported by rising volumes of coronary artery bypass grafting and cardiac valve repair procedures that require high-reliability closure in delicate tissue planes. Cardiac Sutures Market demand is also reinforced by expanding cardiac surgery capacity in emerging economies and the continued shift toward premium materials and needle–suture combinations designed for precision handling.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cardiac Sutures Market Size 2025 | USD 1,589 million |
| Cardiac Sutures Market , CAGR | 9.6% |
| Cardiac Sutures Market Size 2032 | USD 3,019 million |
Key Market Trends & Insights
- North America accounted for 46.2% of Cardiac Sutures Market revenue in 2025, reflecting higher procedure intensity and premium product mix.
- Absorbable Sutures captured 62.9% share in 2025, supported by surgeon preference for predictable absorption and reduced follow-up burden.
- Coronary Artery Bypass Grafting (CABG) represented 33.1% share in 2025, sustaining demand for consistent tensile strength and knot security.
- Specialty Cardiac Hospitals accounted for 77.6% share in 2025, driven by high-acuity case concentration and standardized procurement pathways.
- Asia Pacific reached 21.1% share in 2025, supported by expanding cardiac surgery access and growing adoption of advanced suture materials.
Segment Analysis
Cardiac Sutures Market segmentation reflects clinical requirements across cardiac procedure types, closure complexity, and institutional purchasing patterns. Cardiac Sutures Market demand is closely linked to procedure volumes in CABG, valve repair, and open-heart surgery, where performance requirements emphasize controlled needle penetration, reliable knot strength, and low tissue trauma. Procurement decisions in Cardiac Sutures Market are influenced by surgeon familiarity, hospital standardization of procedure kits, and quality assurance requirements for high-risk cardiac patients.
Cardiac Sutures Market also shows differentiation through material selection and filament structure, with clinical teams balancing handling preferences against infection control and tissue response. Cardiac Sutures Market purchasing increasingly favors product consistency, sterility assurance, and compatibility with advanced surgical approaches, including minimally invasive and robotic-assisted cardiac procedures. Cardiac Sutures Market growth is further shaped by broader cardiac care expansion in specialty hospitals and cardiothoracic centers, which remain the primary consumption hubs.
By Type Insights
Absorbable Sutures accounted for the largest share of 62.9% in 2025. Absorbable Sutures leadership in Cardiac Sutures Market is supported by predictable resorption profiles that align with post-operative healing timelines in cardiac closures. Absorbable Sutures also reduce the clinical burden associated with removal and support streamlined post-surgical care pathways in high-acuity settings. Absorbable Sutures adoption benefits from continued product enhancements such as improved handling, reduced tissue drag, and advanced coating options designed for safer healing response.
By Material Type Insights
Synthetic materials are widely preferred in Cardiac Sutures Market due to consistent tensile properties, predictable handling, and sterilization compatibility required for cardiovascular applications. Synthetic material selection supports knot security and uniform performance in demanding procedures such as CABG and valve repair. Synthetic formats also enable engineered coatings and precision filament designs that improve passage through delicate tissue planes. Natural materials remain relevant in limited use-cases, but Cardiac Sutures Market adoption trends generally favor synthetics for reproducibility and procedural standardization.
By Structure Insights
Monofilament structures are commonly selected in Cardiac Sutures Market when lower tissue drag and reduced wicking risk are prioritized. Monofilament formats support smooth passage and consistent performance in fine vascular and cardiac tissue closures. Multifilament / Braided structures remain important where enhanced handling and knot security are required for specific steps within complex repairs. Cardiac Sutures Market purchasing often includes both structures as complementary options, with monofilament usage strengthened by minimally invasive technique adoption.
By Needle Type Insights
Needle Type selection in Cardiac Sutures Market is primarily driven by tissue type, access route, and procedural step requirements. Sharp-Tip Needles are typically used where controlled penetration is necessary in tougher tissue planes and vascular structures. Blunt-Tip Needles are selected when minimizing accidental tissue injury and needle-stick risk is prioritized, particularly in select soft tissue handling scenarios. Cardiac Sutures Market purchasing frequently standardizes needle–suture combinations by procedure set, supporting consistent operating room workflows.
By Application Insights
Coronary Artery Bypass Grafting (CABG) accounted for the largest share of 33.1% in 2025. CABG leadership in Cardiac Sutures Market is supported by high procedure volumes and repeated closure requirements across anastomosis and graft fixation steps. CABG demand emphasizes consistent tensile strength, reliable knot security, and precise needle performance in vascular closure. Cardiac Sutures Market consumption within CABG is further reinforced by procedural complexity in multi-vessel disease cases and ongoing burden of coronary artery disease in aging populations.
By End-User Insights
Specialty Cardiac Hospitals accounted for the largest share of 77.6% in 2025. Specialty Cardiac Hospitals dominance in Cardiac Sutures Market is supported by concentration of high-acuity surgical volumes and advanced cardiac teams performing CABG, valve repair, and open-heart interventions. Specialty Cardiac Hospitals typically maintain standardized purchasing contracts and procedure kits that increase recurring consumption of cardiac sutures. Academic & Research Hospitals contribute through complex casework and adoption of advanced closure formats, while Ambulatory Surgical Centers expand selectively as outpatient cardiac pathways mature.
Cardiac Sutures Market Drivers
Increasing cardiac surgery volumes across coronary and valve indications
Cardiac Sutures Market growth is driven by sustained volumes in CABG, valve repair, and open-heart procedures performed in high-acuity cardiac centers. Cardiac Sutures Market demand strengthens as aging populations increase the prevalence of coronary artery disease and degenerative valve conditions. Cardiac Sutures Market consumption rises with complex multi-step closures that require multiple suture strands and specialized needles. Cardiac Sutures Market purchasing also benefits from broader access to surgical cardiac care in emerging markets through expanded hospital capacity.
- For instance, Cleveland Clinic reported performing over 5,600 heart surgeries in 2023, underscoring the high-throughput surgical environments where cardiac sutures are consumed at scale.
Preference for advanced closure performance in delicate cardiovascular tissues
Cardiac Sutures Market demand increases as surgical teams prioritize reliable knot security, controlled handling, and low tissue trauma in cardiovascular closures. Cardiac Sutures Market adoption of engineered suture materials improves procedural confidence in vessel and valve-related repairs. Cardiac Sutures Market also benefits from product designs that reduce tissue drag and support smoother passage through fragile tissue planes. Cardiac Sutures Market procurement increasingly emphasizes consistency, sterility assurance, and predictable clinical performance in high-risk patients.
Hospital standardization and procedure-kit adoption in cardiac operating rooms
Cardiac Sutures Market expansion is supported by hospital procurement models that standardize suture sets by procedure and surgeon preference. Cardiac Sutures Market volumes increase when cardiac centers adopt bundled purchasing for operating room efficiency. Cardiac Sutures Market suppliers compete on breadth of compatible needle–suture combinations and portfolio coverage for CABG and valve workflows. Cardiac Sutures Market demand also increases as cardiothoracic centers scale throughput and require reliable supply continuity.
- For instance, W. L. Gore’s GORE-TEX® Suture technical documentation specifies average knot-pull tensile strength limits ranging from 0.075 kg (CV-8) up to 2.7 kg (CV-0), enabling hospitals to standardize suture selection by size/strength requirements for cardiovascular repair workflows.
Growth in minimally invasive and precision cardiac surgery techniques
Cardiac Sutures Market demand is supported by growth in minimally invasive and robotic-assisted cardiac surgery that requires precision handling. Cardiac Sutures Market product selection shifts toward sutures that perform reliably through smaller access ports and specialized needle holders. Cardiac Sutures Market suppliers focus on filament consistency, improved coatings, and needle geometry suited for advanced approaches. Cardiac Sutures Market benefits as precision surgery expands in high-volume centers and drives adoption of premium closure products.
Cardiac Sutures Market Challenges
Cardiac Sutures Market faces substitution pressure in specific procedure steps where device-based closure methods and transcatheter approaches reduce suturing requirements. Cardiac Sutures Market demand can be constrained by procedure migration from open surgery to catheter-based valve interventions for eligible patients. Cardiac Sutures Market purchasing can also be affected by strict hospital cost controls and tender-based procurement, particularly in price-sensitive regions. Cardiac Sutures Market suppliers must balance premium innovation with competitive pricing to sustain share across varied healthcare systems.
- For instance, Medtronic reports that more than 575,000 people worldwide have undergone a Medtronic TAVR procedure, illustrating how catheter-based valve therapy scale can shift treatment pathways and reduce suturing needs in some valve workflows.
Cardiac Sutures Market also faces operational challenges related to surgeon preference variability and lengthy validation cycles for new materials in cardiac settings. Cardiac Sutures Market product changes often require surgeon training, clinical confidence building, and hospital committee approvals. Cardiac Sutures Market supply reliability remains critical because cardiac centers cannot tolerate disruptions in closure consumables. Cardiac Sutures Market quality expectations are stringent, increasing regulatory and manufacturing complexity for advanced material formats.
Cardiac Sutures Market Trends and Opportunities
Cardiac Sutures Market shows opportunity in premium absorbable formats and specialized needle–suture combinations designed for high-precision closure. Cardiac Sutures Market innovation increasingly targets lower tissue drag, improved handling, and enhanced visibility during cardiovascular stitching. Cardiac Sutures Market suppliers also pursue coated and antimicrobial positioning to support safer healing pathways in high-risk surgical patients. Cardiac Sutures Market growth benefits from procedure-kit customization that aligns product sets with CABG and valve repair workflows.
- For instance, Meril reported using LASER welding to attach suture needles and showed higher needle-pull performance versus a channel-swaged benchmark, with an average needle pull of 42.281 kgf (min 43.307; max 45.328) compared with 38.038 kgf (min 38.742; max 39.799) in the cited comparison table (size 6).
Cardiac Sutures Market also presents opportunities in emerging-market expansion through local manufacturing, distributor partnerships, and hospital network penetration. Cardiac Sutures Market demand increases as specialty cardiac hospitals grow across Asia Pacific and parts of Latin America. Cardiac Sutures Market vendors can capture share by offering cost-effective product tiers while maintaining quality assurance expectations. Cardiac Sutures Market adoption can accelerate through surgeon education and clinical support programs tied to advanced suture handling.
Regional Insights
North America
North America accounted for 46.2% of Cardiac Sutures Market revenue in 2025. Cardiac Sutures Market demand in North America is supported by high volumes of cardiac surgery, advanced hospital infrastructure, and adoption of premium closure materials. Cardiac Sutures Market procurement is reinforced by standardized operating room protocols and strong supplier availability across major cardiac centers. Cardiac Sutures Market also benefits from advanced training ecosystems that accelerate uptake of specialized needle–suture combinations.
Europe
Europe represented 24.4% of Cardiac Sutures Market revenue in 2025. Cardiac Sutures Market demand in Europe is supported by established cardiothoracic surgery capacity and structured healthcare systems that sustain procedural throughput. Cardiac Sutures Market purchasing is shaped by centralized procurement and value-based evaluation, supporting steady demand across major markets. Cardiac Sutures Market growth is reinforced by ongoing valve and coronary interventions performed in tertiary care hospitals and specialty centers.
Asia Pacific
Asia Pacific accounted for 21.1% of Cardiac Sutures Market revenue in 2025. Cardiac Sutures Market expansion in Asia Pacific is supported by growing access to cardiac surgery, increased investment in specialty hospitals, and rising burden of cardiovascular disease. Cardiac Sutures Market product mix balances affordability with increasing demand for higher-performance sutures in top-tier centers. Cardiac Sutures Market growth is strengthened by scale-up of cardiothoracic capacity and broader coverage expansion in large population countries.
Latin America
Latin America held 5.4% of Cardiac Sutures Market revenue in 2025. Cardiac Sutures Market demand in Latin America is concentrated in major urban hospital networks and private specialty facilities. Cardiac Sutures Market purchasing is influenced by reimbursement limitations and uneven access to advanced cardiac surgery in certain geographies. Cardiac Sutures Market growth is supported by modernization of hospital infrastructure and gradual expansion of specialty cardiac care services.
Middle East & Africa
Middle East & Africa accounted for 2.9% of Cardiac Sutures Market revenue in 2025. Cardiac Sutures Market demand is supported by specialized cardiac centers in GCC countries and select South African institutions. Cardiac Sutures Market growth is constrained by uneven cardiac surgery availability across broader regional healthcare systems. Cardiac Sutures Market suppliers typically address the region through distributor-led models and targeted hospital network engagement.
Competitive Landscape
Cardiac Sutures Market competition is shaped by product portfolio breadth, clinical performance consistency, and the ability to support procedure-specific needs for CABG and valve repair. Cardiac Sutures Market leaders differentiate through advanced materials, coatings, and engineered needle–suture combinations that improve handling and reliability in delicate cardiovascular tissues. Cardiac Sutures Market procurement increasingly favors suppliers that can ensure continuity of supply, standardized kits, and clinical education support. Cardiac Sutures Market participants also compete on pricing tiers to address both premium and value segments across regions.
Johnson & Johnson (Ethicon) positions within Cardiac Sutures Market are supported by broad surgical closure portfolios, strong hospital relationships, and the ability to bundle suture offerings into standardized operating room workflows. Johnson & Johnson (Ethicon) differentiation in Cardiac Sutures Market is reinforced by portfolio depth across absorbable and non-absorbable formats and continued emphasis on performance-focused product variants. Johnson & Johnson (Ethicon) also benefits from scale in manufacturing and distribution, supporting consistent availability for high-volume cardiac centers. Johnson & Johnson (Ethicon) capabilities can support adoption in complex cardiac procedures through training resources and clinical support programs.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Johnson & Johnson (Ethicon)
- Medtronic plc
- B. Braun Melsungen AG
- Teleflex Incorporated
- W. L. Gore & Associates
- Smith & Nephew plc
- DemeTECH Corporation
- Meril Life Sciences
- Healthium Medtech
- Peters Surgical
- Sutures India
- Gunze Limited
- Lotus Surgicals
- Dolphin Sutures
- SMI AG
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In Jan 2024, Johnson & Johnson (Ethicon) expanded visibility around advanced suture variants positioned for improved surgical site outcomes, supporting differentiated closure portfolios in high-acuity procedures.
- In February 2025, Meril Life Sciences (India) unveiled an expanded cardiovascular surgical portfolio that includes advanced cardiac suture needles and specialized sutures designed to enhance precision in cardiac procedures. The launch introduced Hemovas Needles (engineered to minimize blood loss during vessel extraction), V-Black Needles (featuring tissue and plexiglass penetrators for reduced trauma), and C2 Calcified Coronary Needles (optimized for penetrating calcified vessels).
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1589 million |
| Revenue forecast in 2032 | USD 3019 million |
| Growth rate (CAGR) | 9.6% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Type Outlook: Absorbable Sutures, Non-Absorbable Sutures; By Material Type Outlook: Natural, Synthetic; By Structure Outlook: Monofilament, Multifilament / Braided; By Needle Type Outlook: Blunt-Tip Needles, Sharp-Tip Needles; By Application Outlook: Open-Heart Surgery, Cardiac Valve Repair, Coronary Artery Bypass Grafting (CABG), Other Cardiac Surgeries; By End-User Outlook: Cardiac & Cardiothoracic Surgery Centers, Specialty Cardiac Hospitals, Academic & Research Hospitals, Ambulatory Surgical Centers (ASCs) |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Johnson & Johnson (Ethicon); Medtronic plc; B. Braun Melsungen AG; Teleflex Incorporated; W. L. Gore & Associates; Smith & Nephew plc; DemeTECH Corporation; Meril Life Sciences; Healthium Medtech; Peters Surgical; Sutures India; Gunze Limited; Lotus Surgicals; Dolphin Sutures; SMI AG |
| No.of Pages | 342 |
Segmentation
By Type
- Absorbable Sutures
- Non-Absorbable Sutures
By Material Type
- Natural
- Synthetic
By Structure
- Monofilament
- Multifilament / Braided
By Needle Type
- Blunt-Tip Needles
- Sharp-Tip Needles
By Application
- Open-Heart Surgery
- Cardiac Valve Repair
- Coronary Artery Bypass Grafting (CABG)
- Other Cardiac Surgeries
By End-User
- Cardiac & Cardiothoracic Surgery Centers
- Specialty Cardiac Hospitals
- Academic & Research Hospitals
- Ambulatory Surgical Centers (ASCs)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of Cardiac Sutures Market in 2025 and what is the forecast for 2032?
What is the CAGR for Cardiac Sutures Market during 2025–2032?
Which segment is the largest in Cardiac Sutures Market?
What factors are driving Cardiac Sutures Market growth?
Who are the leading companies in Cardiac Sutures Market?
Which region leads Cardiac Sutures Market in 2025?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cardiac Sutures Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cardiac Sutures Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 1,589 million → 2032: USD 3,019 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cardiac Sutures Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cardiac Sutures Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cardiac Sutures Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cardiac Sutures Market Drivers
- 3.3 Cardiac Sutures Market Restraints & Challenges
- 3.4 Cardiac Sutures Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cardiac Sutures Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cardiac Sutures Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cardiac Sutures category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cardiac Sutures Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cardiac Sutures Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cardiac Sutures market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cardiac Sutures Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cardiac Sutures Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cardiac Sutures Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cardiac Sutures (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cardiac Sutures Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cardiac Sutures Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cardiac Sutures Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cardiac Sutures Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cardiac Sutures Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cardiac Sutures Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cardiac Sutures Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cardiac Sutures Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cardiac Sutures Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
