
Market Overview
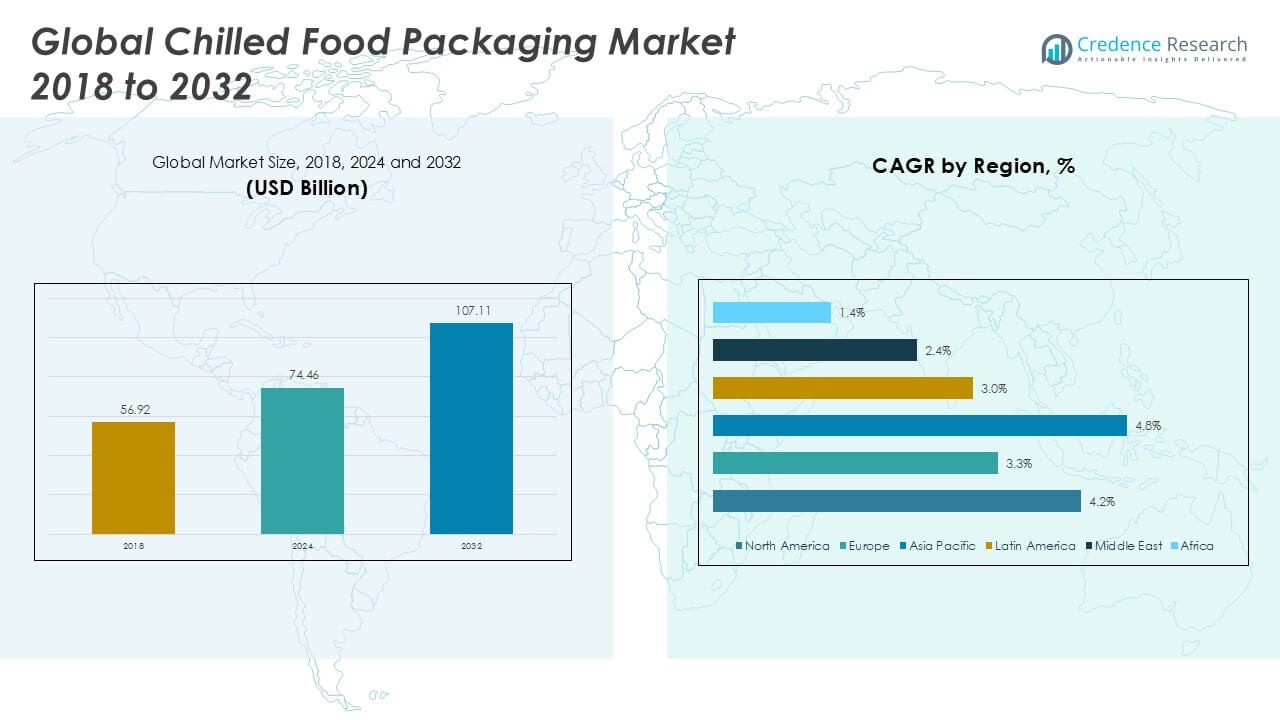
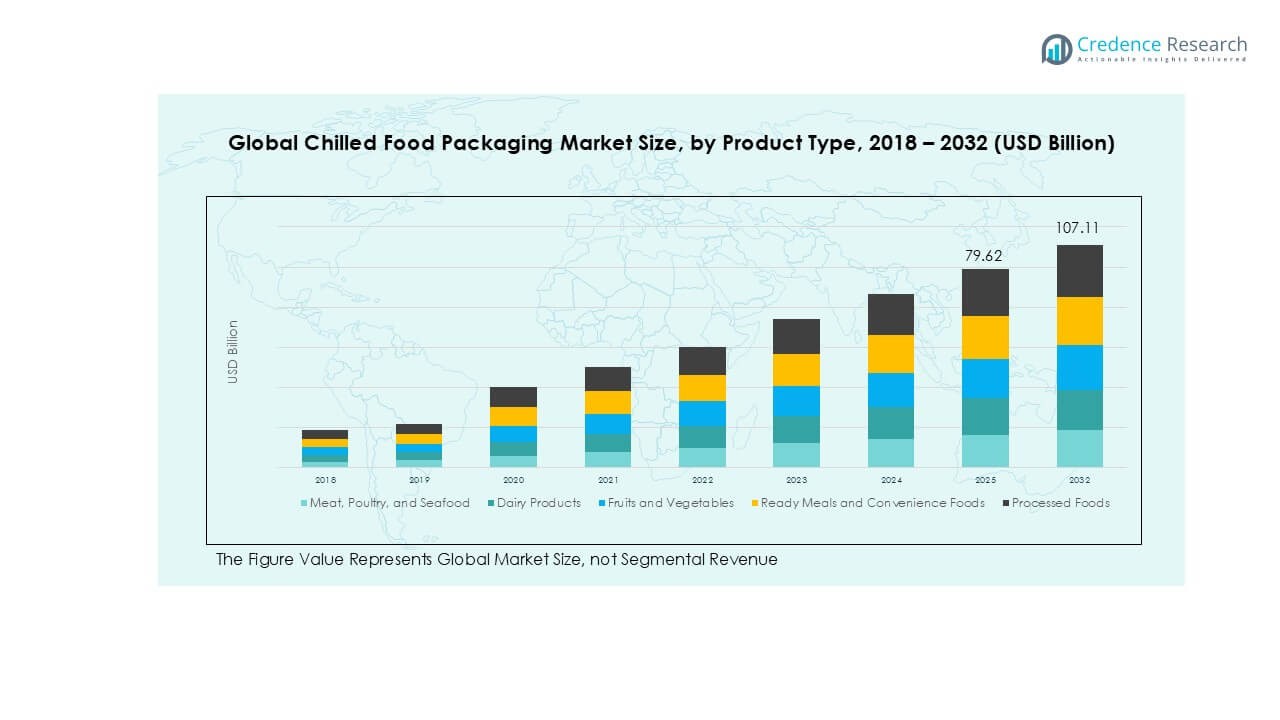
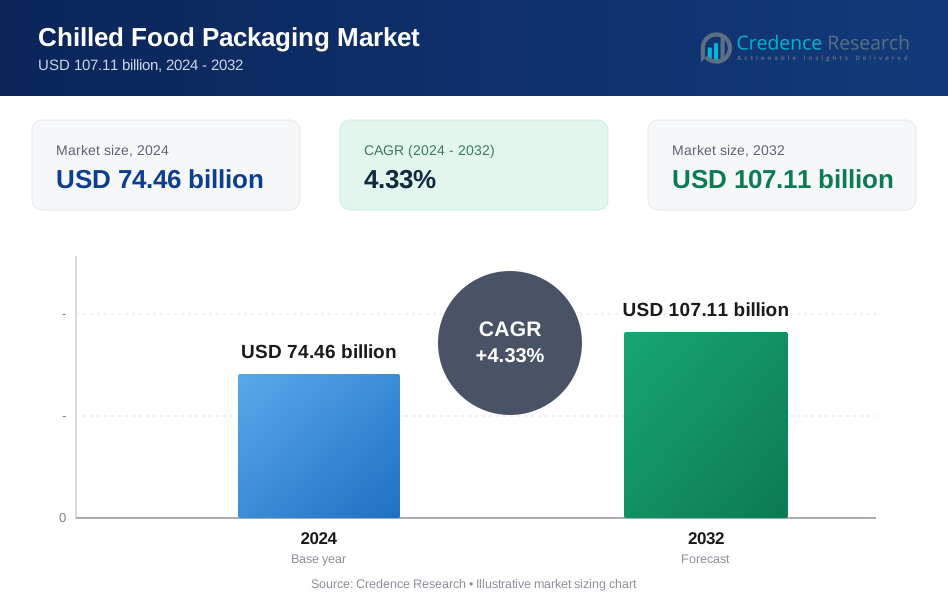
Chilled Food Packaging market size was valued at USD 56.92 billion in 2018, reached USD 74.46 billion in 2024, and is anticipated to reach USD 107.11 billion by 2032, at a CAGR of 4.33% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Chilled Food Packaging Market Size 2024 | USD 74.46 Billion |
| Chilled Food Packaging Market, CAGR | 4.33% |
| Chilled Food Packaging Market Size 2032 | USD 107.11 Billion |
The chilled food packaging market is led by major players such as Amcor Limited, Berry Global, Sealed Air Corporation, Mondi Group, Tetra Pak International, Huhtamaki Oyj, WestRock Company, DS Smith Plc, Sonoco Products, and Oji Holdings Corporation. These companies focus on sustainable materials, high-barrier films, and innovative packaging formats to meet growing demand for fresh and ready-to-eat foods. North America holds the largest market share at 44%, driven by strong demand for packaged meat, dairy, and convenience foods supported by advanced cold-chain infrastructure. Europe follows with 28% share, emphasizing recyclable and compostable solutions under strict EU regulations. Asia Pacific, with 18%, is the fastest-growing region due to rising retail expansion, e-commerce, and investments in cold-chain logistics.
Market Insights
- The chilled food packaging market was valued at USD 56.92 billion in 2018, reached USD 74.46 billion in 2024, and is projected to hit USD 107.11 billion by 2032, growing at a CAGR of 4.33%.
- Rising demand for fresh, convenient, and ready-to-eat foods drives adoption of advanced packaging formats such as MAP trays, vacuum packs, and resealable pouches to extend shelf life.
- Key trends include a strong shift toward recyclable PET trays, compostable films, and automation-friendly packaging, alongside growing investment in smart packaging technologies.
- The market is competitive, with Amcor, Berry Global, Sealed Air, Mondi, and Tetra Pak leading through product innovation and sustainability strategies, while regional players focus on cost-effective and localized solutions.
- North America holds 44% share, followed by Europe at 28% and Asia Pacific at 18%; meat, poultry, and seafood packaging remain the dominant product segment globally.
Market Segmentation Analysis:
By Product Type
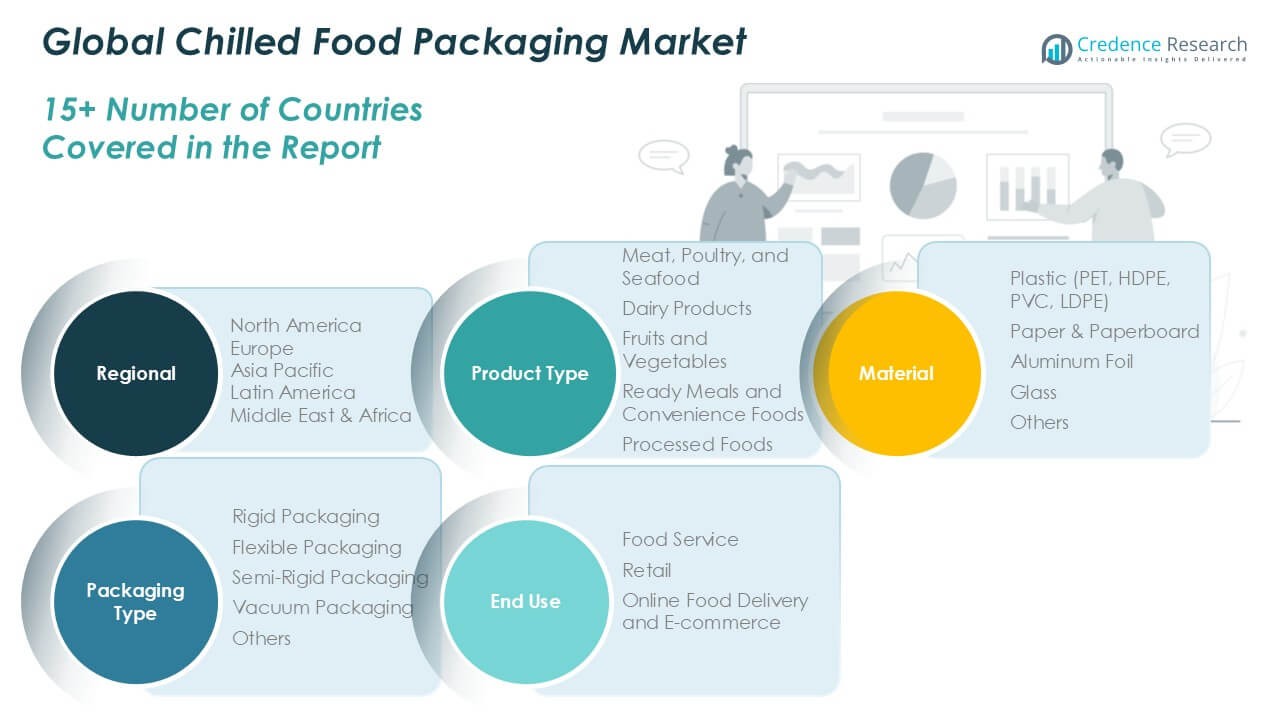
Meat, poultry, and seafood lead the chilled food packaging market, accounting for the largest revenue share. This dominance is driven by the high perishability of animal protein products, requiring advanced packaging solutions to extend shelf life and ensure food safety. Modified atmosphere packaging (MAP) and vacuum-sealed trays are widely used to preserve freshness during transport and retail display. Demand for packaged ready-to-cook meat and seafood products continues to rise with changing consumer lifestyles. Dairy products and ready meals follow as key segments, supported by growth in urban consumption and demand for convenient, portioned packaging formats.
- For instance, in 2023, Tetra Pak delivered 179 billion food and beverage packages worldwide, a figure that includes both chilled and shelf-stable cartons. This large volume of packaging reflects strong demand in the ready-to-drink (RTD) market for products like milk and yogurt, among other segments.
By Material
Plastic remains the most widely used material, holding the largest share of the chilled food packaging market. PET and HDPE dominate due to their durability, transparency, and ability to maintain product integrity under chilled conditions. The segment benefits from cost-effectiveness, lightweight properties, and compatibility with automation-friendly packaging lines. Sustainability initiatives encourage the use of recyclable and bio-based plastics, which attract investments from major packaging producers. Paper and paperboard gain traction in secondary packaging, while aluminum foil serves high-barrier applications. Glass and other materials hold niche demand in premium food segments.
- For instance, in 2023, Amcor's AmPrima™ range of recycle-ready flexible packaging received recognition for its work with Cathedral City cheese and was also named a winner in the Australian Financial Review Sustainability Leaders List for replacing non-recyclable materials in Australia and New Zealand.
By Packaging Type
Rigid packaging dominates the chilled food packaging market, driven by its strength, stackability, and ability to protect products during transit. Plastic trays, tubs, and clamshells are extensively used for meat, seafood, and ready meals where tamper evidence and leak resistance are critical. Growth in flexible packaging is supported by lightweight pouches and films, offering cost savings and reduced environmental footprint. Semi-rigid and vacuum packaging cater to extended shelf-life applications, particularly for processed meats and cheeses. The demand for sustainable rigid packaging made from recycled content is also rising, driven by retailer commitments and consumer preference for eco-friendly solutions.
Key Growth Drivers
Rising Demand for Fresh and Convenient Foods
The growing preference for fresh, ready-to-eat, and minimally processed foods fuels market demand. Urban consumers increasingly seek convenience without compromising product quality. This drives adoption of advanced chilled packaging solutions like vacuum-sealed trays, modified atmosphere packaging (MAP), and resealable pouches. These solutions extend shelf life while maintaining taste and nutrition. Rising working populations and dual-income households boost demand for quick meal options, directly supporting the growth of chilled packaging solutions across meat, dairy, and ready meal categories.
- For instance, Sealed Air's CRYOVAC brand of food packaging provides solutions for meat and poultry products to extend freshness for customers worldwide.
Expansion of Retail and E-commerce Distribution
Supermarkets, hypermarkets, and online grocery platforms are expanding chilled food availability, driving packaging demand. Efficient cold-chain infrastructure allows safe transportation and storage of perishable products. Packaging plays a critical role in maintaining temperature control and product appeal across diverse retail channels. Growth in e-commerce food delivery services further boosts demand for leak-proof, tamper-evident, and insulated packaging formats. This trend is especially strong in emerging markets where organized retail penetration is increasing.
- For instance, in 2024, Walmart operated over 4,600 stores in the U.S., with plans to expand and improve its grocery pickup and delivery services. The company is modernizing its supply chain with new and expanded high-tech distribution centers, and expanding its InHome delivery service to more households. For its online grocery services, temperature-controlled packaging is necessary for fresh and frozen items to ensure safety and quality.
Advances in Packaging Materials and Technology
Innovations in barrier materials, biodegradable plastics, and smart packaging technologies support market growth. High-performance plastics like PET and LDPE improve product protection, while recyclable materials meet sustainability goals. Smart packaging solutions with temperature indicators and QR codes enhance supply chain transparency and consumer trust. Automation-friendly designs also enable cost-efficient large-scale production. These advancements improve operational efficiency for manufacturers while aligning with global regulations on food safety and waste reduction.
Key Trends & Opportunities
Shift Toward Sustainable Packaging Solutions
Growing regulatory pressure and consumer awareness drive adoption of eco-friendly chilled packaging materials. Companies invest in recyclable PET trays, compostable films, and paper-based solutions to reduce plastic waste. Circular economy initiatives encourage packaging manufacturers to use recycled content and design for reusability. This trend presents opportunities for players to differentiate through sustainable innovation and capture environmentally conscious customers.
- For instance, Huhtamaki introduced its Push Tab® blister lid, made with 100% mono-material PET, in 2022. The product improves sustainability by replacing the aluminum in traditional blister packs and making the packaging recyclable.
Growth of Ready Meals and Plant-Based Products
Demand for convenient, healthy, and plant-based meal options is rising globally, creating strong opportunities for chilled packaging suppliers. Packaging formats that support extended shelf life without preservatives, such as vacuum-sealed pouches and MAP trays, are in high demand. Manufacturers offering tailored packaging for plant-based proteins, vegan meals, and premium ready-to-eat products can capture a growing niche segment with higher margins.
- For instance, in 2023, Nestlé launched several new plant-based products, including fish alternatives under its Garden Gourmet brand in Europe. However, the company also scaled back some of its plant-based retail offerings in certain markets, such as the UK and Ireland, during the same year due to slower market growth.
Key Challenges
High Cost of Sustainable Materials
While demand for eco-friendly solutions is rising, the cost of recyclable and biodegradable materials remains high. Manufacturers face challenges in balancing sustainability goals with price-sensitive consumer markets. The higher cost of innovation and material sourcing can limit adoption, particularly in developing regions with lower purchasing power.
Stringent Food Safety and Regulatory Compliance
Compliance with global food safety standards, labeling laws, and environmental regulations is becoming more complex. Manufacturers must invest in high-quality materials and testing processes to meet safety requirements. Failure to comply can result in recalls, penalties, and brand reputation damage, creating operational and financial risks for packaging companies.
Regional Analysis
North America
North America leads the chilled food packaging market with a 44% share in 2018, valued at USD 25.12 billion. The market grew to USD 32.52 billion in 2024 and is projected to reach USD 46.91 billion by 2032, at a CAGR of 4.4%. Growth is driven by strong demand for packaged meat, dairy, and ready meals, supported by advanced cold-chain systems. High adoption of modified atmosphere packaging (MAP) and focus on sustainable materials strengthen market expansion. Regulatory compliance and consumer preference for eco-friendly packaging continue to drive innovation across the region.
Europe
Europe accounted for 28% of the market in 2018 with USD 15.84 billion and reached USD 19.97 billion in 2024. It is expected to hit USD 27.01 billion by 2032 at a CAGR of 3.5%. Market growth is influenced by rising consumption of dairy, processed foods, and convenience meals. EU circular economy initiatives push adoption of recyclable and compostable packaging materials. Western Europe remains the largest contributor, with strong demand from large retailers and strict food waste reduction policies encouraging advanced chilled food packaging solutions.
Asia Pacific
Asia Pacific held an 18% share in 2018, valued at USD 10.51 billion, and increased to USD 14.94 billion in 2024. The market is forecast to reach USD 24.46 billion by 2032, growing at the highest CAGR of 6.0%. Rising disposable incomes, urbanization, and retail expansion drive consumption of packaged chilled foods. Growing online food delivery platforms boost demand for tamper-evident and secure packaging. Investments in cold-chain logistics and sustainable solutions across China, India, and Japan are key contributors to regional market growth.
Latin America
Latin America contributed 5% of the global market in 2018 with USD 2.76 billion and expanded to USD 3.56 billion in 2024. It is projected to reach USD 4.55 billion by 2032, growing at a CAGR of 2.8%. Demand is supported by rising consumption of chilled meat, dairy, and processed foods in Brazil, Argentina, and Mexico. Retail expansion and quick-service restaurants drive packaging demand. However, infrastructure gaps and economic fluctuations remain key challenges, prompting suppliers to focus on cost-efficient, durable packaging formats.
Middle East
The Middle East represented 3% of the market in 2018, valued at USD 1.66 billion, and rose to USD 1.99 billion in 2024. It is expected to reach USD 2.43 billion by 2032, registering a CAGR of 2.2%. Growth is supported by strong demand for imported chilled foods and expanding retail infrastructure in GCC countries. Investment in cold storage facilities and packaging that withstands high temperatures drives adoption. High-barrier films and temperature-resistant packaging formats remain in focus for long-distance transportation and food quality maintenance.
Africa
Africa accounted for 2% of the market in 2018 with a value of USD 1.04 billion and reached USD 1.48 billion in 2024. It is forecast to achieve USD 1.76 billion by 2032 at a CAGR of 1.8%. Rising urbanization and increasing awareness of packaged food safety contribute to market growth. South Africa dominates regional demand due to expanding organized retail and higher chilled food consumption. Infrastructure challenges and price sensitivity slow adoption, creating opportunities for affordable, durable, and easy-to-distribute chilled food packaging solutions.
Market Segmentations:
By Product Type
- Meat, Poultry, and Seafood
- Dairy Products
- Fruits and Vegetables
- Ready Meals and Convenience Foods
- Processed Foods
By Material
- Plastic (PET, HDPE, PVC, LDPE)
- Paper & Paperboard
- Aluminum Foil
- Glass
- Others
By Packaging Type
- Rigid Packaging
- Flexible Packaging
- Semi-Rigid Packaging
- Vacuum Packaging
- Others
By End Use
- Food Service
- Retail
- Online Food Delivery and E-commerce
By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Competitive Landscape
The chilled food packaging market is highly competitive, with global and regional players focusing on product innovation, sustainability, and strategic partnerships. Leading companies such as Amcor Limited, Berry Global, Sealed Air Corporation, Mondi Group, and Tetra Pak International dominate the market with strong distribution networks and diversified product portfolios. These players invest heavily in recyclable and compostable packaging solutions to meet rising sustainability demands. Mergers, acquisitions, and collaborations are common strategies to expand geographic presence and strengthen technological capabilities. Regional players such as Huhtamaki Oyj, WestRock Company, and DS Smith Plc compete by offering cost-efficient, customized solutions for local markets. Continuous R&D efforts drive innovation in high-barrier films, lightweight materials, and automation-friendly formats. Competitive intensity remains high as companies strive to balance cost efficiency, regulatory compliance, and consumer demand for eco-friendly, high-performance packaging formats across meat, dairy, and ready-meal segments.
Key Player Analysis
- Amcor Limited
- Berry Global, Inc.
- Sealed Air Corporation
- Mondi Group
- Sonoco Products Company
- Tetra Pak International S.A.
- Huhtamaki Oyj
- WestRock Company
- DS Smith Plc
- Oji Holdings Corporation
Recent Developments
- In June 2025, Mondi Group launched a product named ‘Grow&Go’. This innovative packaging theme was introduced specially for agricultural products. Right from farms, the products can be kept fresh throughout their shelf-life. The innovative product has received enormous demand.
- In May 2025, Amcor and Metsä Group announced a partnership to develop molded fiber-based food packaging, focusing on sustainability and recyclability for chilled and frozen products.
- In 2025, Berry Global outlined circular packaging solutions at Foodex 2025, including mono-materials for enhanced recyclability and increased recycled content in shrink films and stretch wrap for pallets.
- In June 2023, Amcor Ltd. acquired Bemis Company Inc., where the acquisition of Bemis Company brings additional capabilities, scale and footprint that strengthened Amcor’s industry leading value proposition. Amcor is responsible for food packaging, beverage, pharmaceutical, personal care and consumer products.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Packaging Type, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sustainable and recyclable packaging will rise due to strict environmental regulations.
- Adoption of bio-based plastics and compostable films will expand across major food categories.
- Smart packaging with freshness indicators and QR codes will gain popularity for transparency.
- Automation in packaging lines will grow to improve efficiency and reduce operational costs.
- Flexible packaging formats will see higher adoption for ready meals and convenience foods.
- Cold-chain infrastructure investments will strengthen in Asia Pacific and emerging markets.
- E-commerce and online food delivery will create demand for tamper-evident and secure packaging.
- Lightweight packaging materials will gain traction to reduce transportation and logistics costs.
- Regional players will collaborate with retailers to offer cost-effective, localized solutions.
- Circular economy initiatives will drive innovation in reusable and recyclable chilled packaging systems
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Chilled Food Packaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Chilled Food Packaging market projected to grow between 2025 and 2032?
Which Chilled Food Packaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Chilled Food Packaging market?
Who are the leading companies in the Chilled Food Packaging market?
Which region commanded the largest share of the Chilled Food Packaging market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Chilled Food Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Chilled Food Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 74.46 billion → 2032: USD 107.11 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Chilled Food Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Chilled Food Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Chilled Food Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Chilled Food Packaging Market Drivers
- 3.3 Chilled Food Packaging Market Restraints & Challenges
- 3.4 Chilled Food Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Chilled Food Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Chilled Food Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Chilled Food Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Chilled Food Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Chilled Food Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Chilled Food Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Chilled Food Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Chilled Food Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Chilled Food Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Chilled Food Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Chilled Food Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Chilled Food Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Chilled Food Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Chilled Food Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Chilled Food Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Chilled Food Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Chilled Food Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Chilled Food Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Chilled Food Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
