
Market Overview:
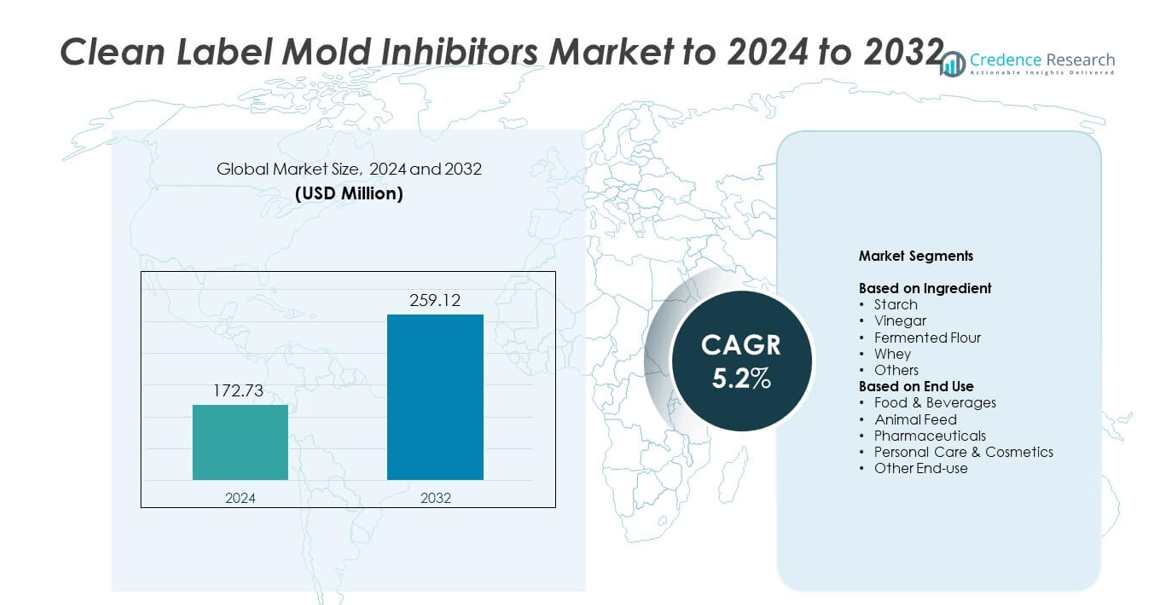
Clean Label Mold Inhibitors Market size was valued at USD 172.73 million in 2024 and is anticipated to reach USD 259.12 million by 2032, at a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Clean Label Mold Inhibitors Market Size 2024 | USD 172.73 million |
| Clean Label Mold Inhibitors Market, CAGR | 5.2% |
| Clean Label Mold Inhibitors Market Size 2032 | USD 259.12 million |
The clean label mold inhibitors market is shaped by leading companies such as Kerry Group plc, Corbion N.V., DSM Food Specialties, Kalsec Inc., and Puratos Group. These players focus on developing bio-based and fermentation-derived solutions to meet rising demand for natural food preservation. Their strategies emphasize sustainability, clean-label compliance, and formulation stability across bakery, dairy, and beverage sectors. North America led the global market with a 36.2% share in 2024, supported by strong adoption of natural preservatives and advanced food processing infrastructure. Europe followed with 29.8%, driven by strict regulatory standards and growing consumer preference for additive-free products.]
Market Insights
- The clean label mold inhibitors market was valued at USD 172.73 million in 2024 and is projected to reach USD 259.12 million by 2032, growing at a CAGR of 5.2%.
- Rising demand for natural preservatives and clean-label food formulations is driving market growth, supported by regulatory pressure to reduce synthetic additives.
- Fermentation-derived and plant-based ingredients such as vinegar and fermented flour are key trends, with increased R&D toward improving formulation stability and cost efficiency.
- The market is moderately consolidated, with players focusing on innovation, bio-based preservation technologies, and strategic partnerships to strengthen product portfolios.
- North America led the market with a 36.2% share in 2024, followed by Europe at 29.8%, while the food and beverages segment dominated end-use applications with 61.7% share, reflecting strong adoption of clean-label preservation across bakery and dairy industries.
Market Segmentation Analysis:
By Ingredient
Vinegar dominated the clean label mold inhibitors market in 2024 with a 38.4% share. Its strong antimicrobial properties and acceptance as a natural preservative make it widely used across bakery and dairy applications. Rising consumer demand for chemical-free preservation methods supports its growth. Fermented flour and whey are also gaining traction due to their multifunctional benefits in improving flavor and texture. Manufacturers increasingly use starch-based inhibitors for moisture control and shelf-life extension in clean-label baked goods, enhancing product stability without synthetic additives.
- For instance, Corbion’s Verdad® F95 is used at a recommended usage level of 0.9% on flour weight, which can effectively replace calcium propionate for breads needing a 7–10 days shelf life, while another solution, Verdad MP 100, is used at 2.5% on flour weight for products requiring a longer, 10–20 days shelf life.
By End Use
The food and beverages segment accounted for 61.7% of the clean label mold inhibitors market in 2024, leading overall demand. The growth is driven by increasing adoption in bakery, confectionery, and dairy products where natural preservation is essential. Consumers prefer clean-label products free from chemical preservatives, prompting food manufacturers to use vinegar, fermented flour, and whey derivatives. Animal feed and pharmaceutical applications are expanding gradually, while personal care uses are growing as formulators adopt bio-based antimicrobials for extended product safety.
- For instance, Gardenia Philippines operates a total of 5 major, fully automated bakery plants strategically located across Luzon, Visayas, and Mindanao. The facilities are located in Laguna, Mabalacat (Pampanga), Cebu, and Cagayan de Oro.
Key Growth Drivers
Rising Demand for Natural Preservatives
Growing consumer preference for clean-label and chemical-free foods is driving the use of natural mold inhibitors. Food producers are replacing synthetic agents like calcium propionate with plant-based or fermentation-derived alternatives such as vinegar and fermented flour. This transition aligns with stricter labeling standards and rising health awareness. Manufacturers are responding by investing in bio-preservation technologies that maintain freshness and extend shelf life without synthetic additives, reinforcing product transparency and consumer trust.
- For instance, IFF’s MicroGARD 100 shows usage levels of 0.3–0.6% in yogurt and 0.5–1.5% in sauces and fresh soups to inhibit yeasts and molds.
Expansion of the Bakery and Dairy Industry
The bakery and dairy industries are key consumers of clean label mold inhibitors due to their susceptibility to microbial spoilage. Increasing global consumption of baked goods, cheeses, and ready-to-eat items fuels product demand. Clean label inhibitors help maintain texture and flavor while extending shelf stability. The growth of artisanal and organic bakery chains, particularly in North America and Europe, further accelerates adoption. This expansion strengthens the market’s reliance on natural ingredients that meet both safety and quality expectations.
- For instance, Grupo Bimbo operates 249 bakeries and plants and more than 1,500 sales centers across 39 countries (with a total presence in 91 countries worldwide through partnerships) broadening outlets for clean-label inhibitors.
Regulatory Push Toward Food Safety and Transparency
Tightening global food safety regulations encourage the adoption of natural mold inhibitors over chemical ones. Regulatory bodies such as the FDA and EFSA are promoting transparency in ingredient labeling. This creates an incentive for manufacturers to reformulate products with clean-label components that are safe, traceable, and sustainable. The rise of eco-conscious consumers and stricter labeling norms worldwide drive companies to comply with cleaner ingredient standards, fostering innovation in natural preservation solutions.
Key Trends & Opportunities
Adoption of Fermentation-Based Preservation Solutions
Fermentation technology is gaining traction as an effective and natural preservation method. Microbial cultures and fermented substrates such as flour and whey are increasingly used to produce inhibitors with multifunctional benefits, including flavor enhancement and improved product stability. The shift toward biotechnological solutions offers manufacturers greater flexibility in developing customized clean-label formulations, supporting both functional and sensory advantages.
- For instance, Novonesis’ FreshQ cultures indicate a 7-day yogurt shelf-life extension in a validated study aimed at cutting waste.
Expansion in Emerging Economies
Developing markets in Asia-Pacific and Latin America present new growth opportunities due to changing dietary habits and urbanization. Rising consumption of packaged foods and bakery products increases the need for natural preservatives. Local manufacturers are investing in clean-label solutions to meet evolving consumer expectations. As awareness of food safety and natural ingredients grows, these regions are likely to experience a significant surge in demand for natural mold inhibitors.
- For instance, Britannia runs 13 factories and sells close to 1,000,000 bread loaves daily across 100+ Indian cities, accelerating natural-preservative uptake.
Innovation in Plant-Based Formulations
The increasing interest in plant-derived preservatives is fueling R&D across the clean label mold inhibitors landscape. Extracts from herbs, spices, and organic acids are being explored as natural antimicrobial agents. These innovations offer improved sustainability and meet consumer demand for vegan and allergen-free formulations. Continuous advancements in extraction and stabilization technologies support the development of efficient plant-based inhibitor blends suitable for diverse food applications.
Key Challenges
High Production and Formulation Costs
Natural mold inhibitors often require complex extraction and fermentation processes that increase production costs. Their shorter shelf life and variability in antimicrobial efficiency also pose challenges in scaling operations. Compared to synthetic alternatives, natural inhibitors demand higher investment in R&D and process optimization. This cost disparity can limit adoption among small and mid-sized food producers, especially in price-sensitive markets.
Limited Shelf-Life Efficiency in Harsh Conditions
Natural inhibitors may show reduced performance under extreme storage or processing conditions. Temperature fluctuations and high-moisture environments can diminish their efficacy, affecting product safety and quality. Ensuring consistent antimicrobial activity without chemical preservatives remains a technical challenge for manufacturers. The need for improved formulation stability drives ongoing innovation but also slows widespread commercialization of clean-label alternatives.
Regional Analysis
North America
North America held the largest share of 36.2% in the clean label mold inhibitors market in 2024. The region’s dominance is driven by strong demand for natural preservatives across bakery, dairy, and convenience food sectors. Consumers prefer products with transparent labels and minimal chemical additives. Major food manufacturers are reformulating products to comply with FDA guidelines on clean-label standards. The growing influence of health-conscious consumers in the United States and Canada continues to push innovation in fermentation-based inhibitors and bio-preservatives, supporting the regional market’s steady expansion.
Europe
Europe accounted for 29.8% of the global clean label mold inhibitors market in 2024. The region’s growth is influenced by stringent EU regulations promoting natural and sustainable food ingredients. Rising demand for organic and additive-free bakery and dairy products strengthens the adoption of vinegar and fermented flour-based inhibitors. Countries like Germany, France, and the U.K. lead in clean-label food reformulation, supported by consumer preference for minimally processed foods. Continuous research investments in bio-based preservatives enhance Europe’s position as a key market for sustainable food preservation technologies.
Asia-Pacific
Asia-Pacific captured 22.6% of the clean label mold inhibitors market in 2024, emerging as the fastest-growing region. Expanding urbanization and rising disposable incomes are fueling demand for packaged and ready-to-eat foods. Manufacturers in China, Japan, and India are increasingly adopting natural preservation systems to meet evolving consumer preferences. Growing awareness about food safety and the influence of Western dietary trends support the shift toward clean-label formulations. The expanding bakery and dairy industries across Southeast Asia further strengthen regional demand for vinegar and fermented ingredient-based inhibitors.
Latin America
Latin America accounted for 7.4% of the clean label mold inhibitors market in 2024. The region is experiencing growing adoption of natural preservatives due to the rising consumption of packaged bakery and snack foods. Brazil and Mexico lead market expansion, driven by a shift toward healthier diets and clean-label food production. Local manufacturers are incorporating vinegar and fermentation-based inhibitors to enhance shelf stability and meet export requirements. Increasing participation of regional food processors in global supply chains supports greater alignment with international clean-label standards.
Middle East & Africa
The Middle East & Africa region held a 4% share of the clean label mold inhibitors market in 2024. Growth is supported by expanding processed food consumption and higher awareness of food safety regulations. Demand is increasing for natural preservatives in bakery, dairy, and confectionery products, particularly in the Gulf countries and South Africa. Urbanization and an expanding retail sector drive clean-label adoption among local producers. Although the market remains in a developing stage, growing investments in sustainable food preservation technologies are expected to support long-term growth.
Market Segmentations:
By Ingredient
- Starch
- Vinegar
- Fermented Flour
- Whey
- Others
By End Use
- Food & Beverages
- Animal Feed
- Pharmaceuticals
- Personal Care & Cosmetics
- Other End-use
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The clean label mold inhibitors market features a competitive landscape led by Kerry Group plc, Corbion N.V., DSM Food Specialties, Kalsec Inc., and other prominent global players. Industry participants are prioritizing innovation through bio-based formulations, fermentation-derived ingredients, and plant-extract blends to address rising consumer demand for natural food preservation. Collaborative initiatives with food manufacturers are expanding product reach and enhancing application-specific performance. Continuous R&D investments aim to optimize formulation stability, ensure regulatory compliance, and reduce production costs. Many companies are focusing on advanced encapsulation and extraction technologies to strengthen inhibitor efficiency across various food products. The shift toward sustainability, transparency, and eco-friendly ingredients remains central to competitive strategies, fostering steady market evolution aligned with clean-label and environmentally responsible production trends.
Key Player Analysis
- Kerry Group plc
- Corbion N.V.
- DSM Food Specialties
- Kalsec Inc.
- Puratos Group
- Galactic
- Niacet
- Prinova Group
- BTSA Biotecnologías Aplicadas
- Sacco System
- Hawkins, Inc.
- Handary SA
- Lesaffre Corporation
- Eastman Chemical
- BioVeritas
- J&K Ingredients
- Ribus, Inc.
- Galactic Food Group
- Shenzhen Leveking Bio-Engineering Co., Ltd.
- Kemin Industries, Inc.
Recent Developments
- In 2025, Corbion launched Verdad® Essence WH100, a clean-label mold inhibitor derived from cultured wheat designed for baked goods, and updated its Natural Mold Inhibition Model (CNMIM), a predictive tool.
- In 2024, Kemin Industries Launched Shield V, a clean-label mold inhibitor that blends buffered vinegar with a botanical extract as a non-synthetic source of sorbic acid, positioned as a natural alternative to potassium sorbate; debuted at IFT 2024.
- In 2023, BioVeritas unveiled/introduced a novel clean-label mold inhibitor made from upcycled vegetable oil extracts via a proprietary process, serving as a replacement for calcium propionate in bakery goods.
Report Coverage
The research report offers an in-depth analysis based on Ingredient, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth as demand for natural preservatives continues to rise.
- Increasing consumer awareness of clean-label ingredients will shape product innovation strategies.
- Fermentation-based inhibitors will gain popularity due to their multifunctional and sustainable nature.
- Vinegar and fermented flour will remain preferred ingredients for bakery and dairy preservation.
- Regulatory pressure on synthetic additives will accelerate the shift toward bio-based alternatives.
- Emerging economies will drive new opportunities with expanding processed food consumption.
- Advancements in formulation technology will improve the stability and efficiency of natural inhibitors.
- Plant-derived antimicrobials will gain wider adoption across food, feed, and personal care applications.
- Strategic collaborations between ingredient suppliers and food producers will strengthen market penetration.
- Growing investments in R&D will support the development of cost-effective clean-label preservation solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Clean Label Mold Inhibitors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Clean Label Mold Inhibitors Market projected to grow between 2025 and 2032?
Which Clean Label Mold Inhibitors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Clean Label Mold Inhibitors Market?
Who are the leading companies in the Clean Label Mold Inhibitors Market?
Which region commanded the largest share of the Clean Label Mold Inhibitors Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 172.73 million → 2032: USD 259.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Clean Label Mold Inhibitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Clean Label Mold Inhibitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Clean Label Mold Inhibitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Clean Label Mold Inhibitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Clean Label Mold Inhibitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Clean Label Mold Inhibitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Clean Label Mold Inhibitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Clean Label Mold Inhibitors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 172.73 million → 2032: USD 259.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Clean Label Mold Inhibitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Clean Label Mold Inhibitors Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Clean Label Mold Inhibitors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Clean Label Mold Inhibitors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

