
Market Overview:
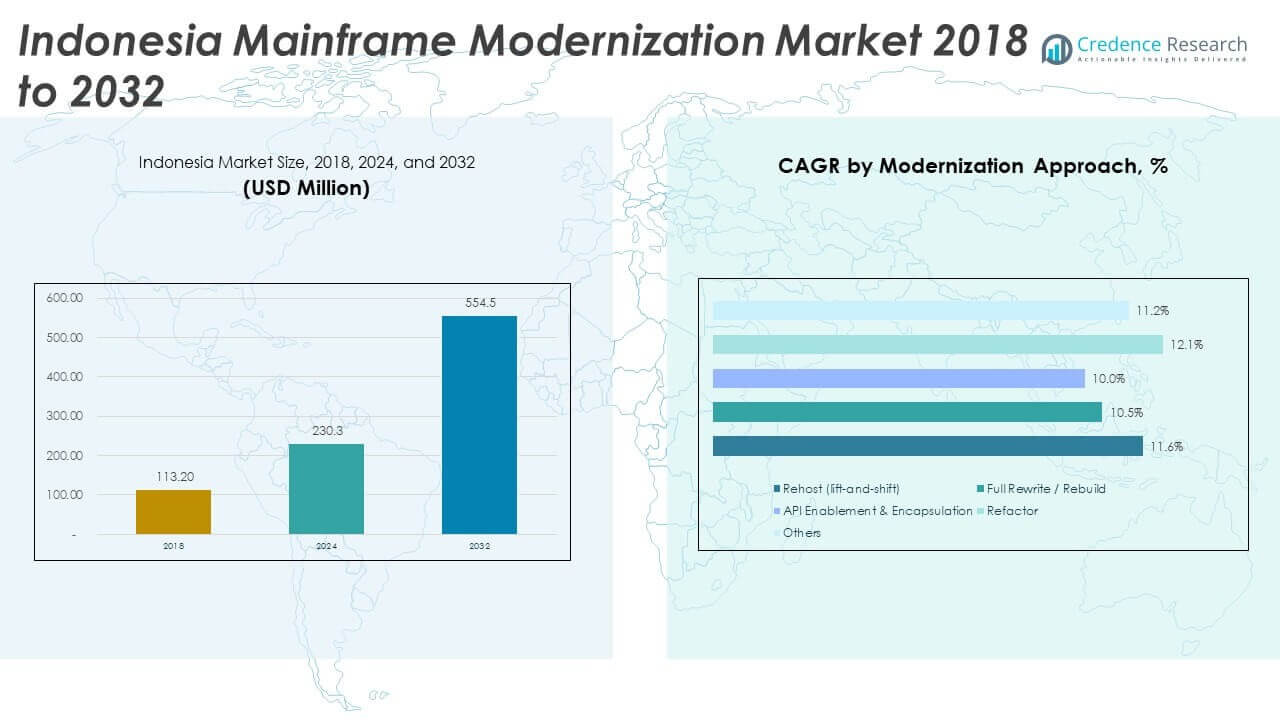
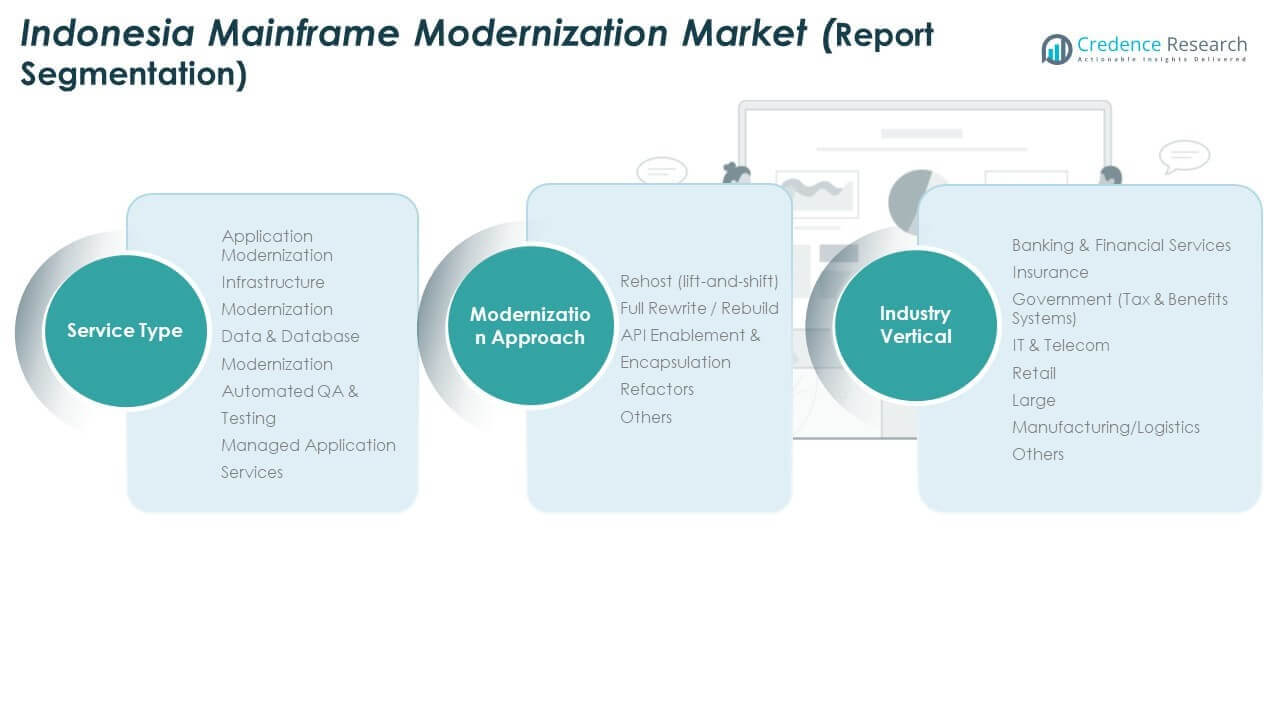
The Indonesia Mainframe Modernization Market size was valued at USD 113.20 million in 2018 to USD 230.28 million in 2024 and is anticipated to reach USD 554.54 million by 2032, at a CAGR of 11.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Indonesia Mainframe Modernization Market Size 2024 | USD 230.28 million |
| Indonesia Mainframe Modernization Market, CAGR | 11.60% |
| Indonesia Mainframe Modernization Market Size 2032 | USD 554.54 million |
The market grows due to rising demand for agile core systems. Enterprises replace legacy mainframes to improve speed and resilience. Digital banking expansion drives platform upgrades across financial institutions. Cloud adoption supports hybrid modernization paths with lower risk. Regulatory pressure increases the need for secure, compliant systems. Talent shortages push firms toward automated tools and managed services. Cost control remains a strong motive for refactoring workloads. API integration enables faster product launches. Business leaders prioritize uptime and scalability. Modern tools reduce technical debt and improve customer experience outcomes.
India leads adoption due to strong IT services capacity and large enterprise bases. Major banks and insurers accelerate modernization programs nationwide. Indonesia emerges rapidly with digital-first banking and fintech growth. Government digitalization efforts support public sector upgrades. Urban centers drive demand through cloud-ready infrastructure. Regional system integrators strengthen delivery capabilities. Southeast Asian peers show rising interest as workloads expand. Cross-border operations favor standardized platforms. Local regulations shape phased migration strategies. Talent ecosystems influence country-level execution speed.
Market Insights:
- The Indonesia Mainframe Modernization Market size stood at USD 113.20 million in 2018, reached USD 230.28 million in 2024, and is projected to hit USD 554.54 million by 2032, expanding at a CAGR of 11.60% during the forecast period.
- India holds around 62% share, Indonesia accounts for 38% share, while other nearby Southeast Asian markets remain marginal, driven by India’s strong IT services base and Indonesia’s rapid digital banking expansion.
- Indonesia represents the fastest-growing region with nearly 38% share, supported by fintech growth, public digital programs, and rising cloud-ready urban infrastructure adoption.
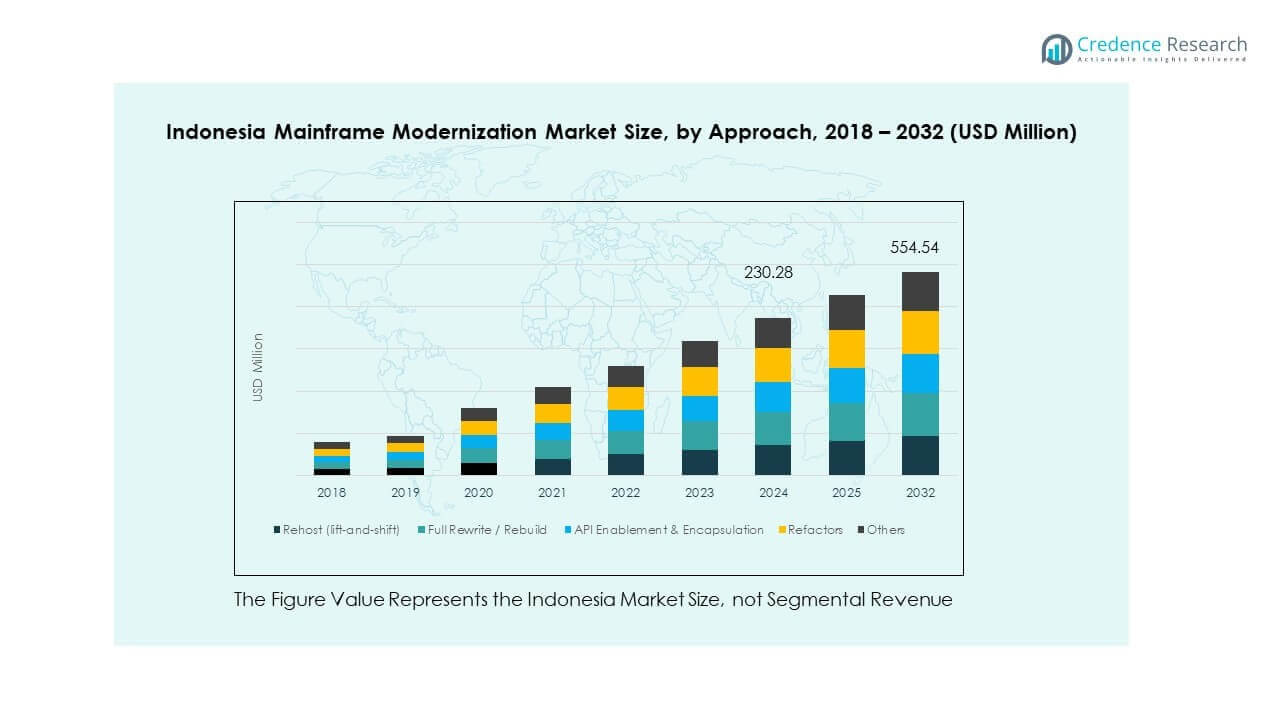
- By modernization approach, Rehost (lift-and-shift) leads with about 30% share, followed by API enablement and encapsulation at nearly 25%, reflecting demand for faster, lower-risk transformation.
- Refactors contribute close to 20% share, while full rewrite/rebuild and others together account for about 25%, showing balanced adoption of deep and phased modernization strategies.
Market Drivers:
Rising Need For Core System Agility And Business Continuity
The Indonesia Mainframe Modernization Market gains momentum from enterprise demand for agility. Legacy systems limit response speed to market change. Banks and insurers require faster product rollout cycles. Core workloads must support real-time processing needs. High transaction volumes demand stable system performance. Downtime risks push firms toward modernization paths. It supports better workload resilience across operations. Decision-makers favor platforms with higher flexibility.
- For instance, IBM Z systems deliver 99.999% availability, supporting uninterrupted processing for large global banks. Decision-makers favor platforms with higher flexibility.
Regulatory Compliance Pressure Across Financial And Public Sectors
Regulatory frameworks tighten data security and reporting norms. Financial regulators enforce strict audit readiness standards. Legacy mainframes face limits in compliance automation. Enterprises modernize systems to meet reporting timelines. Cybersecurity mandates require stronger access control layers. It enables improved governance and monitoring tools. Public sector digital reforms support system upgrades. Compliance costs drive long-term transformation planning.
- For instance, major banks using ISO 27001-aligned platforms improved audit response times through automated compliance reporting. Compliance costs drive long-term transformation planning.
Cost Optimization And Long-Term Infrastructure Sustainability Goals
Operational costs remain high for aging mainframe systems. Hardware maintenance creates recurring capital strain. Enterprises seek predictable cost structures over time. Modern platforms reduce dependency on proprietary systems. It supports better resource utilization across workloads. Budget planners favor scalable infrastructure models. Technology leaders focus on lifecycle cost control. Modernization aligns with financial efficiency goals.
Shortage Of Skilled Legacy System Professionals In Enterprises
Experienced mainframe talent continues to decline regionally. Workforce retirement increases operational risk exposure. Training new staff requires high time investment. Enterprises adopt modernization to reduce skill dependency. It allows use of widely available development skills. Managed services gain preference among large firms. Automation reduces manual system intervention. Talent gaps accelerate transformation decisions.
Market Trends:
Adoption Of Hybrid Modernization Approaches Over Full Replacement Models
Enterprises prefer phased modernization strategies today. Hybrid models balance risk and operational stability. Core systems remain active during transformation cycles. Cloud integration supports gradual workload migration. It reduces disruption to mission-critical operations. Technology leaders favor coexistence architectures. Tool vendors design solutions for mixed environments. This trend reshapes modernization project structures.
- For instance, Microsoft Azure Hybrid enables mainframe-linked workloads to integrate with cloud services used by over 95% of Fortune 500 firms. This trend reshapes modernization project structures.
Growing Preference For API Enablement And Service-Oriented Architectures
Organizations expose mainframe functions through APIs. Service layers improve system interoperability. Digital channels require seamless backend integration. It enables faster partner and fintech collaboration. Microservices adoption supports modular development approaches. Enterprises decouple user interfaces from core logic. Platform openness becomes a key selection factor. Integration capability defines modernization success.
- For instance, DBS Bank operates over 1,000 secure APIs, supporting rapid partner integration across digital banking services. Integration capability defines modernization success.
Increased Role Of System Integrators And Specialized Modernization Vendors
Large enterprises rely on external expertise for execution. System integrators manage complex migration programs. Vendor ecosystems expand across India and Indonesia. It improves access to tested modernization frameworks. Providers offer domain-specific transformation accelerators. Risk mitigation drives outsourcing preference. Long-term support contracts gain traction. Vendor capability influences buyer confidence.
Shift Toward Data-Centric Modernization And Analytics Readiness
Enterprises focus on unlocking legacy data value. Modern platforms improve data accessibility and quality. Analytics adoption requires faster data pipelines. It supports advanced reporting and insights use. Real-time dashboards enhance decision-making processes. Data governance improves through modern architectures. Enterprises align modernization with analytics roadmaps. Data strategy shapes system priorities.
Market Challenges Analysis:
High Transformation Complexity And Operational Risk Exposure
Mainframe modernization involves deep system dependencies. Business logic remains embedded in legacy code. Migration errors can disrupt critical services. Enterprises face limited tolerance for downtime. Testing cycles extend project timelines significantly. It demands strong governance and change control. Stakeholder alignment proves difficult across departments. Risk concerns slow decision-making speed.
Budget Constraints And Uncertain Return On Investment Timelines
Modernization requires high upfront financial commitment. Cost estimation remains difficult in legacy environments. Benefits often appear over long periods. Finance teams question immediate value realization. It complicates approval for large programs. Economic uncertainty tightens IT budgets further. Competing digital priorities dilute funding focus. ROI clarity remains a key hurdle.
Market Opportunities:
Expansion Of Digital Banking And Government Digital Platforms
Digital banking growth increases core system pressure. Public digital platforms require scalable backend support. Enterprises modernize to meet citizen service demand. It creates new project pipelines for vendors. Cross-sector digital initiatives expand addressable demand. National digital agendas support funding access. Platform standardization encourages repeat deployments. Growth aligns with digital transformation goals.
Rising Demand For Managed Modernization And Outcome-Based Services
Enterprises seek predictable delivery and cost models. Managed modernization reduces internal execution burden. Vendors offer outcome-based engagement structures. It improves risk sharing across stakeholders. Subscription models gain acceptance among large firms. Long-term service contracts ensure operational continuity. Local partners strengthen delivery capacity. Service innovation opens new revenue streams.
Market Segmentation Analysis:
By Service Type
Application modernization holds strong demand due to legacy code renewal needs. Enterprises upgrade core applications to improve speed and flexibility. Infrastructure modernization supports hybrid cloud readiness and system resilience. Data and database modernization enables better access, governance, and analytics use. Automated QA and testing reduce migration risk and ensure service continuity. Managed application services gain traction due to skill gaps and uptime needs. The Indonesia Mainframe Modernization Market benefits from service portfolios that balance transformation with operational stability. It reflects buyer preference for end-to-end modernization support.
- For instance, Accenture applies automated testing tools that cut mainframe regression testing cycles by more than 50% in large banking programs. It reflects buyer preference for end-to-end support.
By Modernization Approach
Rehost strategies attract enterprises seeking lower risk and faster execution. Full rewrite and rebuild approaches support deep transformation goals. API enablement and encapsulation improve interoperability with digital platforms. Refactoring helps retain business logic while improving maintainability. Other approaches address niche system requirements and phased transitions. Buyers select methods based on risk tolerance and budget scope. It supports flexible migration paths across complex environments.
- For instance, Kyndryl delivers lift-and-shift mainframe migrations that preserve existing transaction logic while integrating with modern cloud platforms. It supports flexible migration paths across complex environments.
By Industry Vertical
Banking and financial services lead demand due to high transaction volumes. Insurance firms modernize policy and claims systems for efficiency. Government agencies upgrade tax and benefits platforms for scalability. IT and telecom firms align core systems with digital services. Retail enterprises modernize to support omnichannel operations. Manufacturing and logistics firms focus on process integration and reliability. It reflects strong vertical-specific adoption patterns across the region.
Segmentation:
- By Service Type
- Application Modernization
- Infrastructure Modernization
- Data & Database Modernization
- Automated QA & Testing
- Managed Application Services
- By Modernization Approach
- Rehost (Lift-and-Shift)
- Full Rewrite / Rebuild
- API Enablement & Encapsulation
- Refactors
- Others
- By Industry Vertical
- Banking & Financial Services
- Insurance
- Government (Tax & Benefits Systems)
- IT & Telecom
- Retail
- Large Manufacturing / Logistics
- Others
Regional Analysis:
India’s Leadership In Enterprise Modernization And Service Capability
India anchors the Indonesia Mainframe Modernization Market with a dominant revenue share. Large banks, insurers, and public sector units drive frequent core system upgrades. Major IT service providers create a deep ecosystem for consulting and execution. India holds the higher market share due to higher deal volumes and larger ticket sizes. Strong cloud and digital infrastructure supports complex modernization programs. Government digital initiatives push ministries toward scalable, secure architectures. It benefits from mature talent pools and established delivery frameworks.
Indonesia’s Accelerating Adoption And Expanding Modernization Pipeline
Indonesia contributes a smaller yet rapidly expanding share of the market. Local banks, fintechs, and telecom operators modernize platforms to support digital users. Government agencies move legacy workloads toward integrated, citizen-facing systems. Indonesia’s market share rises as more projects shift from pilot to full deployment. Domestic service providers partner with global integrators to close capability gaps. Cloud data centers in key cities support hybrid modernization models. It reflects strong momentum from financial inclusion and e-government strategies.
Cross-Border Synergies And Regional Positioning Across India And Indonesia
India and Indonesia together account for the full regional scope of the Indonesia Mainframe Modernization Market. India contributes the larger share, while Indonesia provides a fast-growing complement. Cross-border projects use Indian delivery hubs to serve Indonesian clients efficiently. Global vendors leverage Indian centers of excellence and local Indonesian partners. Shared regulatory themes in banking and public services support reusable modernization templates. Knowledge transfer between the two markets strengthens project quality and speed. It positions the region as a strategic cluster for mainframe transformation in Asia Pacific.
Key Player Analysis:
- IBM
- Microsoft Corporation
- Wipro
- Kyndryl
- DXC Technology Company
- Avanade Inc.
- HCL Tech
- NTT Data Inc.
- Accenture
Competitive Analysis:
The competitive landscape of the Indonesia Mainframe Modernization Market reflects strong presence of global technology leaders and regional system integrators. Large vendors compete through deep mainframe expertise, cloud alliances, and end-to-end service portfolios. IBM, Microsoft, Accenture, and Kyndryl leverage platform depth and long enterprise relationships. Indian IT firms strengthen positions through cost-efficient delivery and domain knowledge. Competition centers on migration speed, risk control, and post-modernization support. It favors vendors with hybrid modernization frameworks and strong security credentials. Strategic partnerships and vertical-focused offerings shape differentiation across India and Indonesia.
Recent Developments:
- Avanade, the Microsoft-focused consulting and technology services joint venture between Accenture and Microsoft, announced a significant expansion into India on December 10, 2025, to capture the rising demand for Microsoft-powered artificial intelligence and cloud transformation services. This expansion reflects Avanade's strategic recognition that India represents a critical growth market for modern cloud and AI solutions, building on its existing capabilities in cloud application services and digital transformation. The expansion positions Avanade to serve Indian enterprises seeking to modernize legacy systems and accelerate their AI journey through Microsoft's technology stack and Accenture's implementation expertise.
- In India, IBM has made substantial investments in mainframe modernization capabilities throughout 2025. On August 13, 2025, IBM officially inaugurated its new India Client Experience Center in Mumbai, a strategic facility designed to support Indian enterprises' adoption of artificial intelligence, hybrid cloud, and quantum computing technologies. This expansion reflects IBM's long-term commitment to the Indian market and includes a Letter of Intent (LOI) with the Government of Maharashtra to explore opportunities for supporting the state's quantum computing initiatives, aligning with India's National Quantum Mission and the broader vision of a developed India (Viksit Bharat).
- Building on this momentum, IBM announced a significant strategic collaboration with BharatGen on September 17, 2025, to advance artificial intelligence adoption across India. This partnership leverages BharatGen's sovereign multimodal and Large Language Models (LLMs) tailored to India's unique linguistic and cultural landscape, combined with IBM's expertise in data governance and model training technology. The initiative focuses on developing AI models specifically suited for Indic domains and languages, with applications spanning education, agriculture, banking, healthcare, and citizen services sectors critical to India's digital transformation agenda.
- Most prominently, IBM announced a transformative partnership with Bharti Airtel on October 15, 2025, to augment the telecom giant's Airtel Cloud infrastructure. This strategic alliance combines Airtel's telco-grade reliability and data residency capabilities with IBM's cloud leadership and AI technologies designed specifically for mainframe workloads and regulated industries. Under this partnership, IBM's watsonx platform and Red Hat OpenShift AI will enable enterprises to scale AI workloads efficiently across hybrid cloud environments, including on-premise, multi-cloud, and edge deployments. Notably, the partnership includes expansion of Airtel's availability zones in India from four to ten, with two new Multizone Regions (MZRs) planned for Mumbai and Chennai, enhancing mainframe-like resilience for mission-critical applications.
- Wipro strengthened its global engineering services capabilities and artificial intelligence portfolio through a significant acquisition. On August 21, 2025, Wipro announced its intention to acquire the Digital Transformation Solutions (DTS) division of U.S. audio equipment manufacturer HARMAN for USD 375 million. This acquisition was completed on December 1, 2025, marking a transformative moment for the Indian technology company's global expansion. The acquisition brings over 5,600 employees from HARMAN's DTS segment across North America, Europe, and Asia into Wipro's fold, significantly expanding its product engineering and digital transformation services capabilities.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Modernization Approach, and Industry Vertical segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Enterprises will prioritize phased modernization to control risk and protect uptime.
- Hybrid architectures will remain central to core system strategies.
- Demand for managed modernization services will rise due to talent gaps.
- API enablement will gain focus to support digital channel expansion.
- Public sector modernization will accelerate under digital governance goals.
- Banking and insurance will sustain the highest project volumes.
- Vendors will invest in automation to shorten migration timelines.
- Cloud partnerships will shape vendor selection decisions.
- Regional delivery hubs will support cross-border execution models.
- Security and compliance readiness will guide long-term platform choices.=
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Indonesia Mainframe Modernization Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Indonesia Mainframe Modernization Market projected to grow between 2024 and 2032?
Which Indonesia Mainframe Modernization Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Indonesia Mainframe Modernization Market?
Who are the leading companies in the Indonesia Mainframe Modernization Market?
Which region commanded the largest share of the Indonesia Mainframe Modernization Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Indonesia Mainframe Modernization Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Indonesia Mainframe Modernization Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 230.28 million → 2032: USD 554.54 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Indonesia Mainframe Modernization Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Indonesia Mainframe Modernization Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Indonesia Mainframe Modernization Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 Indonesia Mainframe Modernization Drivers
- 3.3 Indonesia Mainframe Modernization Restraints & Challenges
- 3.4 Indonesia Mainframe Modernization Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Indonesia Mainframe Modernization Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Indonesia Mainframe Modernization Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Indonesia Mainframe Modernization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Indonesia Mainframe Modernization Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. Indonesia Mainframe Modernization Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to Indonesia Mainframe Modernization in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Indonesia Mainframe Modernization Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 Indonesia Mainframe Modernization Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Indonesia Mainframe Modernization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Indonesia Mainframe Modernization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Indonesia Mainframe Modernization
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Indonesia Mainframe Modernization – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Indonesia Mainframe Modernization – Priority Domestic Market 1
Chapter 10. Indonesia Mainframe Modernization – Priority Domestic Market 2
Chapter 11. Indonesia Mainframe Modernization – Priority Domestic Market 3
Chapter 12. Indonesia Mainframe Modernization – Priority Domestic Market 4
Chapter 13. Indonesia Mainframe Modernization Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
