
Cold Chain Market Overview:
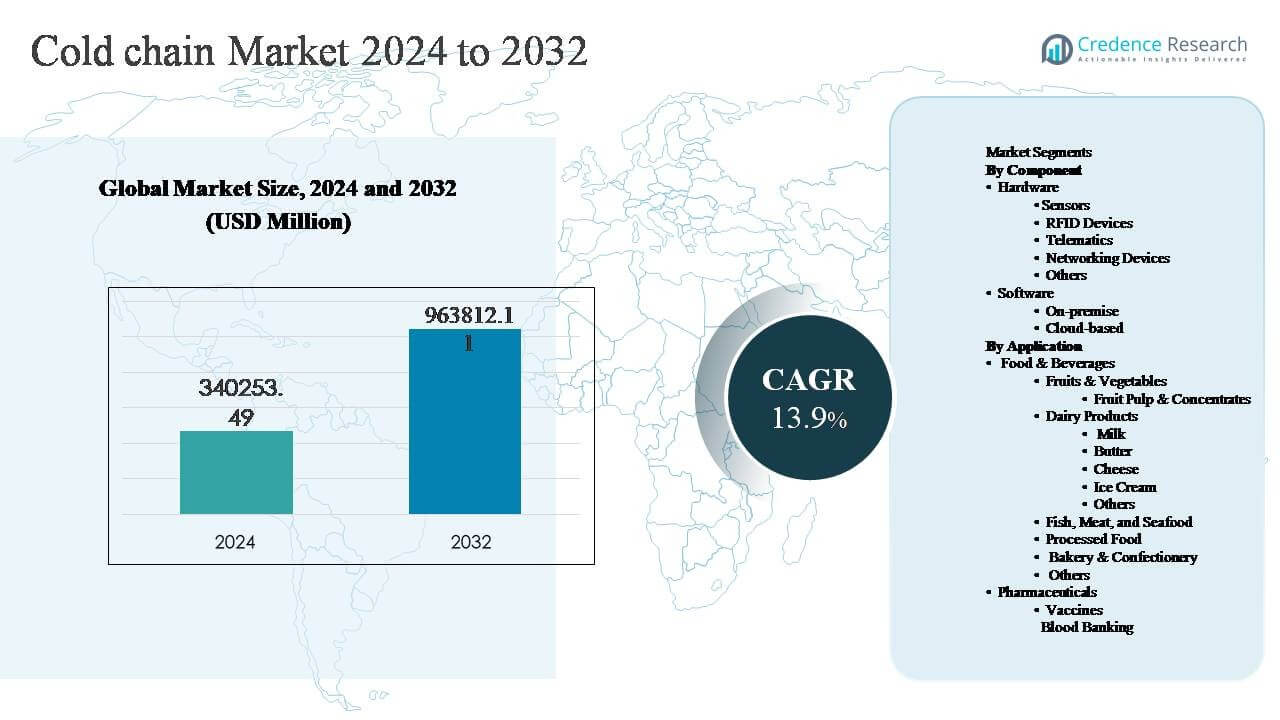
The global cold chain market was valued at USD 340,253.49 million in 2024 and is projected to reach USD 963,812.11 million by 2032, expanding at a compound annual growth rate (CAGR) of 13.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cold Chain Market Size 2024 | USD 340,253.49 million |
| Cold Chain Market , CAGR | 13.9% |
| Cold Chain Market Size 2032 | USD 963,812.11 million |
Cold Chain Market Insights
- Market growth is primarily driven by rising consumption of perishable foods, expansion of vaccine and biologics distribution, and stricter food safety and pharmaceutical compliance requirements, pushing logistics providers to invest in temperature-controlled storage, monitoring hardware, and end-to-end visibility solutions.
- Key market trends include rapid adoption of IoT-enabled sensors, RFID, and cloud-based monitoring platforms, alongside increasing focus on energy-efficient refrigeration and automation; hardware remains the dominant component segment, while food & beverages account for the largest application share.
- The competitive landscape features a mix of global technology providers and cold chain specialists competing on monitoring accuracy, infrastructure scale, compliance capabilities, and digital integration, with strategic investments in smart cold chain and capacity expansion shaping competition.
- Regionally, North America leads with ~35% market share, followed by Asia Pacific at ~30% and Europe at ~25%, while Latin America and the Middle East & Africa collectively account for the remaining share, supported by agricultural exports and healthcare logistics growth.
Cold Chain Market Segmentation Analysis:
By Component:
The cold chain market by component is led by hardware, which accounts for the dominant market share, driven by the essential role of physical monitoring and tracking infrastructure across temperature-sensitive logistics. Within hardware, sensors represent the leading sub-segment, supported by their widespread deployment for real-time temperature, humidity, and location monitoring across storage and transportation assets. Growth is driven by stricter food safety and pharmaceutical regulations, increasing adoption of IoT-enabled cold chain systems, and the need to minimize spoilage and compliance risks. Software adoption is expanding steadily, with cloud-based platforms gaining traction for scalability and centralized visibility.
- For instance, Sensitech Inc. deploys single-use and multi-use temperature loggers capable of recording data at intervals as short as 1 minute and operating across a calibrated range of -30 °C to +70 °C, supporting pharmaceutical and biologics shipments over multi-day transit cycles.
By Application:
By application, food & beverages constitute the dominant segment of the cold chain market, accounting for the largest share due to high volumes of perishable products requiring controlled storage and transport. Within this segment, dairy products particularly milk and ice cream form the leading sub-segment, driven by short shelf life, temperature sensitivity, and consistent daily consumption. Demand is reinforced by expanding organized retail, frozen food penetration, and export-oriented agri-food supply chains. The pharmaceutical segment follows, with vaccines and blood banking driving growth as governments and healthcare providers strengthen temperature-controlled medical logistics infrastructure.
- For instance, Nestlé operates refrigerated dairy logistics that maintain milk and fresh dairy products consistently between 2 °C and 6 °C from processing plants to retail distribution centers, while its ice cream supply chain relies on ultra-low freezers operating at -25 °C to preserve texture and product stability during transport.
Key Growth Drivers
Rising Demand for Perishable Food and Temperature-Sensitive Pharmaceuticals
The rapid growth in global consumption of perishable food products and temperature-sensitive pharmaceuticals is a primary driver of the cold chain market. Expanding urban populations, changing dietary habits, and rising demand for fresh fruits, vegetables, dairy products, seafood, and frozen foods are increasing the need for reliable cold storage and refrigerated transportation. Simultaneously, the pharmaceutical sector is witnessing sustained demand for cold chain solutions due to the widespread distribution of vaccines, biologics, insulin, and blood products that require strict temperature control. Governments and healthcare providers are strengthening immunization programs and emergency preparedness, further driving investments in pharmaceutical cold chains. These dynamics are pushing logistics providers, food processors, and healthcare distributors to expand cold chain capacity and improve temperature integrity across storage, handling, and last-mile delivery operations.
- For instance, Lineage Logistics operates large-scale refrigerated warehouses capable of maintaining chilled zones at 0 °C to 4 °C and frozen zones at –18 °C, supporting high-throughput handling of meat, seafood, and dairy products across thousands of pallet movements per day.
Stringent Regulatory Compliance and Food Safety Standards
Stricter food safety regulations and pharmaceutical compliance requirements are significantly accelerating cold chain adoption worldwide. Regulatory authorities mandate precise temperature monitoring, documentation, and traceability across the supply chain to prevent contamination, spoilage, and product recalls. Compliance with standards related to Hazard Analysis and Critical Control Points (HACCP), Good Distribution Practices (GDP), and Good Manufacturing Practices (GMP) has become essential for market participants. As enforcement intensifies, companies are investing in validated cold storage facilities, refrigerated fleets, and monitoring systems to ensure compliance and maintain market access. Regulatory pressure is particularly strong in export-driven food and pharmaceutical supply chains, where failure to meet temperature requirements can result in shipment rejections, financial losses, and reputational damage, making cold chain infrastructure a strategic necessity.
- For instance, United States Cold Storage operates GDP- and GMP-aligned warehouses with validated temperature zones maintained between 2 °C and 8 °C for pharmaceuticals and -18 °C for frozen foods, supported by redundant refrigeration and backup power systems designed to maintain temperature integrity during outages.
Expansion of Organized Retail and E-commerce Channels
The rapid expansion of organized retail formats and e-commerce platforms is driving sustained growth in cold chain logistics. Supermarkets, hypermarkets, and online grocery platforms require reliable refrigerated storage and transport to manage high volumes of fresh, frozen, and ready-to-eat products. Growth in home delivery of groceries, meal kits, and pharmaceutical products has increased the need for efficient last-mile cold chain solutions. Retailers are prioritizing inventory freshness, reduced wastage, and faster replenishment cycles, prompting investments in temperature-controlled warehouses and distribution centers. Additionally, pharmaceutical e-commerce and direct-to-patient delivery models are reinforcing demand for compliant cold chain systems that ensure product integrity from origin to end consumer.
Key Trends & Opportunities
Adoption of Digital Monitoring and Smart Cold Chain Solutions
The integration of digital technologies into cold chain operations is a key trend shaping the market. IoT-enabled sensors, RFID devices, telematics, and cloud-based monitoring platforms are enabling real-time visibility into temperature, location, and handling conditions. These technologies help operators reduce spoilage, improve compliance, and optimize logistics performance. Predictive analytics and automated alerts allow proactive intervention before temperature excursions occur, enhancing reliability. As digital solutions become more affordable and scalable, their adoption is expanding across food, beverage, and pharmaceutical cold chains, creating opportunities for technology providers and logistics operators to deliver value-added services.
- For instance, ORBCOMM equips refrigerated trailers and containers with telematics devices capable of capturing temperature data from multiple probes at intervals of under 5 minutes and transmitting this information via cellular and satellite networks across long-haul and intercontinental routes.
Growth of Cold Chain Infrastructure in Emerging Markets
Emerging economies present significant opportunities for cold chain expansion due to underdeveloped storage and transportation infrastructure. Rapid growth in food processing, pharmaceutical manufacturing, and agricultural exports is driving demand for modern cold storage facilities and refrigerated logistics networks. Governments and private investors are increasingly supporting infrastructure development to reduce post-harvest losses and improve supply chain efficiency. As income levels rise and consumption of frozen and processed foods increases, cold chain penetration is expected to deepen, offering long-term growth potential for market participants.
- For instance, Snowman Logistics operates large multi-temperature cold storage facilities across India, including sites with installed refrigeration capacities exceeding 20,000 pallet positions designed to maintain chilled ranges of 0 °C to 4 °C and frozen ranges of –18 °C, supporting processed foods, seafood, and pharmaceutical products.
Rising Focus on Sustainability and Energy-Efficient Cold Storage
Sustainability is emerging as a critical opportunity in the cold chain market. Operators are increasingly adopting energy-efficient refrigeration systems, natural refrigerants, and optimized warehouse designs to reduce operating costs and environmental impact. Demand for greener cold chain solutions is growing as companies align with environmental regulations and corporate sustainability goals. This trend is encouraging innovation in refrigeration technologies, insulation materials, and renewable energy integration, creating new opportunities for equipment manufacturers and service providers.
Key Challenges
High Capital and Operating Costs
The cold chain market faces significant challenges due to high capital investment and operating costs. Establishing temperature-controlled warehouses, refrigerated transport fleets, and monitoring systems requires substantial upfront expenditure. Operating costs, including energy consumption, maintenance, and skilled labor, further strain profitability. These cost pressures are particularly challenging for small and mid-sized players and for operators in price-sensitive markets. Fluctuating energy prices add uncertainty to cost management, making it difficult for companies to maintain margins while meeting service and compliance expectations.
Infrastructure Gaps and Operational Complexity
Inadequate infrastructure and operational complexity remain key challenges, especially in developing regions. Limited availability of reliable power supply, poor transportation networks, and fragmented logistics ecosystems can disrupt cold chain continuity. Managing temperature integrity across multiple handoffs, storage points, and transport modes increases the risk of product loss and compliance failures. Additionally, lack of standardized practices and trained personnel can compromise operational efficiency. Overcoming these challenges requires coordinated investment, process standardization, and workforce development across the cold chain ecosystem.
Regional Analysis
North America
North America dominates the global cold chain market, accounting for approximately 35% of total market share, driven by well-established cold storage infrastructure, advanced refrigerated transportation networks, and strict food and pharmaceutical safety regulations. The United States leads regional demand due to high consumption of frozen and processed foods, widespread vaccine distribution programs, and strong adoption of digital cold chain monitoring systems. Growth is further supported by expanding grocery e-commerce, organized retail penetration, and investments in automated, energy-efficient cold warehouses. Canada contributes steadily through agri-food exports and pharmaceutical logistics expansion.
Europe
Europe represents around 25% of the global cold chain market, supported by stringent regulatory frameworks governing food safety and pharmaceutical distribution. Countries such as Germany, France, the UK, and the Netherlands play a central role due to advanced logistics infrastructure and strong cross-border trade in perishable goods. Demand is driven by high consumption of dairy, meat, seafood, and frozen foods, along with robust pharmaceutical manufacturing and vaccine distribution activities. Sustainability initiatives and adoption of energy-efficient refrigeration technologies are shaping investments, while export-oriented food supply chains continue to reinforce cold chain capacity expansion.
Asia Pacific
Asia Pacific accounts for approximately 30% of the global cold chain market and is the fastest-growing regional segment. Rapid urbanization, rising disposable incomes, and changing dietary preferences are increasing demand for fresh, frozen, and processed foods. China and India are major growth engines, driven by expanding food processing industries, pharmaceutical manufacturing, and government-backed cold chain infrastructure initiatives. Growth is further supported by increasing agricultural exports, rising vaccine distribution, and rapid expansion of organized retail and e-commerce platforms. However, uneven infrastructure development across countries continues to influence regional performance.
Latin America
Latin America holds around 6% of the global cold chain market, supported by growth in agricultural exports, meat processing, and pharmaceutical distribution. Countries such as Brazil, Mexico, and Argentina are investing in cold storage and refrigerated logistics to reduce post-harvest losses and strengthen export competitiveness. Rising consumption of frozen foods and expansion of organized retail are driving demand for temperature-controlled storage and transport. While infrastructure gaps and high operating costs remain challenges, increasing private sector investment and regional trade activities are gradually improving cold chain penetration across the region.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4% of the global cold chain market, with growth driven by food imports, pharmaceutical distribution, and healthcare infrastructure development. Gulf Cooperation Council (GCC) countries lead regional adoption due to high reliance on imported perishables, strong cold storage investments, and expanding vaccine logistics. In Africa, demand is rising as governments and private players focus on reducing food spoilage and improving agricultural supply chains. Despite infrastructure limitations, ongoing investments in logistics hubs and cold warehouses support gradual market expansion.
Cold Chain Market Segmentations:
By Component
- Hardware
- Sensors
- RFID Devices
- Telematics
- Networking Devices
- Others
- Software
- On-premise
- Cloud-based
By Application
- Food & Beverages
- Fruits & Vegetables
- Fruit Pulp & Concentrates
- Dairy Products
- Milk
- Butter
- Cheese
- Ice Cream
- Others
- Fish, Meat, and Seafood
- Processed Food
- Bakery & Confectionery
- Others
- Fruits & Vegetables
- Pharmaceuticals
- Vaccines
- Blood Banking
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the global cold chain market is moderately fragmented, characterized by the presence of large integrated logistics providers, specialized cold storage operators, and regional players with strong local networks. Market participants compete primarily on infrastructure scale, geographic reach, service reliability, and compliance capabilities. Leading companies focus on expanding temperature-controlled warehouse capacity, strengthening refrigerated transportation fleets, and integrating digital monitoring technologies to enhance visibility and traceability. Strategic initiatives such as capacity expansions, mergers and acquisitions, long-term contracts with food processors and pharmaceutical companies, and investments in automation are common. Players are also prioritizing energy-efficient refrigeration systems and sustainable operations to reduce costs and meet regulatory and customer expectations. Regional players maintain competitiveness through proximity to production hubs and customized services, while global operators leverage end-to-end solutions and cross-border expertise to strengthen market positioning.
Key Player Analysis
- Daikin Industries Ltd.
- Emerson Electric Co.
- ORBCOMM Inc.
- Digi International Inc.
- Sensitech Inc.
- Berlinger & Co. AG
- Elpro-Buchs AG
- Controlant
- Monnit Corporation
- Zest Labs Inc.
Recent Developments
- In June 2025, Berlinger & Co. AG’s monitoring solutions business was formally integrated into Sensitech’s organizational structure, reflecting the consolidation of Berlinger’s temperature monitoring expertise under the Sensitech brand to deliver unified cold chain visibility solutions.
- In October 2024, Chillventa 2024 Participation: Daikin announced its participation at Chillventa 2024, one of the world’s premier refrigeration and cold chain trade events, where it showcased its latest cold chain technologies and refrigeration solutions for industrial and storage applications. The showcased portfolio included systems designed for broad temperature operation ranges, such as low- and medium-temperature refrigeration units capable of maintaining environments from -35 °C to +30 °C across warehouse and processing applications, reinforcing Daikin’s commitment to supporting global cold chain infrastructure improvements.
Report Coverage
The research report offers an in-depth analysis based on Component, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the cold chain market, and what is its projected size in 2032?
At what Compound Annual Growth Rate (CAGR) is the cold chain market projected to grow between 2025 and 2032?
Which cold chain segment held the largest share in 2024?
What are the primary factors fueling the growth of the cold chain market?
Who are the leading companies in the cold chain market?
Which region commanded the largest share of the cold chain market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 340,253.49 million → 2032: USD 963,812.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cold Chain Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cold Chain Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cold Chain Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cold Chain Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cold Chain Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cold Chain Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cold Chain Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cold Chain Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 340,253.49 million → 2032: USD 963,812.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cold Chain Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cold Chain Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cold Chain Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cold Chain Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

