
Completion Equipment Market Overview:
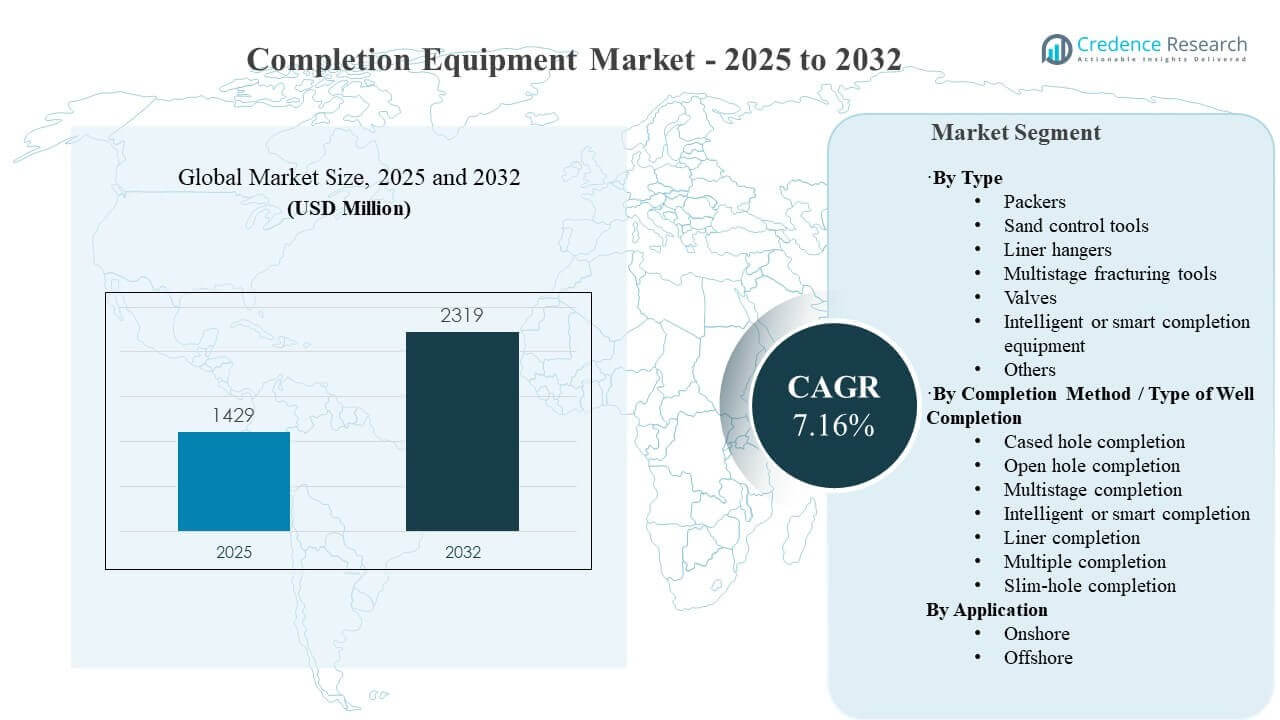
The global Completion Equipment Market size was estimated at USD 1,429 million in 2025 and is expected to reach USD 2,319 million by 2032, growing at a CAGR of 7.16% from 2025 to 2032. Rising horizontal drilling and higher completion intensity in unconventional reservoirs are driving recurring demand for multistage tools, packers, liner hangers, and flow-control components that improve well integrity and production efficiency. North America remains a major demand center, and offshore developments in select basins are increasing requirements for high-reliability completion hardware designed for complex operating conditions.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Completion Equipment Market Size 2025 | USD 1,429 million |
| Completion Equipment Market, CAGR | 7.16% |
| Completion Equipment Market Size 2032 | USD 2,319 million |
Key Market Trends & Insights
- The Completion Equipment Market is projected to expand from USD 1,429 million (2025) to USD 2,319 million (2032) at a 7.16% CAGR (2025–2032).
- North America accounted for 33.9% of market revenue in 2025, supported by sustained completion activity and high service intensity in prolific basins.
- Asia Pacific represented 25.7% of market revenue in 2025, reflecting continued upstream investment and steady demand for standardized and engineered completion systems.
- Onshore applications held 71.3% share in 2025, driven by higher well counts and repeat completion cycles versus offshore.
- Packers accounted for 29.6% share in 2025, supported by continued demand for zonal isolation and well integrity across conventional and unconventional completions.
Segment Analysis
Completion equipment demand tracks drilling and completion activity, but mix is increasingly shaped by well complexity, lateral lengths, and the need to control flow across multiple zones. Operators prioritize equipment that reduces nonproductive time, improves well integrity, and supports consistent production performance, which sustains baseline demand for packers, liner hangers, valves, and sand-control solutions. Procurement also favors providers that can bundle tools with engineering support, field execution, and inventory reliability, particularly in fast-cycle onshore programs.
Technology adoption is moving toward higher-performance materials, tighter tolerances, and more integrated assemblies that simplify installation and reduce failure risk. Intelligent or smart completion equipment is gaining attention where producers need greater control of production profiles, better water or gas management, and improved intervention planning. Offshore developments reinforce demand for premium-rated components designed for harsh environments, longer run lives, and enhanced safety performance, which supports higher-value completion packages.
By Type Insights
Packers accounted for the largest share of 29.6% in 2025. Zonal isolation remains a foundational requirement across most completion designs, supporting steady demand regardless of well type or basin. Increasing multistage completion intensity reinforces the need for reliable isolation and pressure containment to improve stimulation efficiency and production outcomes. Growth in complex wells also increases the preference for premium-rated packers that reduce operational risk and help maintain well integrity over longer production cycles.
By Completion Method / Type of Well Completion Insights
Cased hole completion accounted for the largest share of 46.2% in 2025. Cased-hole architectures support stronger well control and integrity in a wide range of reservoir conditions, which aligns with operator priorities around safety and predictable execution. Cased-hole designs also enable flexible perforation and stimulation strategies, supporting repeatable workflows in high-volume development programs. The completion-method mix is further influenced by interventions and recompletions, which often favor cased-hole approaches for controllability and long-term maintenance.
By Application Insights
Onshore accounted for the largest share of 71.3% in 2025. High well counts and repeat completion cycles in onshore programs sustain consistent demand for standardized completion packages and fast-turn tool availability. Operators often prioritize equipment reliability, shorter installation time, and supply assurance to keep pace with high-frequency operations. Offshore remains strategically important due to engineered hardware requirements and higher-value packages, but onshore volume continues to anchor market demand.
Completion Equipment Market Drivers
Rising Horizontal Drilling and Completion Intensity
Longer laterals and higher stage counts increase demand for multistage fracturing tools, packers, liner hangers, and valves. Operators seek repeatable completion designs that improve stimulation efficiency and production outcomes. Higher completion intensity also increases wear and replacement cycles for critical components, supporting recurring demand. Standardization across development programs encourages broader adoption of proven equipment families. Supply reliability and field support remain decisive for sustaining high-rate completion schedules.
Growth in Complex and High-Value Offshore Developments
Offshore and deepwater projects require premium completion systems engineered for long run life and harsh operating conditions. These wells use higher-spec hardware to reduce failure risk, protect well integrity, and support safe operations. Project execution also favors integrated packages that reduce interfaces and improve accountability across tool delivery and installation support. Longer-cycle developments create stable demand visibility for vendors with qualified portfolios. Equipment validation and reliability performance are major differentiators in offshore awards.
- For instance, Baker Hughes said its PrimeStar HD system enabled the world’s first 20,000-psi completion in the Gulf of Mexico across six zones in a single trip, handling 31,500 bbl of base fluid and about 3 million lb of proppant while keeping maximum surface treating pressure below 12,000 psi.
Mature-Field Optimization and Recompletion Activity
Mature basins generate sustained demand for recompletions and workovers focused on restoring production and managing water or sand ingress. These programs require packers, sand-control tools, valves, and selective isolation solutions to address evolving reservoir conditions. Recompletion strategies often target improved inflow distribution, reduced downtime, and lower unit operating costs. Operators value equipment that simplifies installation and minimizes intervention frequency. The need to extend asset life supports steady replacement and upgrade demand.
- For instance, SLB reported that a targeted recompletion program in onshore Nigeria used cement packers and PowerJet Nova shaped charges to unlock approximately 1,000 bbl/d of additional oil from shallower bypassed zones, highlighting the value of precise recompletion hardware in extending mature-asset life.
Technology Upgrades Toward Smart and Integrated Systems
Increasing focus on production optimization is expanding demand for intelligent or smart completion equipment and integrated hardware configurations. Producers aim to manage production profiles and reduce intervention requirements through better flow control and monitoring-enabled designs. Integration also reduces installation complexity and improves reliability by limiting connections and interfaces. As digital workflows mature, equipment is increasingly selected based on its ability to support data-driven decision-making. Vendors that combine engineering support with reliable tool performance gain adoption momentum.
Completion Equipment Market Challenges
Market demand is sensitive to upstream investment cycles, and shifts in commodity pricing can delay projects or reduce near-term completion activity. Qualification requirements for harsh environments increase development timelines and raise costs for premium-rated completion hardware. Supply-chain constraints, long lead times for specialized components, and logistics disruptions can create scheduling risk, particularly in high-frequency onshore programs. Execution complexity also elevates the cost of tool failures, increasing performance expectations and warranty exposure.
Equipment selection is influenced by basin-specific conditions, and vendors must maintain broad portfolios to address varying pressure, temperature, and fluid challenges. Standardization pressures can compress pricing for common components, raising competitive intensity in high-volume segments. Regulatory and safety requirements increase documentation and testing needs, adding overhead for both manufacturers and service providers. Localization expectations in certain markets can require regional manufacturing or partnerships, increasing operational complexity for global suppliers.
- For instance, Baker Hughes states that its Hammerhead ultradeepwater completion and production system is designed for well depths up to 33,000 ft, water depths up to 10,000 ft, temperatures up to 300°F, and pressures up to 25,000 psi, while its multi-zone frac-pack lower completion can place up to 5 million lb of proppant at 50 barrels per minute across as many as five zones, demonstrating the need for basin-specific engineering breadth.
Market Trends and Opportunities
Integrated completion packages are gaining traction as operators seek fewer interfaces, faster execution, and improved accountability across tool delivery and installation support. Standardized tool families that can be configured for multiple basins are favored in high-volume programs, creating opportunity for vendors with scalable manufacturing and dependable inventory models. Growth in engineered offshore projects supports demand for high-reliability valves, premium packers, and specialized sand-control systems that can command higher value per well.
- For instance, Halliburton’s XSTMZ single-trip multizone completion system is rated to 15,000 psi, supports stimulation rates up to 45 BPM with 3,750,000 lb of proppant, integrates with a 15K SmartWell system, and was used in an ultra-deepwater four-zone installation at depths of more than 30,000 ft.
Adoption of intelligent or smart completion equipment is increasing where producers need better production control and improved lifecycle economics. Opportunities are expanding for equipment that supports remote operations, lower intervention frequency, and improved production management across multiple zones. Vendors that strengthen engineering services, field execution support, and performance assurance can capture share as operators prioritize reliability and minimized nonproductive time. Aftermarket and replacement demand remains attractive in mature basins with sustained intervention activity.
Regional Insights
North America
North America held 33.9% share in 2025, supported by high completion intensity and repeat development cycles in major producing basins. Operator focus on cycle time, reliability, and standardized completion designs sustains demand for packers, liner hangers, multistage tools, and valves. Procurement emphasizes supply assurance and field execution capability to keep pace with high-frequency operations. Competitive differentiation often centers on tool performance consistency, installation efficiency, and the ability to support large-scale programs.
Europe
Europe accounted for 21.4% share in 2025, with demand shaped by offshore activity, mature-field optimization, and well integrity priorities. Engineered completion systems are important in offshore environments where reliability requirements are elevated and failures carry high cost exposure. Mature assets drive demand for recompletions and sand-control solutions to sustain output and manage declining reservoir performance. Vendor selection favors strong engineering support, proven reliability, and compliance with stringent safety and operating standards.
Asia Pacific
Asia Pacific represented 25.7% share in 2025, reflecting broad upstream investment and a mix of onshore and offshore developments. Demand is supported by steady requirements for core completion hardware and basin-specific engineered solutions for more complex projects. Operators increasingly value standardization where possible, alongside localized support and dependable supply. Growth opportunities exist in upgrading completion designs to improve production performance and reduce intervention frequency, especially in maturing fields and offshore developments.
Latin America
Latin America captured 10.8% share in 2025, driven by a combination of offshore developments and selective onshore activity. Deepwater projects in the region typically require high-spec completion packages that prioritize reliability and long run life. Project-based procurement can be concentrated by country and operator, creating volatility but also sizable contract opportunities for qualified vendors. Strong field execution support, quality assurance, and robust logistics capability are important for sustained participation in large developments.
Middle East & Africa
Middle East & Africa accounted for 8.2% share in 2025, supported by large conventional reserves, redevelopment programs, and production optimization priorities. Demand centers on reliable, scalable completion hardware that supports consistent execution across large well inventories. Mature-field work and water management needs sustain requirements for zonal isolation and flow-control components. Vendor competitiveness depends on operational scale, local support, and the ability to deliver consistent tool performance under high utilization.
Competitive Landscape
Competition is driven by reliability, breadth of completion portfolios, engineering capability, and the ability to deliver tools at scale with consistent performance. Vendors differentiate through integrated packages, basin-specific customization, and field execution support that reduces nonproductive time. Strong manufacturing, quality systems, and supply assurance are decisive in high-volume programs, while premium engineering and qualification capabilities matter more in offshore and harsh-environment applications. Commercial strategies increasingly emphasize long-term contracts, bundled offerings, and lifecycle service support.
SLB competes through integrated completion systems supported by engineering services and field execution capability across onshore and offshore environments. The company’s positioning benefits from broad tool coverage spanning packers, valves, liner systems, sand-control solutions, and intelligent completion architectures. SLB’s approach aligns with operator preferences for fewer interfaces, predictable execution, and consistent performance across large well programs. The company’s global footprint supports supply assurance and localized support, which are important for both fast-cycle and complex projects.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- SLB
- Halliburton
- Baker Hughes
- Weatherford International
- NOV
- Superior Energy Services
- Forum Energy Technologies
- Nine Energy Service
- NCS Multistage Holdings
- RPC
- Hilong Oil Service & Engineering
- SPT Energy Group
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Halliburton and Singapore’s ASTAR launched NEX Lab, a S$35 million joint lab focused on accelerating the development and commercialization of advanced well completion technologies. The company said the partnership combines Halliburton’s well completions expertise with ASTAR’s research capabilities to support innovation across completion technologies, including lower-carbon applications.
- In October 2025, Halliburton announced the launch of the Turing electro-hydraulic control system, described as the next generation of SmartWell intelligent completions technology. Halliburton said the new system improves zonal optimization through integrated position sensors and is designed to reduce rig time, lower operational risk, and improve well performance across completion applications.
- In September 2025, SLB announced that it had been awarded a major completions contract by Petrobras to provide services and technology for up to 35 ultra-deepwater wells in Brazil’s Santos Basin. SLB said the project will use advanced electric completions technologies and digital solutions, including Electris high-flow-rate interval control valves, to improve real-time production intelligence and reservoir management.
- In March 2025, Baker Hughes announced a major multi-year fully integrated completions systems contract with Petrobras for offshore deepwater fields in Brazil. The company said the award will use its completions technology portfolio to support remote operations, enable real-time response to changing well conditions, and optimize production across multiple deepwater fields, with delivery beginning in late 2025.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1,429 million |
| Revenue forecast in 2032 | USD 2,319 million |
| Growth rate (CAGR) | 7.16% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Type; By Completion Method / Type of Well Completion; By Application |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | SLB; Halliburton; Baker Hughes; Weatherford International; NOV; Superior Energy Services; Forum Energy Technologies; Nine Energy Service; NCS Multistage Holdings; RPC; Hilong Oil Service & Engineering; SPT Energy Group |
| No. of Pages | 328 |
Segmentation
By Type
- Packers
- Sand control tools
- Liner hangers
- Multistage fracturing tools
- Valves
- Intelligent or smart completion equipment
- Others
By Completion Method / Type of Well Completion
- Cased hole completion
- Open hole completion
- Multistage completion
- Intelligent or smart completion
- Liner completion
- Multiple completion
- Slim-hole completion
By Application
- Onshore
- Offshore
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Completion Equipment Market and what is the forecast value?
What is the CAGR for the Completion Equipment Market during 2025–2032?
What is the largest segment in the Completion Equipment Market?
What factors are driving growth in the Completion Equipment Market?
Who are the leading companies in the Completion Equipment Market?
Which region leads the Completion Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Completion Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Completion Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 1,429 million → 2032: USD 2,319 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Completion Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Completion Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Completion Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Completion Equipment Market Drivers
- 3.3 Completion Equipment Market Restraints & Challenges
- 3.4 Completion Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Completion Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Completion Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Completion Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Completion Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Completion Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Completion Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Completion Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Completion Equipment Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Completion Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Completion Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Completion Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Completion Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Completion Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Completion Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Completion Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Completion Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Completion Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Completion Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Completion Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
