
Gasoline Direct Injection (GDI) Device Market Overview:
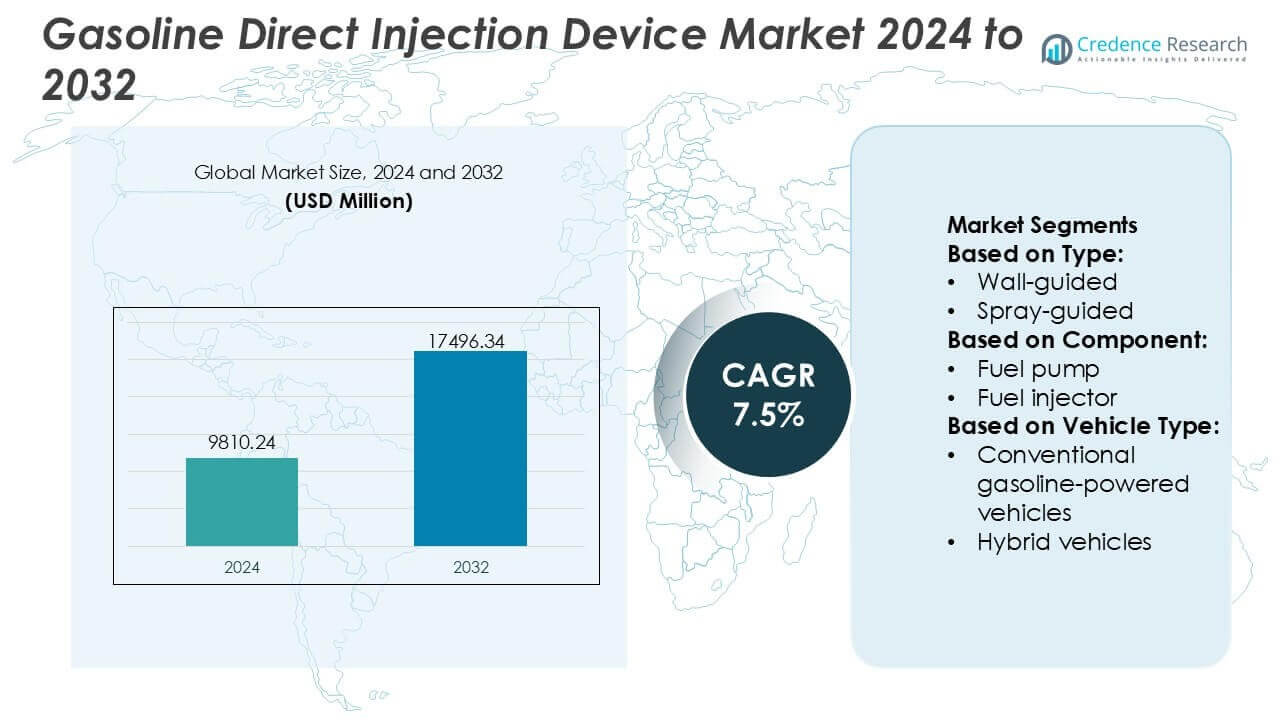
Gasoline Direct Injection Device Market size was valued USD 9810.24 million in 2024 and is anticipated to reach USD 17496.34 million by 2032, at a CAGR of 7.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Gasoline Direct Injection (GDI) Device Market Size 2024 | USD 9810.24 million |
| Gasoline Direct Injection (GDI) Device Market, CAGR | 7.5% |
| Gasoline Direct Injection (GDI) Device Market Size 2032 | USD 17496.34 million |
Gasoline Direct Injection (GDI) Device Market Insights
- Market growth is primarily driven by stricter emission regulations and rising demand for fuel-efficient, high-performance engines, with high-pressure fuel injectors emerging as the dominant segment due to their role in precise fuel atomization and combustion control.
- Key market trends include increased integration of advanced electronic control units, higher injection pressures, and compatibility with turbocharged and downsized engines to balance efficiency and power output.
- The competitive landscape is defined by global suppliers focusing on R&D, OEM partnerships, and scalable manufacturing, while cost pressures and system complexity act as notable restraints, especially in price-sensitive vehicle segments.
- Regionally, Asia-Pacific leads with an exact 34% market share, supported by high vehicle production volumes, followed by Europe and North America, while emerging regions show gradual adoption driven by evolving emission norms.
Gasoline Direct Injection (GDI) Device Market Segmentation Analysis:
By Type
Within the Gasoline Direct Injection (GDI) device market, spray-guided systems dominate with an estimated 55% market share, driven by superior fuel atomization and precise in-cylinder combustion control. Spray-guided architectures place the injector centrally, enabling higher compression ratios, improved thermal efficiency, and reduced knock propensity key requirements for downsized, turbocharged gasoline engines. Automakers increasingly adopt this configuration to meet stringent emission norms while preserving performance. Wall-guided systems retain relevance in cost-sensitive applications, but their comparatively higher particulate formation limits adoption in next generation engines, reinforcing spray-guided systems as the preferred choice.
- For instance, Infineon Technologies supplies automotive-grade GDI control ICs capable of driving piezo and solenoid injectors at injection pressures up to 350 bar, with microsecond-level switching times below 5 µs and operating junction temperatures rated to 150 °C, enabling the precise multi-pulse injection strategies required for spray-guided combustion systems.
By Component
Among components, fuel injectors represent the dominant sub-segment, accounting for approximately 34% market share, supported by their critical role in determining spray pattern, penetration, and injection pressure. Advances toward multi-hole injectors operating above 350 bar enable finer atomization and more complete combustion, directly improving fuel efficiency and emissions compliance. High-pressure fuel pumps follow closely, as elevated injection pressures are central to modern GDI performance. Electronic control units gain importance through advanced calibration algorithms, yet injectors remain the primary value driver due to precision engineering requirements and frequent technology upgrades.
- For instance, Keihin has developed multi-hole GDI fuel injectors validated for continuous operation at injection pressures up to 350 bar, incorporating solenoid actuation with response times below 0.4 milliseconds and needle control tolerances measured in single-digit micrometers, enabling highly repeatable multi-pulse injection strategies required in modern high-efficiency gasoline engines.
By Vehicle Type
Conventional gasoline-powered vehicles lead the market with nearly 68% share, reflecting their large global production base and continued optimization under tightening emission regulations. Automakers rely on GDI systems to extract higher efficiency from internal combustion platforms through downsizing and turbocharging. Hybrid vehicles exhibit faster adoption rates, leveraging GDI to optimize engine operation within hybrid powertrains and improve real-world fuel economy. However, higher penetration of conventional gasoline vehicles, particularly in emerging markets, sustains their dominance, ensuring consistent demand for GDI devices across mass-market passenger car segments.
Key Growth Drivers
Stringent Emission Regulations and Fuel Efficiency Mandates
Tightening global emission norms and fuel-efficiency standards remain a primary growth driver for gasoline direct injection (GDI) devices. Regulators increasingly mandate lower CO₂ and particulate emissions while maintaining engine performance, pushing automakers to adopt advanced fuel-delivery technologies. GDI systems enable precise fuel metering, improved combustion efficiency, and better thermal control compared to port fuel injection. These capabilities help manufacturers meet regulatory thresholds without sacrificing power output, making GDI devices integral to compliance strategies across passenger cars and light commercial vehicles.
- For instance, Marelli Holdings Co., Ltd. has engineered advanced GDI injector and control system solutions capable of supporting injection pressures up to 350 bar, with injector opening and closing response times below 0.3 milliseconds and fuel dosing accuracy controlled within a few milligrams per stroke, enabling stable multi-pulse injection events that directly support lower particulate formation and improved combustion efficiency under stringent emission test cycles.
Rising Demand for High-Performance and Downsized Engines
Growing consumer preference for responsive, high-performance vehicles supports wider adoption of GDI devices. Automakers increasingly combine engine downsizing with turbocharging to balance performance and efficiency. GDI systems play a critical role by delivering fuel at high pressure directly into the combustion chamber, improving torque delivery and throttle response. This configuration allows smaller engines to achieve power levels comparable to larger displacement engines, aligning with market demand for sporty driving dynamics alongside improved fuel economy.
- For instance, Stanadyne Holdings has developed high-pressure GDI fuel pump and injector technologies designed to operate at pressures up to 350 bar, with pump plunger durability validated beyond 300 million cycles and injector flow-rate consistency maintained within milligram-level precision per injection event, supporting stable high-load operation in turbocharged, downsized gasoline engines.
Expansion of Hybrid and Advanced Powertrain Architectures
The expanding penetration of hybrid vehicles significantly contributes to GDI device demand. Hybrid powertrains require highly efficient internal combustion engines that operate seamlessly with electric components under variable load conditions. GDI technology enhances cold-start efficiency, transient response, and combustion stability key requirements in hybrid systems. As automakers invest in advanced gasoline-electric architectures to bridge the transition toward electrification, GDI devices remain a core component supporting optimized engine performance and lower overall emissions.
Key Trends & Opportunities
Integration of High-Pressure and Multi-Hole Injector Technologies
Manufacturers increasingly adopt high-pressure fuel systems and advanced multi-hole injector designs to improve atomization and combustion control. These innovations reduce fuel droplet size, enhance air-fuel mixing, and lower particulate emissions. The trend creates opportunities for component suppliers to develop next-generation injectors, pumps, and rails capable of operating at higher pressures while maintaining durability and precision, especially for turbocharged and high-output gasoline engines.
- For instance, Continental AG has developed gasoline direct injection systems supporting rail pressures up to 350 bar, with multi-hole injectors featuring laser-drilled orifices below 100 micrometers in diameter and solenoid actuation response times under 0.2 milliseconds, enabling highly repeatable multi-injection events and stable combustion control across wide engine speed and load ranges.
Digital Engine Management and Smart Control Systems
The integration of advanced electronic control units and sensor-driven engine management systems represents a key opportunity in the GDI device market. Real-time data processing enables adaptive fuel injection timing, pressure modulation, and diagnostics, improving efficiency across varying driving conditions. As vehicles become increasingly software-defined, demand grows for GDI systems compatible with connected, predictive, and AI-assisted powertrain control platforms.
- For instance, GP Performance develops performance-oriented engine control solutions capable of processing crankshaft and camshaft sensor inputs at sampling rates above 1 kHz, supporting injector pulse-width control with timing resolution down to 0.1 milliseconds and real-time correction algorithms that execute within control loop latencies below 2 milliseconds, enabling precise fuel delivery and responsive combustion management in advanced GDI-enabled engines.
Growth in Emerging Automotive Markets
Rapid vehicle production growth in emerging economies presents long-term opportunities for GDI device adoption. Rising disposable incomes, urbanization, and stricter regional emission standards encourage automakers to introduce advanced gasoline technologies in cost-sensitive markets. This trend supports localized manufacturing, platform-specific GDI configurations, and scalable system designs tailored to regional fuel quality and regulatory requirements.
Key Challenges
Particulate Emissions and Carbon Deposit Formation
Despite efficiency advantages, GDI engines face challenges related to particulate emissions and carbon buildup on intake valves. Direct fuel injection bypasses intake valve washing, increasing deposit formation over time and potentially impacting engine performance. Meeting particulate emission limits often requires additional components such as gasoline particulate filters, raising system complexity and cost. Addressing these issues demands continuous innovation in injector design, combustion strategies, and aftertreatment integration.
Higher System Cost and Engineering Complexity
GDI devices involve higher manufacturing costs and technical complexity compared to conventional fuel-injection systems. High-pressure pumps, precision injectors, and advanced electronic controls increase component costs and require stringent quality standards. For cost-sensitive vehicle segments, balancing performance benefits with affordability remains challenging. Automakers and suppliers must optimize system design, manufacturing efficiency, and supply chains to sustain adoption across a broad range of vehicle platforms.
Regional Analysis
North America
North America represents a mature and technology-driven market for gasoline direct injection (GDI) devices, accounting for an estimated 31% market share. Stringent emission regulations, strong consumer demand for high-performance vehicles, and widespread adoption of turbocharged gasoline engines continue to support GDI penetration. Automakers across the U.S. and Canada emphasize fuel efficiency improvements without compromising power, accelerating the integration of advanced injectors, fuel pumps, and electronic control units. The region also benefits from strong R&D activity and early adoption of hybrid gasoline platforms, sustaining steady demand for next-generation GDI systems.
Europe
Europe holds approximately 27% market share in the global GDI device market, driven primarily by strict CO₂ and emission regulations across major automotive economies. Downsized engines paired with turbocharging are widely adopted, making GDI systems a standard configuration in passenger vehicles. Automakers focus on optimizing combustion efficiency and meeting Euro emission standards, increasing demand for high-precision injectors and high-pressure fuel rails. The region’s strong presence of premium and performance vehicle manufacturers further supports the adoption of advanced GDI technologies across multiple vehicle segments.
Asia-Pacific
Asia-Pacific dominates the gasoline direct injection device market with an estimated 34% market share, supported by high vehicle production volumes and expanding automotive manufacturing bases. Rapid urbanization, rising disposable incomes, and tightening emission norms in countries such as China, Japan, South Korea, and India accelerate GDI adoption. Automakers increasingly deploy GDI systems in both mass-market and mid-range vehicles to balance cost, efficiency, and performance. Localized manufacturing, coupled with strong demand for compact and fuel-efficient cars, positions Asia-Pacific as the fastest-growing regional market.
Latin America
Latin America accounts for roughly 5% market share in the GDI device market, reflecting gradual adoption of advanced gasoline technologies. Improving emission regulations, expanding middle-class vehicle ownership, and modernization of automotive platforms support regional growth. Automakers increasingly introduce GDI-equipped vehicles in Brazil, Mexico, and Argentina to enhance fuel efficiency and comply with evolving standards. However, cost sensitivity and fuel quality variability limit rapid penetration, encouraging suppliers to offer optimized and durable GDI solutions tailored to regional operating conditions.
Middle East & Africa
The Middle East & Africa region holds an estimated 3% market share, characterized by selective adoption of gasoline direct injection devices. Demand is supported by growing passenger vehicle sales, particularly in urban centers and Gulf countries. While emission regulations are comparatively less stringent in parts of the region, rising fuel efficiency awareness and gradual regulatory alignment encourage GDI integration. Market growth remains moderate due to lower vehicle production volumes, but increasing imports of advanced gasoline-powered vehicles sustain steady demand for GDI components.
Gasoline Direct Injection (GDI) Device Market Segmentations:
By Type:
- Wall-guided
- Spray-guided
By Component:
- Fuel pump
- Fuel injector
By Vehicle Type:
- Conventional gasoline-powered vehicles
- Hybrid vehicles
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the gasoline direct injection (GDI) device market players such as Infineon Technologies, Keihin, Marelli Holdings Co., Ltd., Stanadyne Holdings, Continental AG, GP Performance, Denso, Hitachi Astemo, Ltd., Robert Bosch GmbH, Delphi Technologies. the gasoline direct injection (GDI) device market is shaped by intense technological competition, strong OEM partnerships, and continuous investment in fuel delivery innovation. Market participants focus on developing high-pressure injectors, precision fuel pumps, and advanced electronic control systems to improve combustion efficiency and meet tightening emission standards. Differentiation increasingly depends on system reliability, miniaturization, and the ability to integrate seamlessly with turbocharged and hybrid gasoline powertrains. Companies also compete on manufacturing scale, cost optimization, and global supply capabilities to support high-volume vehicle platforms. Ongoing advancements in materials, injector spray control, and digital engine management strengthen competitive positioning, while aftermarket support and long-term supply agreements play a critical role in sustaining market presence.
Key Player Analysis
- Infineon Technologies
- Keihin
- Marelli Holdings Co., Ltd.
- Stanadyne Holdings
- Continental AG
- GP Performance
- Denso
- Hitachi Astemo, Ltd.
- Robert Bosch GmbH
- Delphi Technologies.
Recent Developments
- In April 2025, Kia unveiled a new 2.5-liter turbocharged T-GDI engine designed for both traditional internal combustion engine (ICE) and hybrid applications. This modular, high-efficiency engine aims for a 5% gain in thermal efficiency and a 12% increase in power compared to the existing 2.5L turbo engine.
- In February 2025, BorgWarner announced contract extensions with a major North American automaker for their wastegate turbochargers on midsized gasoline engines, covering SUVs and trucks through 2028 and beyond, featuring electrically actuated systems for better efficiency, reflecting a continued strong partnership and focus on combustion tech alongside hybrid solutions.
- In January 2024, Standard Motor Products, Inc. (SMP) launched a major expansion of its Fuel Injection Program, adding over 1,100 new, all-new GDI, MFI, and TBI injectors and multi-packs for comprehensive repair solutions, boosting their aftermarket offerings with more GDI coverage and complete repair kits for import and domestic vehicles, including related components like high-pressure pumps and fuel lines.
Report Coverage
The research report offers an in-depth analysis based on Type, Component, Vehicle Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of advanced gasoline direct injection systems will expand as automakers prioritize higher combustion efficiency and lower tailpipe emissions.
- Integration of higher-pressure fuel injection and improved injector spray patterns will enhance engine performance and fuel atomization.
- Demand for GDI devices will remain strong in turbocharged and downsized gasoline engines across passenger and light commercial vehicles.
- Hybrid powertrain growth will support continued use of GDI technology to optimize engine operation under variable load conditions.
- Increased use of electronic control units and software-driven calibration will improve real-time fuel management and diagnostics.
- Manufacturers will focus on reducing particulate emissions through improved combustion strategies and system-level optimization.
- Localization of GDI component manufacturing will increase to support regional automotive production and cost efficiency.
- Advancements in materials and coatings will improve injector durability and resistance to carbon deposit formation.
- Compatibility with evolving emission regulations will remain a key design priority for future GDI systems.
- Strategic collaborations between automakers and component suppliers will accelerate innovation and platform-specific GDI solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Gasoline Direct Injection Device Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Gasoline Direct Injection Device Market projected to grow between 2024 and 2032?
Which Gasoline Direct Injection Device Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Gasoline Direct Injection Device Market?
Who are the leading companies in the Gasoline Direct Injection Device Market?
Which region commanded the largest share of the Gasoline Direct Injection Device Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Gasoline Direct Injection (GDI) Device Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Gasoline Direct Injection (GDI) Device Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9810.24 million → 2032: USD 17496.34 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Gasoline Direct Injection (GDI) Device Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Gasoline Direct Injection (GDI) Device Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Gasoline Direct Injection (GDI) Device Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Gasoline Direct Injection (GDI) Device Market Drivers
- 3.3 Gasoline Direct Injection (GDI) Device Market Restraints & Challenges
- 3.4 Gasoline Direct Injection (GDI) Device Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Gasoline Direct Injection (GDI) Device Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Gasoline Direct Injection (GDI) Device Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Gasoline Direct Injection (GDI) Device category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Gasoline Direct Injection (GDI) Device Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Gasoline Direct Injection (GDI) Device Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Gasoline Direct Injection (GDI) Device. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Gasoline Direct Injection (GDI) Device Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Gasoline Direct Injection (GDI) Device Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Gasoline Direct Injection (GDI) Device Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Gasoline Direct Injection (GDI) Device (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Gasoline Direct Injection (GDI) Device
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Gasoline Direct Injection (GDI) Device Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Gasoline Direct Injection (GDI) Device Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Gasoline Direct Injection (GDI) Device Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Gasoline Direct Injection (GDI) Device Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Gasoline Direct Injection (GDI) Device Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Gasoline Direct Injection (GDI) Device Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Gasoline Direct Injection (GDI) Device Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Gasoline Direct Injection (GDI) Device Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
