
Market Overview
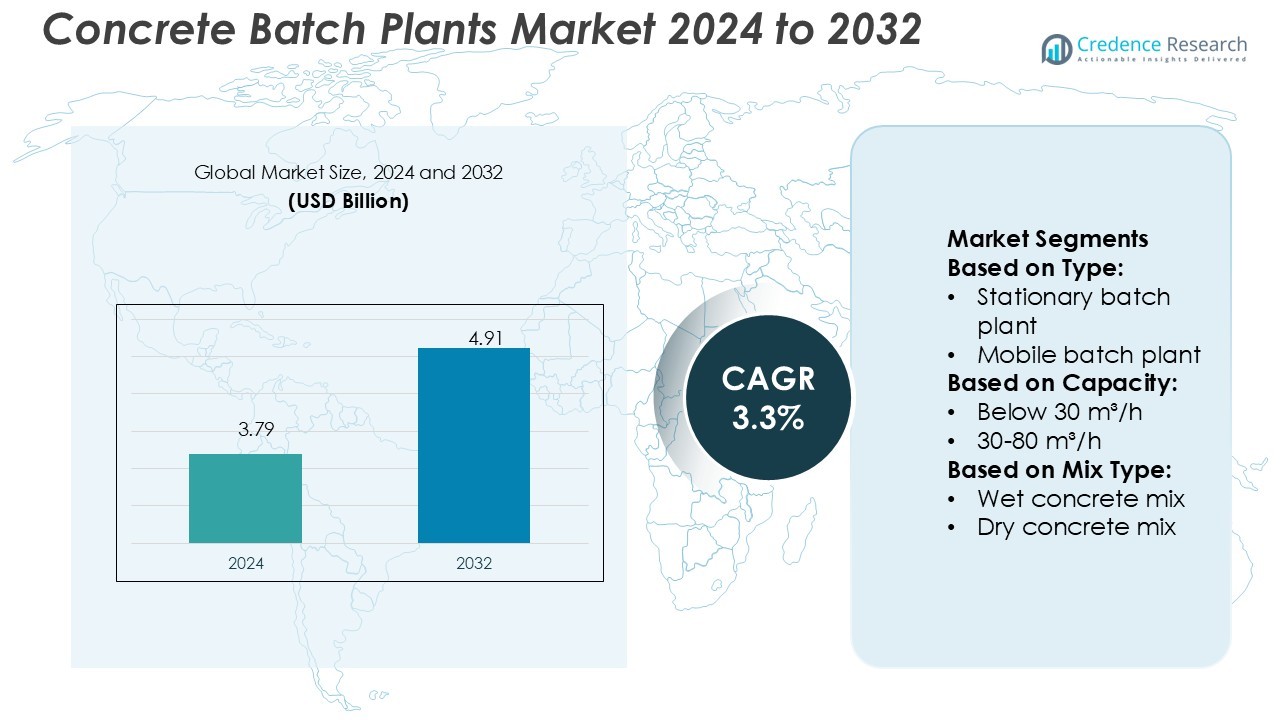
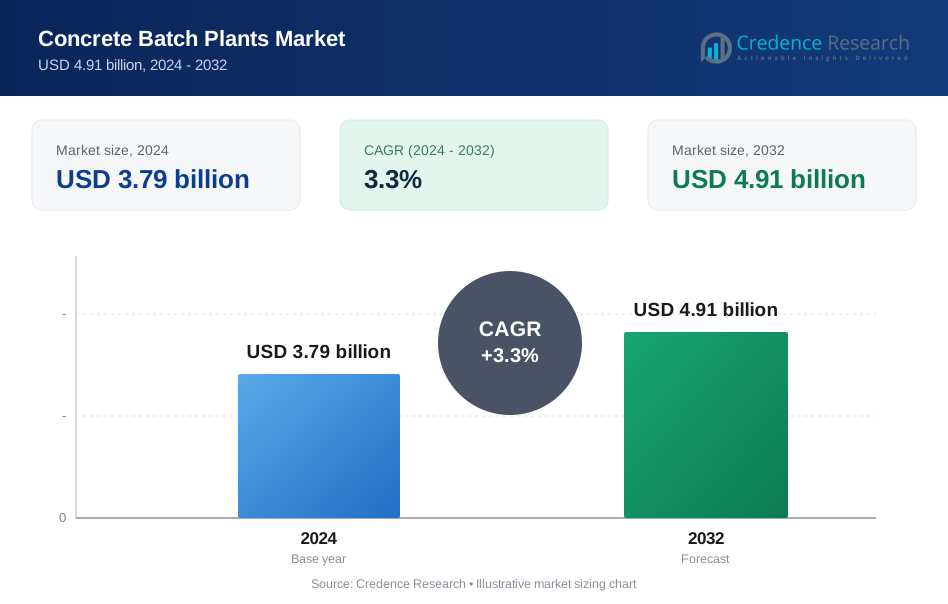
Concrete Batch Plants Market size was valued USD 3.79 billion in 2024 and is anticipated to reach USD 4.91 billion by 2032, at a CAGR of 3.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Concrete Batch Plants Market Size 2024 | USD 3.79 Billion |
| Concrete Batch Plants Market, CAGR | 3.3% |
| Concrete Batch Plants Market Size 2032 | USD 4.91 Billion |
The concrete batch plants market is shaped by leading players such as Elkon, Sany, Putzmeister, AIMIX Group, JEL Concrete Plants, Liebherr, Ammann, Astec, Meka, and Cemco. These companies focus on product innovation, advanced automation, and modular plant designs to strengthen their market position. Many emphasize sustainable and energy-efficient solutions to align with global construction standards. Strategic expansions, partnerships, and smart batching technologies help them meet diverse project demands across regions. Asia Pacific leads the global market with a 38% share, driven by rapid urbanization, infrastructure investments, and rising adoption of high-capacity batching systems for large-scale construction projects.
Market Insights
- The concrete batch plants market size was valued at USD 3.79 billion in 2024 and is projected to reach USD 4.91 billion by 2032, registering a CAGR of 3.3%.
- Strong infrastructure development, rapid urbanization, and rising adoption of ready-mix concrete drive steady market expansion across residential, commercial, and industrial projects.
- Modular and mobile batching plants, energy-efficient systems, and digital control technologies are key trends transforming the industry landscape.
- The market is competitive with major players focusing on automation, smart monitoring, and sustainable designs to strengthen their global presence.
- Asia Pacific leads with a 38% regional share, supported by large-scale infrastructure investments, while the 30–80 m³/h capacity segment dominates due to its versatility and cost efficiency.
Market Segmentation Analysis:
By Type
Stationary batch plants dominate the market with a major share. These plants are widely adopted for large infrastructure and commercial projects that demand high output and consistent quality. They support automated control systems, which enhance operational efficiency and reduce material wastage. Stationary plants also enable precise mixing, ensuring uniform concrete composition. This capability makes them a preferred choice for urban development and large-scale construction. Their robust design and long-term cost benefits drive adoption in industrial and infrastructure projects, maintaining their lead over mobile batch plants.
- For instance, Elkon’s stationary concrete batching plant ELKOMIX-200 features a 200 m³/h capacity and an automated twin-shaft mixer system, enabling precise and continuous production for high-volume projects.
By Capacity
The 30–80 m³/h capacity segment holds the dominant share in the market. This segment is popular because it offers a balance between operational flexibility and high production output. It caters to mid-sized construction projects, such as residential complexes, commercial buildings, and road construction. Many contractors prefer this capacity range as it provides efficient batching without requiring large-scale investment. Its adaptability to both stationary and mobile setups further strengthens its market position. High demand in emerging economies with active construction activities drives this segment’s growth.
- For instance, Sany offers a range of batching plants, including models with a rated output of 60 m³/h, such as the HZS60F, HZS60G, or HZS60X8. These models are typically equipped with a twin-shaft mixer with a 1000 L capacity and are suitable for medium-scale projects, while the HZS60V8 model has a rated output of 50 m³/h and a 1000 L mixer.
By Mix Type
Wet concrete mix plants lead the market with a significant share. These plants ensure high-quality and uniform concrete by combining all materials with water before discharge. Wet mix plants deliver better strength and durability, making them suitable for critical construction applications such as bridges, tunnels, and highways. Their faster batching and consistent performance support large-scale, time-sensitive projects. The increasing emphasis on quality standards in construction further boosts the adoption of wet mix plants over dry mix alternatives, reinforcing their dominant position in the market.
Key Growth Drivers
Rapid Urbanization and Infrastructure Development
Rising urbanization and growing infrastructure projects drive the demand for concrete batch plants. Governments and private developers are investing in road networks, bridges, housing, and commercial spaces. High-capacity stationary plants are preferred for large projects due to their reliability and efficiency. For instance, large-scale metro and expressway projects require continuous concrete production to meet strict timelines. This infrastructure boom, especially in emerging economies, strengthens market growth and encourages investment in advanced batching technology to meet rising concrete production requirements.
- For instance, Putzmeister’s MT 3.0 batching plant is designed for continuous high-output operations, offering a 120 m³/h production capacity with an advanced 3000 L twin-shaft mixer and an automated moisture control system for precise concrete quality during large infrastructure builds.
Advancements in Automation and Digitalization
Automation and digital control systems are transforming the concrete batching process. Modern batch plants integrate sensors, SCADA systems, and IoT-based monitoring to improve accuracy and reduce manual errors. Automated systems enable consistent concrete quality, efficient material use, and lower operational costs. Companies are also adopting predictive maintenance to minimize downtime. These advancements increase productivity and improve plant performance. As construction projects demand tighter quality control and faster output, the integration of smart technologies becomes a strong driver for market expansion.
- For instance, The AIMIX AJ-60 stationary concrete batching plant features a PLC and touchscreen system with one-click start and dual-mode control.
Rising Demand for Ready-Mix Concrete
The growing preference for ready-mix concrete boosts the adoption of concrete batch plants. Contractors prefer ready-mix due to its uniform quality, faster application, and reduced labor requirements. Urban construction and infrastructure projects require quick delivery of large concrete volumes, which batch plants can provide efficiently. The trend is strong in commercial and residential projects where on-site mixing is less feasible. Increased investment in ready-mix facilities worldwide supports market expansion, driving demand for both stationary and mobile batching solutions.
Key Trends & Opportunities
Shift Toward Modular and Mobile Plants
The adoption of mobile and modular batching plants is rising due to their flexibility and cost efficiency. These plants are ideal for remote locations and temporary project sites. Mobile units allow rapid setup and relocation, reducing installation costs and delays. Contractors use modular systems to scale production capacity based on project needs. This flexibility attracts infrastructure developers looking to optimize operational efficiency. The shift creates opportunities for manufacturers to develop compact, transportable, and energy-efficient models tailored to evolving construction requirements.
- For instance, JEL’s Decumulator mobile precast plant supports a 20-ton daily capacity, with optional expansion to 40 tons, and uses individual aggregate scales for pre-blending before mixer feed.
Sustainable Construction and Green Technologies
Sustainability is becoming a major focus in the construction industry. Manufacturers are introducing batching plants with reduced energy use, low emissions, and recycling capabilities. Integration of water recycling systems and eco-friendly admixtures supports green building practices. Regulations promoting low-carbon construction create opportunities for companies offering sustainable plant designs. Growing interest in LEED-certified projects and net-zero goals further drives this trend. As environmental standards tighten globally, sustainable concrete batching solutions gain a competitive advantage in the market.
- For instance, Liebherr’s new generation of Betomix and Mobilmix plants use frequency converters to smooth power peaks and optimize mixing, reducing energy consumption by up to 30%. With an advanced dosing accuracy of ±0.35% for cement, the plants can save up to 8 kg of cement per cubic meter of concrete in a typical mix.
Integration of Advanced Control and Monitoring Systems
The increasing use of cloud-based monitoring and AI-driven control systems enhances operational visibility. Smart batching plants track material flow, mixing accuracy, and plant performance in real time. These systems help contractors maintain quality standards and reduce wastage. Digital dashboards allow remote monitoring and quick decision-making, improving overall productivity. Companies are investing in advanced controls to differentiate their offerings and meet modern construction demands. This technological shift presents strong opportunities for innovation and market growth.
Key Challenges
High Initial Investment and Maintenance Costs
The cost of setting up concrete batch plants is a major barrier for small and medium contractors. Stationary plants, in particular, require significant capital for installation, power infrastructure, and automated controls. Maintenance costs further add to operational expenses, impacting profitability for low-volume projects. This financial burden limits adoption in smaller construction firms and rural projects. Manufacturers need to address this challenge by offering modular financing, leasing options, or low-cost plant models to encourage wider market penetration.
Stringent Environmental Regulations
Tighter environmental norms for dust control, emissions, and water usage pose operational challenges. Concrete batching involves dust generation and high water consumption, which must comply with local environmental standards. Meeting these regulations often requires installing advanced dust collectors, recycling systems, and emission control units, increasing costs. Non-compliance can lead to penalties or shutdowns. Adapting to these regulations without reducing productivity remains a key challenge for plant operators and manufacturers, especially in regions with strict sustainability policies.
Regional Analysis
North America
North America holds a 28% share of the concrete batch plants market, driven by strong infrastructure investments and advanced construction technologies. The U.S. leads the region with large-scale projects in transportation, commercial real estate, and residential development. Government initiatives, such as highway expansions and bridge rehabilitation programs, support steady demand for stationary and mobile batching solutions. The region also emphasizes sustainability, encouraging the use of energy-efficient and low-emission plants. Technological adoption, including automated control systems and smart monitoring, enhances plant productivity and quality control, further strengthening North America’s position as a key contributor to global market growth.
Europe
Europe accounts for a 22% market share, supported by strict construction quality standards and environmental regulations. Countries like Germany, France, and the U.K. lead infrastructure modernization, renewable energy projects, and urban housing developments. The region prioritizes low-emission and energy-efficient concrete batch plants to align with its carbon reduction targets. Advanced batching technologies and automation drive adoption in both public and private sector projects. Additionally, the circular economy trend encourages the integration of water recycling systems in batching facilities. These factors position Europe as a technologically mature and environmentally focused market with stable long-term growth prospects.
Asia Pacific
Asia Pacific dominates the market with a 38% share, driven by rapid urbanization, industrialization, and large infrastructure investments. China, India, and Southeast Asian countries are leading contributors, supported by government-led transportation and housing projects. The demand for high-capacity stationary and mobile batching plants is growing due to mega infrastructure programs such as metro rail networks, highways, and smart cities. Rising adoption of ready-mix concrete and automation enhances efficiency across construction sites. Manufacturers are expanding production facilities to meet increasing regional demand, making Asia Pacific the fastest-growing and most dynamic region in the global concrete batch plants market.
Latin America
Latin America holds an 8% market share, driven by rising investments in infrastructure modernization and urban development. Countries like Brazil and Mexico are witnessing growing demand for efficient batching solutions for residential and commercial construction. Mobile and modular plants are gaining traction due to their flexibility and lower setup costs. Public-private partnerships in road and transport infrastructure further fuel the market. However, slower economic growth and regulatory gaps limit large-scale technology adoption. Despite these challenges, increasing construction activity and foreign investments present steady opportunities for batching plant manufacturers in the region.
Middle East & Africa
The Middle East & Africa region captures a 4% market share, supported by growing construction and infrastructure development, particularly in GCC countries. Mega projects such as smart cities, highways, and commercial complexes drive the demand for advanced batching solutions. UAE and Saudi Arabia lead regional growth with investments in sustainable and high-capacity stationary plants. African countries are increasingly adopting mobile plants for cost-effective construction in remote areas. While infrastructure financing remains a challenge in parts of Africa, ongoing government initiatives and foreign investments are expected to strengthen the region’s contribution to the global concrete batch plants market.
Market Segmentations:
By Type:
- Stationary batch plant
- Mobile batch plant
By Capacity:
- Below 30 m³/h
- 30-80 m³/h
By Mix Type:
- Wet concrete mix
- Dry concrete mix
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The concrete batch plants market is highly competitive, with major players including Elkon, Sany, Putzmeister, AIMIX Group, JEL Concrete Plants, Liebherr, Ammann, Astec, Meka, and Cemco. The concrete batch plants market is characterized by strong competition, continuous innovation, and a growing focus on sustainability. Manufacturers are prioritizing advanced automation, digital monitoring, and energy-efficient designs to enhance plant performance. Many companies are introducing modular and mobile systems to meet the needs of infrastructure projects in both urban and remote areas. Technological integration, including smart control systems and real-time production monitoring, improves quality control and operational flexibility. The market also sees rising investment in eco-friendly solutions to comply with stricter environmental regulations. Expansion strategies, product differentiation, and after-sales service offerings further intensify the competitive landscape.
Key Player Analysis
- Elkon
- Sany
- Putzmeister
- AIMIX Group
- JEL Concrete Plants
- Liebherr
- Ammann
- Astec
- Meka
- Cemco
Recent Developments
- In January 2025, Ammann India offers Super-Tech asphalt batch mix plants, a 10 meter Ammann ABG track pavers, concrete batching plants, CE Stage V Compactors. Ammann has ventured into concreting solutions with its trailer-mounted stationary pumps, concrete batch mix plants that feature ELBA technology working on Ammann’s software.
- In December 2024, Normet introduced a new series of construction equipment in India, such as low-cost concrete spraying machines and hydraulic breakers for better efficiency. The new arrivals at Bauma CONEXPO India 2024 are for tunneling and underground applications to meet increasing infrastructure needs in India through better and economical technologies.
- In October 2024, SBM Mineral Processing presented the new SBM Euromix 1600 Nova mobile concrete mixing plant. It is a replacement for the previous entry-level model in the Euromix range, with up to 80 m³/h of hardened concrete production capacity. The concepts important cornerstones are a high degree of operator comfort and safety paired with high efficiency in year-round operation.
- In July 2024, AJAX Engineering introduced Concrete GPT, an India construction sector AI-powered platform. Powered by GPT-4, it offers technical data, maintenance alerts, and regulation news in various languages. With chatbot, voice, and WhatsApp support, it enhances project efficiency and skill enhancement, which facilitates better operation of concrete equipment and new age technologies in the industry.
Report Coverage
The research report offers an in-depth analysis based on Type, Capacity, Mix Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for mobile and modular batching plants will increase to support flexible construction needs.
- Automation and digital control technologies will become standard features across new plant installations.
- Sustainable and energy-efficient designs will gain stronger adoption due to stricter environmental regulations.
- Smart monitoring and IoT integration will enhance operational efficiency and reduce downtime.
- Urbanization and infrastructure development will drive strong market expansion in emerging economies.
- Ready-mix concrete production will continue to be a key growth area for plant installations.
- Manufacturers will focus on compact designs to reduce setup time and improve mobility.
- Strategic collaborations and partnerships will help companies expand their regional footprint.
- Advanced recycling systems will support eco-friendly construction practices and resource optimization.
- Continuous R&D investment will lead to improved productivity and higher precision in batching processes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Concrete Batch Plants Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Concrete Batch Plants Market projected to grow between 2025 and 2032?
Which Concrete Batch Plants Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Concrete Batch Plants Market?
Who are the leading companies in the Concrete Batch Plants Market?
Which region commanded the largest share of the Concrete Batch Plants Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Concrete Batch Plants Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Concrete Batch Plants Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.79 billion → 2032: USD 4.91 billion)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Concrete Batch Plants Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Concrete Batch Plants Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Concrete Batch Plants Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Concrete Batch Plants Market Drivers
- 3.3 Concrete Batch Plants Market Restraints & Challenges
- 3.4 Concrete Batch Plants Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Concrete Batch Plants Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Concrete Batch Plants Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Concrete Batch Plants category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Concrete Batch Plants Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Concrete Batch Plants Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Concrete Batch Plants. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Concrete Batch Plants Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Concrete Batch Plants Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Concrete Batch Plants Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Concrete Batch Plants (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Concrete Batch Plants
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Concrete Batch Plants Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Concrete Batch Plants Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Concrete Batch Plants Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Concrete Batch Plants Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Concrete Batch Plants Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Concrete Batch Plants Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Concrete Batch Plants Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Concrete Batch Plants Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
