
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
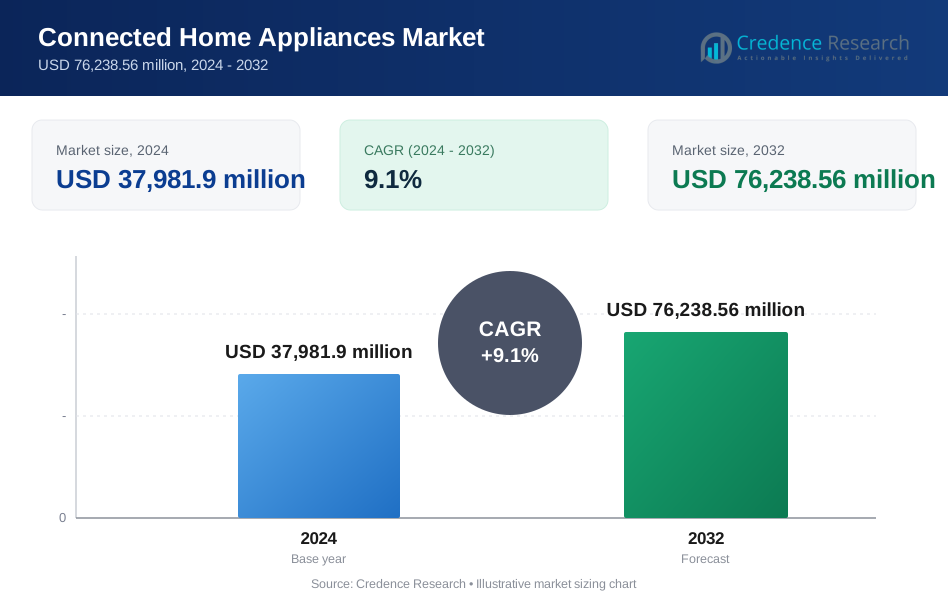
| Connected Home Appliances Market Size 2024 | USD 37981.9 million |
| Connected Home Appliances Market, CAGR | 9.1% |
| Connected Home Appliances Market Size 2032 | USD 76238.56 million |
Market Overview:
The Connected Home Appliances Market is projected to grow from USD 37981.9 million in 2024 to an estimated USD 76238.56 million by 2032, with a compound annual growth rate (CAGR) of 9.1% from 2024 to 2032.
The growth of the Connected Home Appliances Market is underpinned by a convergence of technological advancements, consumer demand, and policy support. The integration of IoT and AI technologies has redefined traditional appliances, offering seamless connectivity, voice-activated controls, and predictive maintenance capabilities that enhance convenience and efficiency. Growing consumer awareness about sustainability and energy conservation has further propelled the adoption of smart devices, as these appliances enable real-time monitoring and optimization of energy usage, reducing environmental impact. Governments worldwide are promoting energy-efficient technologies through subsidies and incentives, encouraging households to transition to connected solutions. The proliferation of e-commerce platforms has made these devices increasingly accessible, especially in emerging markets. Furthermore, declining production costs and advancements in wireless connectivity have lowered entry barriers, allowing consumers from diverse economic backgrounds to participate in this technological shift.
The Connected Home Appliances Market exhibits diverse regional dynamics, reflecting varying levels of technological adoption and infrastructure. North America dominates the market due to its high disposable income levels, well-established IoT ecosystems, and early adoption of smart home technologies. The region's tech-savvy population and strong retail distribution channels further enhance market growth. Europe follows as a key player, driven by stringent energy efficiency regulations and widespread adoption of smart home initiatives. Asia-Pacific, however, is emerging as the fastest-growing market, supported by rapid urbanization, rising middle-class income, and increasing smartphone and internet penetration in countries like China, India, and Japan. In Latin America and the Middle East & Africa, growth remains in the early stages but holds substantial potential. Improvements in digital infrastructure and rising awareness about connected appliances in these regions are expected to unlock significant opportunities in the coming years.
Market Drivers:
Integration of IoT and AI Driving Smart Functionality:
The integration of the Internet of Things (IoT) and artificial intelligence (AI) is revolutionizing the connected home appliances market. IoT enables seamless interconnectivity among devices, allowing users to monitor and control appliances remotely via smartphones or voice-activated assistants. AI enhances this functionality by introducing predictive analytics and automation. For instance, LG Electronics has developed smart refrigerators that use AI to analyze consumption patterns and suggest restocking needs. Similarly, AI-driven HVAC systems from companies like Honeywell optimize energy usage based on occupancy patterns. These advancements significantly improve user convenience and operational efficiency, making connected appliances an integral part of modern households.
Rising Consumer Demand for Energy Efficiency and Sustainability:
The growing emphasis on energy conservation and environmental sustainability is a key driver of market growth. Consumers are increasingly opting for smart appliances that offer energy-efficient solutions and contribute to lower carbon footprints. Governments and regulatory bodies across the globe are supporting this trend through policies and incentives that encourage energy efficiency. For example, several regions provide rebates for installing energy-saving connected appliances. This push towards sustainability has not only boosted the adoption of such devices but has also prompted manufacturers to innovate and develop eco-friendly products, further expanding the market.
Growth in E-commerce and Digital Connectivity:
The rapid expansion of e-commerce platforms and enhanced digital connectivity are making connected home appliances more accessible to a wider audience. Online retail channels provide consumers with detailed product information, reviews, and competitive pricing, simplifying the purchasing process. Furthermore, advancements in wireless technologies, such as Wi-Fi 6 and 5G, have improved the reliability and speed of smart appliance operations. For instance, Amazon's integration of Alexa with smart home devices has significantly lowered entry barriers for consumers. These developments have accelerated market penetration, making the convenience of online shopping combined with efficient connectivity solutions a significant driver of sales for connected home appliances.
Technological Advancements and Cost Reductions:
Continuous technological advancements and decreasing production costs are catalyzing the growth of the connected home appliances market. Innovations in sensors, cloud computing, and data analytics have enhanced the capabilities of smart devices, enabling them to deliver personalized and efficient services. Additionally, as the cost of components like microprocessors and sensors declines, the overall affordability of connected appliances improves. This cost reduction has made these appliances accessible to a broader demographic, particularly in price-sensitive markets. The trend has also encouraged manufacturers to diversify their product portfolios and cater to a wide range of consumer preferences, further stimulating market demand.
Market Trends:
Increasing Adoption of Voice-Activated Technology:
The integration of voice-activated technology is emerging as a dominant trend in the connected home appliances market. For instance, as of 2023, approximately 125.2 million people globally utilize voice assistants, reflecting a notable increase from previous years. Devices equipped with virtual assistants, such as Amazon Alexa, Google Assistant, and Apple Siri, are becoming integral to smart home ecosystems. Voice activation enables users to interact with appliances effortlessly, whether adjusting the temperature of a smart thermostat, preheating an oven, or starting a washing machine. According to industry reports, the adoption rate of voice-controlled smart appliances grew by over 20% in 2023, reflecting a shift toward more user-friendly, hands-free operations. This trend is likely to gain momentum as virtual assistants become more sophisticated and widely compatible across devices.
Expansion of Subscription-Based Services:
Another emerging trend in the connected home appliances market is the rise of subscription-based services. Manufacturers are increasingly offering value-added services alongside connected appliances, such as maintenance alerts, performance analytics, and energy usage insights. For instance, some smart refrigerators provide subscription plans for automated grocery replenishment, while HVAC systems offer real-time air quality monitoring for a monthly fee. This shift allows companies to create recurring revenue streams while providing consumers with enhanced functionality and convenience.
Growing Focus on Interoperability Standards:
Interoperability has become a critical focus area in the connected home appliances market. With consumers increasingly using multiple brands and platforms within their smart homes, seamless integration has become a priority. Initiatives like the Matter protocol—a universal connectivity standard—aim to address compatibility issues, enabling devices from different manufacturers to work together effortlessly. By 2025, over 50% of smart home devices are expected to support such interoperability standards. This trend not only enhances the consumer experience but also fosters collaboration among market players, promoting innovation and expanding market reach.
Regional Diversification and Emerging Market Potential:
The connected home appliances market is witnessing a trend of regional diversification, with significant growth occurring in emerging markets. Countries in Asia-Pacific, such as India, Indonesia, and Vietnam, are seeing rapid adoption of connected appliances due to increasing disposable incomes, urbanization, and improving digital infrastructure. Localized product offerings tailored to the needs and budgets of these regions are gaining traction. For example, manufacturers are developing affordable smart appliances with essential features to cater to cost-sensitive consumers. By 2030, Asia-Pacific is expected to account for nearly 35% of the global market share, marking a substantial shift in market dynamics and highlighting the untapped potential in these regions.
Market Restraints and Challenges:
High Initial Costs and Limited Affordability:
One of the significant restraints in the connected home appliances market is the high initial cost of smart devices, which limits their accessibility to price-sensitive consumers. Advanced technologies, such as IoT integration, AI capabilities, and premium materials, contribute to the elevated pricing of these appliances. While prices have gradually declined due to mass production and technological advancements, affordability remains a barrier, particularly in developing economies. This challenge slows adoption rates among middle- and low-income households, affecting market penetration in regions with emerging economies.
Privacy and Data Security Concerns:
The increasing reliance on connectivity and data sharing in smart home appliances raises concerns about privacy and data security. Connected devices often collect sensitive user information, including behavioral patterns and energy usage data, which can be vulnerable to cyberattacks. Data breaches and hacking incidents can erode consumer trust, creating hesitation to adopt smart home technologies. Despite efforts by manufacturers to enhance cybersecurity measures, the perception of risk remains a critical challenge for widespread market adoption.
Connectivity Issues and Infrastructure Limitations:
The performance of connected home appliances heavily depends on stable and high-speed internet connectivity. In regions with limited digital infrastructure or unreliable networks, users often face connectivity issues that hinder the seamless operation of these devices. Additionally, rural areas in developing countries lack the necessary broadband coverage to support smart home ecosystems. These infrastructure limitations restrict the potential reach of the connected home appliances market, particularly in underserved areas.
Lack of Standardization and Interoperability:
The absence of standardized protocols and interoperability among different brands and platforms creates compatibility challenges for consumers. Many users face difficulties integrating appliances from multiple manufacturers within a single smart home ecosystem. This lack of uniformity can lead to frustration and reduce the appeal of investing in connected devices. While industry efforts, such as the Matter protocol, aim to address this issue, the slow adoption of standards across all manufacturers remains a significant obstacle.
Market Segmentation Analysis:
The Connected Home Appliances Market is segmented by component, platform, technology, and functionality, offering diverse insights into its dynamic structure.
By Component, the market includes solutions tailored for specific needs, such as Lighting Control, Security, Entertainment, and Home Healthcare, addressing varied consumer priorities. Energy Management Solutions and Kitchen Solutions are gaining traction due to increasing consumer focus on sustainability and convenience. HVAC Solutions cater to growing demands for climate control, while Professional and Managed Services provide essential support for installation, maintenance, and seamless integration of devices.
By Platform, Smartphones dominate as the primary control hub for connected appliances, thanks to their ubiquity and ease of use. Laptops and Home Gateways provide alternative platforms, while Other Platforms like tablets and wearable devices enhance versatility and accessibility.
By Technology, Wi-Fi-powered appliances lead the market due to their widespread compatibility and network stability. Bluetooth-powered devices offer localized control, while NFC-powered appliances are increasingly used for contactless operation and pairing.
Segmentation:
By Component
- Lighting Control Solution
- Security Solution
- Entertainment Solution
- Home Healthcare Solution
- Energy Management Solution
- Kitchen Solution
- HVAC Solution
- Professional Services
- Managed Services
By Platform
- Smartphones
- Laptops
- Home Gateway
- Other platforms
By Technology
- Wi-Fi-powered
- NFC-powered
- Bluetooth-powered
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Connected Home Appliances Market demonstrates significant regional variations, driven by differences in technological adoption, infrastructure, and consumer behavior. The market is dominated by North America, followed by Europe, with Asia-Pacific emerging as the fastest-growing region. Regions such as Latin America and the Middle East & Africa (MEA) are in nascent stages but hold substantial growth potential.
North America accounts for the largest market share, approximately 35% in 2024. This dominance is attributed to early adoption of smart home technologies, high disposable incomes, and a robust IoT ecosystem. The United States leads the region, driven by widespread internet penetration, the popularity of voice-activated devices, and government initiatives promoting energy-efficient technologies. Canada also contributes significantly, with a growing inclination toward sustainable and connected living solutions.
Europe holds the second-largest market share, approximately 28%, supported by stringent regulations on energy efficiency and a strong emphasis on sustainable housing solutions. Countries like Germany, the U.K., and France are at the forefront, with increasing adoption of smart kitchen and HVAC appliances. Government incentives and the rising trend of green buildings further boost the market.
The Asia-Pacific region is the fastest-growing, accounting for nearly 25% of the market. Rapid urbanization, rising middle-class income levels, and improving internet infrastructure drive growth in countries like China, India, and Japan. China leads the regional market due to its advanced manufacturing capabilities and extensive domestic consumption. India and Southeast Asia are also experiencing significant growth, driven by affordable smart appliances tailored to local preferences.
Latin America represents approximately 7% of the market and shows steady growth, driven by increasing smartphone penetration and growing awareness of connected home solutions. Brazil and Mexico are the key contributors, supported by urbanization and expanding digital infrastructure.
The Middle East & Africa (MEA) accounts for roughly 5% of the market. Growth is primarily concentrated in the GCC countries, where high disposable incomes and investments in smart city projects create opportunities. South Africa is also emerging as a notable market due to its improving internet access and growing adoption of smart appliances.
Key Player Analysis:
- ARRIS Group
- AT&T Inc.
- Comcast Corporation
- General Electric
- Haier
- Hisense
- Honeywell International Inc.
- LG
- Midea
- Miele and Cie
- Robert Bosch GmbH
- Samsung Group
- Whirlpool Corporation
Competitive Analysis:
The Connected Home Appliances Market is highly competitive, with major players leveraging innovation and strategic partnerships to strengthen their market positions. Key industry leaders such as Samsung Electronics, LG Electronics, Whirlpool Corporation, Haier Group, and Bosch focus on integrating cutting-edge technologies like IoT, AI, and voice control into their product portfolios. These companies invest heavily in R&D to enhance user experience and expand their offerings across smart kitchens, HVAC systems, and security solutions. Emerging players and startups also contribute to market dynamics by offering niche solutions and affordable alternatives, particularly in price-sensitive regions. Strategic alliances, such as collaborations with tech firms (e.g., Google and Amazon), have become common, enabling seamless integration of smart home ecosystems. Intense competition drives continuous innovation, leading to a broader range of products tailored to diverse consumer needs, ensuring sustained market growth and differentiation among competitors.
Recent Developments:
- In March 2024, Samsung Electronics reached a significant milestone as its Bespoke Jet Bot Combo™ AI and Family Hub Refrigerators became the first in the industry to receive the prestigious 'Diamond' level IoT security verification from UL Solutions.
- In March 2024, Haier India marked its 20th anniversary by unveiling a new range of smart home appliances, including TVs, air conditioners, refrigerators, and washing machines. The company also expanded its production facilities in Pune and Greater Noida, employing over 35,000 workers and catering to a customer base of 25 million.
- In November 2023, Whirlpool Corporation contributed to the Matter 1.2 update, enhancing the connectivity of appliances like washing machines and refrigerators. This update aimed to improve user experience and ensure better interoperability among connected devices.
- In August 2023, Reliance Jio introduced Jio Smart Home Services, a platform enabling seamless control of home appliances. At RIL’s Annual General Meeting, Chairman Akash Ambani highlighted its potential to redefine home management and elevate the smart home ecosystem.
Market Concentration & Characteristics:
The Connected Home Appliances Market is moderately concentrated, with a mix of global giants and regional players competing for market share. Leading companies such as Samsung Electronics, LG Electronics, Whirlpool Corporation, and Bosch dominate the market through extensive R&D, strong brand recognition, and a broad product portfolio. These key players leverage advanced technologies like IoT, AI, and voice control to maintain competitive advantages. The market is characterized by rapid innovation, high consumer demand for convenience, and a growing emphasis on energy efficiency and sustainability. Despite the dominance of established brands, emerging players and startups are gaining traction by offering affordable, niche, and region-specific solutions. Intense competition fosters continuous product enhancements and strategic collaborations, such as partnerships with tech firms and smart home ecosystem providers. This competitive landscape drives market growth while ensuring diverse options for consumers globally.
Report Coverage:
The research report offers an in-depth analysis based on By Component, By Platform and By Technology It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing adoption of AI and IoT technologies will drive innovation in functionality and user experience.
- Expanding smart city initiatives will enhance infrastructure, boosting demand for connected home appliances.
- Increasing consumer focus on energy efficiency and sustainability will promote eco-friendly product development.
- Integration of advanced security features will address privacy concerns, fostering greater consumer trust.
- Voice control and interoperability advancements will streamline smart home ecosystem integration.
- Rising disposable incomes in emerging markets will expand the customer base for connected appliances.
- Subscription-based models and service add-ons will create new revenue streams for manufacturers.
- Enhanced affordability through technological advancements and economies of scale will accelerate adoption.
- Continued growth in e-commerce platforms will increase accessibility and convenience for consumers.
- Collaboration between tech giants and appliance manufacturers will further refine device compatibility and performance.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Connected Home Appliances Market?
What factors are driving the market growth?
Which region leads the Connected Home Appliances Market?
What are the challenges in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Connected Home Appliances Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Connected Home Appliances Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 37,981.9 million → 2032: USD 76,238.56 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Connected Home Appliances Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Connected Home Appliances Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Connected Home Appliances Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Connected Home Appliances Market Drivers
- 3.3 Connected Home Appliances Market Restraints & Challenges
- 3.4 Connected Home Appliances Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Connected Home Appliances Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Connected Home Appliances Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Connected Home Appliances category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Connected Home Appliances Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Connected Home Appliances Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Connected Home Appliances market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Connected Home Appliances Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Connected Home Appliances Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Connected Home Appliances Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Connected Home Appliances (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Connected Home Appliances Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Connected Home Appliances Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Connected Home Appliances Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Connected Home Appliances Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Connected Home Appliances Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Connected Home Appliances Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Connected Home Appliances Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Connected Home Appliances Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Connected Home Appliances Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
