
Market Overview
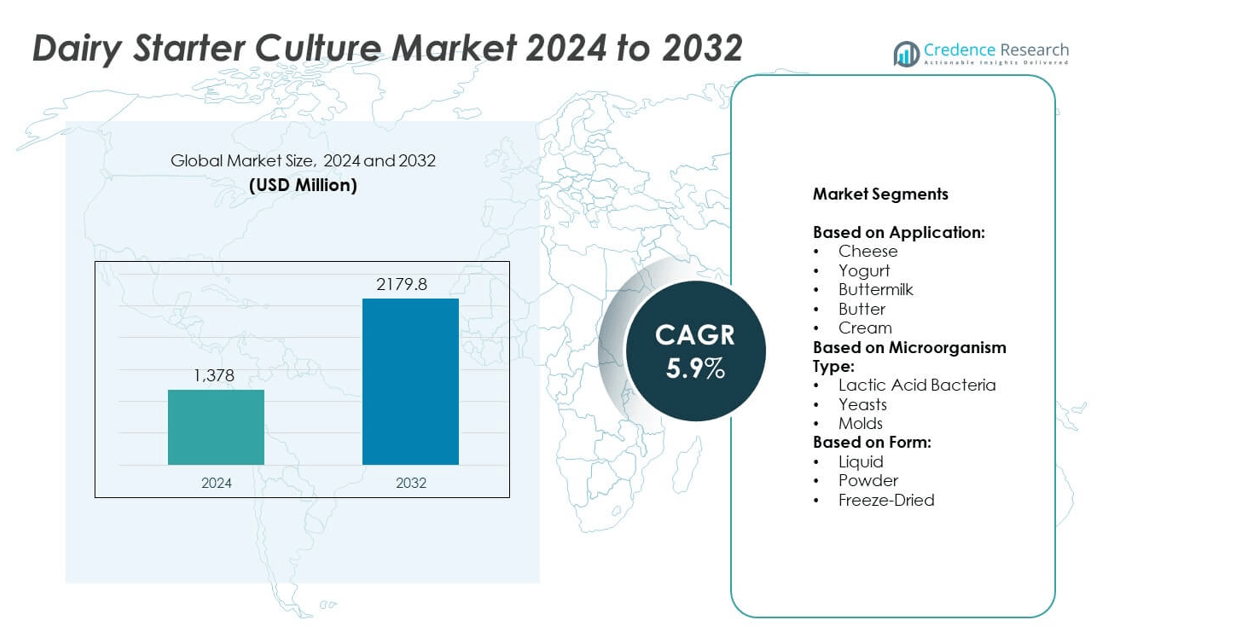
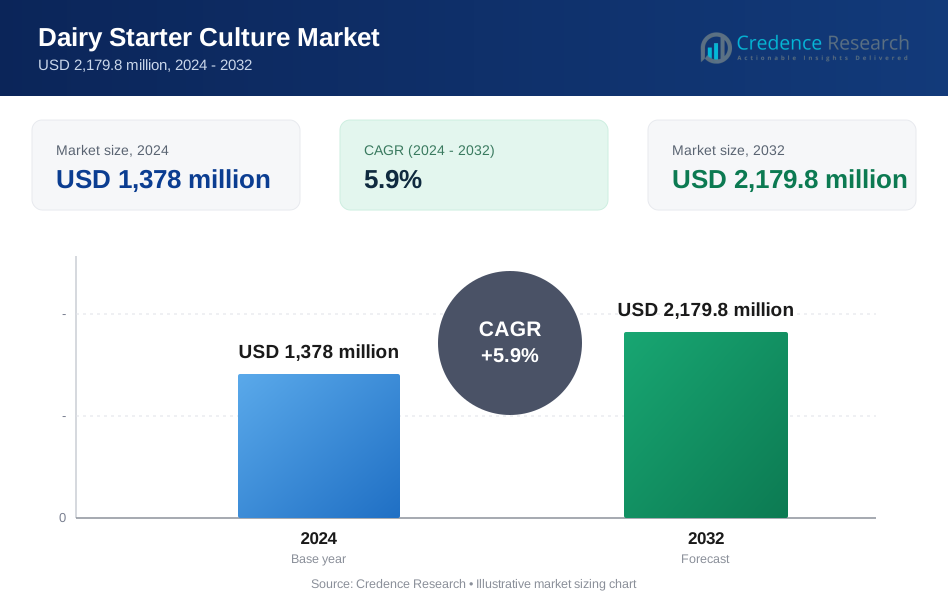
Dairy Starter Culture Market size was valued at USD 1,378 million in 2024 and is anticipated to reach USD 2,179.8 million by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dairy Starter Culture Market Size 2024 | USD 1,378 million |
| Dairy Starter Culture Market, CAGR | 5.9% |
| Dairy Starter Culture Market Size 2032 | USD 2,179.8 million |
The Dairy Starter Culture market grows with rising demand for probiotic-rich, clean-label dairy products across global markets. Manufacturers focus on developing stable, multi-strain cultures that enhance product safety, texture, and shelf life. Functional strains offering digestive and immune benefits attract health-conscious consumers. Technological advances in freeze-drying and microencapsulation improve culture performance and storage. The market also benefits from the expanding dairy sector in emerging economies and increased use of customized cultures for regional taste preferences and traditional recipes.
Europe leads the Dairy Starter Culture market due to its strong dairy traditions, advanced processing infrastructure, and demand for high-quality fermented products. North America follows, supported by high yogurt and cheese consumption and innovation in probiotic cultures. Asia-Pacific shows rapid growth driven by urbanization, dietary shifts, and government-backed dairy programs. Latin America and the Middle East & Africa offer growth potential through infrastructure expansion and rising dairy intake. Key players include DuPont, Hansen, Danone, and FrieslandCampina, each focusing on innovation and regional expansion.
Market Insights
- The Dairy Starter Culture market was valued at USD 1,378 million in 2024 and is projected to reach USD 2,179.8 million by 2032, growing at a CAGR of 5.9%.
- Growth is driven by rising demand for probiotic-rich, clean-label, and functional dairy products.
- Trends include adoption of freeze-dried and microencapsulated cultures to improve shelf life and transport.
- Leading players focus on multi-strain innovations, probiotic functionality, and digital fermentation systems.
- Regulatory barriers, cold chain limitations, and strain-specific approvals pose challenges in developing markets.
- Europe dominates due to advanced dairy processing and demand for premium cheese and yogurt; Asia-Pacific grows fastest with increased dairy consumption.
- Companies expand regionally through localization, public-private partnerships, and tailored starter culture blends.
Market Drivers
Rising Demand for Fermented Dairy Products Across Diverse Consumer Segments
The Dairy Starter Culture market is driven by growing global consumption of fermented dairy products like yogurt, cheese, and buttermilk. Health-conscious consumers seek probiotic-rich foods to support gut health and immunity. Rising awareness of digestive disorders accelerates demand for fermented options. It fuels adoption of starter cultures to standardize taste and ensure microbial safety. The market benefits from increased product launches with functional health claims. Manufacturers focus on incorporating multi-strain cultures to enhance texture and shelf life.
- For instance, Chr. Hansen maintains a collection of approximately 40,000 microbial strains. This large strain library supports its innovations in starter culture performance, bio-protection, and flavor consistency, enabling faster selection and scale-up of new culture blends.
Growing Penetration of Clean-Label and Organic Dairy Products
The shift toward natural and clean-label dairy products strongly influences demand for biological fermentation agents. Consumers reject artificial preservatives and chemical additives, preferring naturally processed alternatives. The Dairy Starter Culture market gains traction through its alignment with organic labeling and minimal processing. It supports claims of authenticity and traditional fermentation processes. Regulatory bodies encourage clean-label transparency, pushing producers to adopt natural culture solutions. Rising consumption of premium and artisanal dairy further drives starter culture use.
- For instance, DuPont Nutrition & Biosciences launched its YO-MIX PRIME culture series (Prime 800 and Prime 900) which allows yogurt makers to cut back on skimmed-milk powder, reduce sugar content while maintaining sweetness perception, and retain quality through fluctuating storage temperatures.
Expansion of Industrial Dairy Processing and Globalization of Dairy Trade
Large-scale dairy production and exports create need for consistent, high-quality fermentation cultures. Manufacturers seek reliable cultures to maintain product uniformity across global supply chains. It ensures microbial stability during long-distance transportation and storage. The Dairy Starter Culture market supports commercial operations by reducing batch variation and spoilage. Increased investment in automated dairy processing lines integrates culture inoculation systems for precision. Global dairy trade liberalization enables rapid adoption of commercialized starter blends.
Supportive Government Nutrition Programs and Fortified Dairy Initiatives
Government-backed nutrition programs in developing countries promote dairy consumption to combat malnutrition. Fortified dairy products, such as vitamin-enriched yogurt, require defined microbial cultures for efficacy. The Dairy Starter Culture market sees rising adoption in public health food supply chains. It plays a critical role in producing safe, nutritious dairy for mass distribution. Policy incentives and subsidies for dairy cooperatives improve accessibility to standardized cultures. Public-private partnerships enhance supply and education around cultured dairy benefits.
Market Trends
Advancements in Freeze-Drying and Microencapsulation Technologies for Culture Stability
Innovations in preservation techniques support the growth of stable, longer-lasting dairy cultures. Freeze-drying enhances shelf stability without compromising strain viability or activity. Microencapsulation protects sensitive cultures from heat and acidity during processing. The Dairy Starter Culture market benefits from these technologies by extending product reach in export-focused markets. It enables producers to reduce refrigeration dependence and improve logistics. These advancements also support customized blends with targeted release properties.
- For instance, as of an August 2021 update, Lallemand operated 9 bacteria plants and 27 yeast facilities worldwide, with one bacteria plant in La Ferté-Sous-Jouarre, France, dedicated to Lallemand Specialty Cultures. The company does operate on 5 continents, with offices and production facilities strategically located to serve its markets.
Rising Popularity of Plant-Based and Lactose-Free Dairy Alternatives
Consumers with lactose intolerance or plant-based preferences demand non-dairy fermented products. This trend encourages development of starter cultures tailored to plant-based substrates like soy, almond, and oats. The Dairy Starter Culture market adapts by offering strains capable of fermenting non-traditional bases. It requires innovation in strain selection and nutrient compatibility to match dairy-like taste and texture. Manufacturers also explore hybrid fermentation techniques to support cleaner flavor profiles. This diversification broadens the culture application scope beyond animal-based dairy.
- For instance, Chr. Hansen specifies that its frozen DVS dairy starter cultures contain at least 1 × 10¹⁰ viable cells per gram, while its freeze-dried DVS cultures guarantee a minimum of 5 × 10¹⁰ viable cells per gram under proper storage.
Increased Emphasis on Functional Strains with Probiotic Properties
Consumers seek dairy products that offer digestive and immune system support. This trend fuels demand for cultures that deliver probiotic benefits beyond fermentation. The Dairy Starter Culture market responds by incorporating strains like Lactobacillus rhamnosus and Bifidobacterium lactis. It creates value-added products with health claims that appeal to both mainstream and clinical markets. Research on strain efficacy and survivability under gastrointestinal conditions gains importance. Product labels now highlight specific probiotic strains to attract informed buyers.
Customized Culture Solutions for Regional Tastes and Local Recipes
Regional diversity in fermented dairy preferences creates opportunities for culture customization. Companies tailor starter blends to produce localized flavor, texture, and aroma profiles. The Dairy Starter Culture market supports this trend by offering flexible, modular culture systems. It enables dairy processors to replicate traditional recipes on a commercial scale. Markets in Asia and the Middle East show strong interest in localized yogurt and curd products. Cultural adaptation through microbial design strengthens brand differentiation.
Market Challenges Analysis
Stringent Storage, Handling, and Cold Chain Requirements for Live Cultures
Live bacterial cultures require precise storage and transport conditions to maintain viability. Any deviation in temperature or humidity can degrade culture activity and spoil product quality. The Dairy Starter Culture market faces challenges from regions lacking cold chain infrastructure. It limits penetration in rural or underdeveloped areas where demand for dairy is rising. It also raises operational costs for manufacturers managing international supply chains. Companies must invest in insulated packaging, real-time monitoring, and regional storage hubs to ensure product integrity.
Complex Regulatory Environment and Strain-Specific Approval Delays
The use of microbial cultures in food faces strict regulatory scrutiny across global markets. Every strain often needs individual approval, which delays product launches and adds compliance costs. The Dairy Starter Culture market contends with fragmented guidelines across regions like the EU, US, and Asia-Pacific. It complicates international trade and slows innovation in multi-strain culture development. Labeling laws on probiotics and claims also vary widely, affecting marketing strategies. Companies must navigate complex documentation, testing, and safety standards to access high-growth regions.
Market Opportunities
Expansion of Probiotic-Fortified Dairy in Functional Food Segment
The rising interest in preventive health opens new avenues for probiotic-rich dairy products. Consumers seek yogurt and fermented milk with proven gut and immune benefits. The Dairy Starter Culture market finds strong potential in delivering high-potency strains that survive digestion. It enables producers to differentiate their offerings with clinical strain efficacy. Functional food expansion also attracts pharmaceutical and wellness brands into the cultured dairy segment. Cross-industry collaboration can accelerate product development and reach health-focused demographics.
Untapped Growth Potential in Emerging Economies with Rising Dairy Demand
Emerging markets in Asia, Africa, and Latin America show increasing demand for safe, standardized dairy. Rapid urbanization and growing middle-class populations drive packaged dairy consumption. The Dairy Starter Culture market sees an opportunity to support regional producers with localized, cost-effective culture solutions. It also benefits from government investments in dairy processing infrastructure and nutritional programs. Low market saturation in rural regions offers room for long-term expansion. Strategic partnerships with local cooperatives and governments can strengthen market presence.
Market Segmentation Analysis:
By Application:
Cheese holds the largest share due to its widespread global consumption and diverse processing needs. Starter cultures play a key role in developing cheese texture, flavor, and shelf life. Yogurt follows closely, driven by its probiotic value and increasing preference among health-conscious consumers. The Dairy Starter Culture market also benefits from growing demand for buttermilk and butter in traditional and culinary applications. These products require specific cultures to ensure consistent acidity and fermentation. Cream-based fermented products occupy a niche but growing segment, especially in artisanal and specialty food categories.
- For instance, Lallemand Specialty Cultures directly manages over 2,000 strains of bacteria, yeasts, and molds for dairy, meat, and plant-based solutions.
By Microorganism Type:
Lactic acid bacteria dominate due to their essential role in dairy fermentation. These bacteria control pH, enhance safety, and contribute to flavor formation across all dairy products. It remains the most reliable choice for large-scale and standardized production. Yeasts are gaining relevance in specialty dairy products where flavor and carbonation are needed, such as certain cheese types and fermented creams. Molds serve limited but high-value segments like blue cheese and surface-ripened varieties. Their role in flavor complexity and textural development keeps them relevant in premium cheese production.
- For instance, The Leibniz Institute DSMZ-German Collection of Microorganisms and Cell Cultures holds a bioresource collection larger and more diverse than stated, according to recent figures. As of recent reports, the DSMZ collection houses over 90,000 bioresources, including more than 39,800 bacterial and archaeal strains (not 32,000) and over 9,800 fungal and yeast strain
By Form:
Freeze-dried cultures lead the market due to their long shelf life, ease of transport, and consistent performance. It enables manufacturers to store and distribute cultures across wide geographies with minimal degradation. Powdered cultures follow closely and remain popular in small to mid-scale operations for their ease of mixing and cost-effectiveness. Liquid cultures hold a niche in artisanal and fresh dairy production where immediate usage and rapid fermentation are essential. Each form addresses different production scales and handling preferences, supporting diverse dairy manufacturing needs.
Segments:
Based on Application:
- Cheese
- Yogurt
- Buttermilk
- Butter
- Cream
Based on Microorganism Type:
- Lactic Acid Bacteria
- Yeasts
- Molds
Based on Form:
- Liquid
- Powder
- Freeze-Dried
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds a market share of 29.4% in the global Dairy Starter Culture market, making it one of the most dominant regions. The strong presence of leading dairy processors and advanced cold chain infrastructure supports widespread adoption of starter cultures across cheese, yogurt, and buttermilk segments. The U.S. market is driven by consumer demand for probiotic-rich products and clean-label dairy. Manufacturers focus on incorporating multi-strain cultures to support digestive health and shelf stability. High per capita consumption of cheese and yogurt fuels culture demand, especially in processed and specialty cheese. Regulatory support from agencies such as the FDA further ensures microbial safety and promotes innovation in strain development. Demand for customized cultures in organic and lactose-free dairy also grows steadily across the region.
Europe
Europe accounts for 32.1% of the Dairy Starter Culture market, making it the largest regional contributor by value. Strong dairy traditions in France, Germany, the Netherlands, and Italy drive demand for high-quality fermentation cultures. Cheese remains the dominant application segment in Europe, supported by extensive artisanal and industrial cheese production. The region is also known for strict regulations on microbial strains and labeling, which drives demand for certified, traceable culture solutions. Yogurt and fermented creams also see high adoption due to the region’s focus on digestive wellness. Multinational players based in Europe invest heavily in R&D to develop strain-specific benefits and regional flavor profiles. Clean-label trends and sustainable sourcing practices influence purchasing decisions among European consumers and dairy manufacturers.
Asia-Pacific
Asia-Pacific holds a market share of 21.7% and is the fastest-growing region in the Dairy Starter Culture market. Rising disposable incomes, urbanization, and changing dietary patterns increase the consumption of packaged and probiotic dairy. China, India, and Japan lead in demand for starter cultures used in yogurt, curd, and fermented milk products. It benefits from large-scale investments in dairy processing facilities, especially in India, where the cooperative model boosts production. Korea and Japan drive innovation in functional dairy, favoring strains that offer immune and digestive benefits. The region also shows strong growth in plant-based dairy alternatives, encouraging tailored culture solutions for soy, oat, and almond bases. Governments promote dairy fortification and safety through national health programs, further supporting demand for standardized cultures.
Latin America
Latin America holds a market share of 8.2%, driven by growing dairy consumption in Brazil, Mexico, and Argentina. Cheese and yogurt remain the primary applications for starter cultures, especially in urban markets where cold chain logistics are improving. It also sees rising awareness of probiotic dairy and fermented drinks like kefir. Smaller dairy processors increasingly seek culture solutions to maintain consistency and extend shelf life in warm climates. Regional suppliers collaborate with global players to introduce adapted cultures suitable for local taste profiles and raw milk conditions. Demand for freeze-dried and powdered forms is strong due to limited refrigeration access in rural zones. Regulatory improvements and industry incentives help expand starter culture usage across mid-scale production.
Middle East & Africa
The Middle East & Africa region holds a market share of 8.6% in the global Dairy Starter Culture market. Demand is supported by population growth, urban expansion, and government-backed dairy development programs. Countries like Saudi Arabia, Egypt, and South Africa show increasing adoption of yogurt and laban, both of which rely heavily on starter cultures. It also sees demand from industrial processors aiming to replace traditional fermentation with standardized culture systems for safety and efficiency. Challenges include limited cold chain infrastructure and high import reliance for premium cultures. However, local manufacturing initiatives and rising interest in fortified dairy products create new opportunities. The region also shows interest in customized culture blends for ethnic and fermented dairy drinks, opening room for long-term growth.
Key Player Analysis
- DuPont
- Synergy Flavors
- Agropur
- Almarai
- Hansen
- FrieslandCampina
- Kerry Group
- Nestlé
- Calpis
- Fonterra
- Lactalis
- Groupe Lactalis
- Saputo
- Danone
- Arla Foods
Competitive Analysis
The Dairy Starter Culture market features strong competition among key players such as DuPont, Synergy Flavors, Agropur, Almarai, Hansen, FrieslandCampina, Kerry Group, Nestlé, Calpis, Fonterra, Lactalis, Groupe Lactalis, Saputo, Danone, and Arla Foods. These companies compete on strain innovation, application diversity, and culture stability. Most leading firms offer multi-strain and customized solutions for cheese, yogurt, and buttermilk production. They invest in R&D to develop functional strains with probiotic, digestive, and immunity-boosting properties. Manufacturers also expand freeze-dried and encapsulated forms to support cold chain efficiency and export needs. Many players focus on clean-label compatibility and natural formulations to meet regulatory and consumer demands. Strategic partnerships with dairy cooperatives and food processors help expand their regional presence. Some companies integrate digital tools for precision fermentation and process optimization. Emerging markets present new growth areas, pushing firms to localize culture development for traditional products. Capacity expansion and technology upgrades in Asia and Latin America are top priorities. Mergers, acquisitions, and licensing agreements also support their competitive positioning. Overall, differentiation through innovation, shelf stability, and regional adaptability shapes the competitive landscape.
Recent Developments
- In 2024, Danone announced a partnership with Novonesis to leverage their combined scientific expertise and create unique, sustainable dairy products with improved taste and texture, aligning with Danone's strategic focus on health and sustainability.
- In 2024, BDF Ingredients launched an innovative line of freeze-dried starter cultures for low-fat yogurt and sour cream, designed to maintain creamy texture and robust flavor while meeting demand for healthier products.
- In 2023, FrieslandCampina Ingredients launched several new products focusing on functional dairy applications, including the fermented ingredient Biotis® Fermentis, which combines whey proteins, probiotics, and prebiotics to target the gut-muscle axis for health-conscious consumers.
Report Coverage
The research report offers an in-depth analysis based on Application, Microorganism Type, Form and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for probiotic-rich dairy products will continue to drive culture innovation.
- Freeze-dried starter cultures will gain preference for their longer shelf life and export suitability.
- Functional strains with immunity and gut health benefits will see increased adoption.
- Plant-based dairy alternatives will create new demand for non-dairy compatible cultures.
- Regulatory approvals for novel strains will influence product development timelines.
- Regional customization of cultures will expand to meet local taste and texture preferences.
- Cold chain expansion in developing markets will support higher penetration of starter cultures.
- Industry partnerships between dairy processors and biotech firms will accelerate culture innovation.
- Clean-label and organic dairy trends will strengthen the demand for natural starter cultures.
- Investments in automated and precision fermentation systems will optimize culture application.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Probiotic and Functional Dairy Demand
Health-conscious consumers are increasingly seeking probiotic-rich and functional dairy products to support digestive and immune health, driving manufacturers to adopt advanced starter cultures that deliver proven health benefits.
Clean-Label and Organic Product Trends
The shift toward natural, minimally processed, and organic dairy products is boosting demand for biological fermentation agents, as consumers and regulators favor clean-label starter cultures over artificial additives.
Expansion of Industrial Dairy Processing
Growth in large-scale dairy production and global trade requires consistent, high-quality fermentation cultures to ensure product uniformity, safety, and extended shelf life across international supply chains.
Technological Advances in Culture Preservation
Innovations in freeze-drying and microencapsulation technologies are enhancing the stability, shelf life, and transportability of starter cultures, enabling broader market reach and reducing cold chain dependence.
Government Nutrition Programs and Dairy Fortification
Public health initiatives and government-backed nutrition programs in emerging markets are increasing the adoption of standardized starter cultures for fortified and safe dairy products, supporting mass distribution and improved nutrition.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dairy Starter Culture market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dairy Starter Culture Market projected to grow between 2025 and 2032?
Which Dairy Starter Culture market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dairy Starter Culture market?
Who are the leading companies in the Dairy Starter Culture Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Powder
- 1.2.3 Freeze-Dried
- 1.3 By Application
- 1.3.1 Cheese
- 1.3.2 Yogurt
- 1.3.3 Buttermilk
- 1.3.4 Butter
- 1.3.5 Cream
- 1.4 By Microorganism Type
- 1.4.1 Lactic Acid Bacteria
- 1.4.2 Yeasts
- 1.4.3 Molds
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,378 million → 2032: USD 2,179.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dairy Starter Culture Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dairy Starter Culture Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dairy Starter Culture Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dairy Starter Culture Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dairy Starter Culture Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dairy Starter Culture Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dairy Starter Culture Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dairy Starter Culture Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,378 million → 2032: USD 2,179.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dairy Starter Culture Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Powder
- 12.3.7.3 Freeze-Dried
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cheese
- 12.4.7.2 Yogurt
- 12.4.7.3 Buttermilk
- 12.4.7.4 Butter
- 12.4.7.5 Cream
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Microorganism Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Lactic Acid Bacteria
- 12.5.7.2 Yeasts
- 12.5.7.3 Molds
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dairy Starter Culture End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dairy Starter Culture Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dairy Starter Culture Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dairy Starter Culture Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 DuPont
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Chr. Hansen
- 18.4 FrieslandCampina
- 18.5 Danone
- 18.6 Kerry Group
- 18.7 Nestlé
- 18.8 Lallemand
- 18.9 Fonterra
- 18.10 Lactalis
- 18.11 Arla Foods
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

