
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
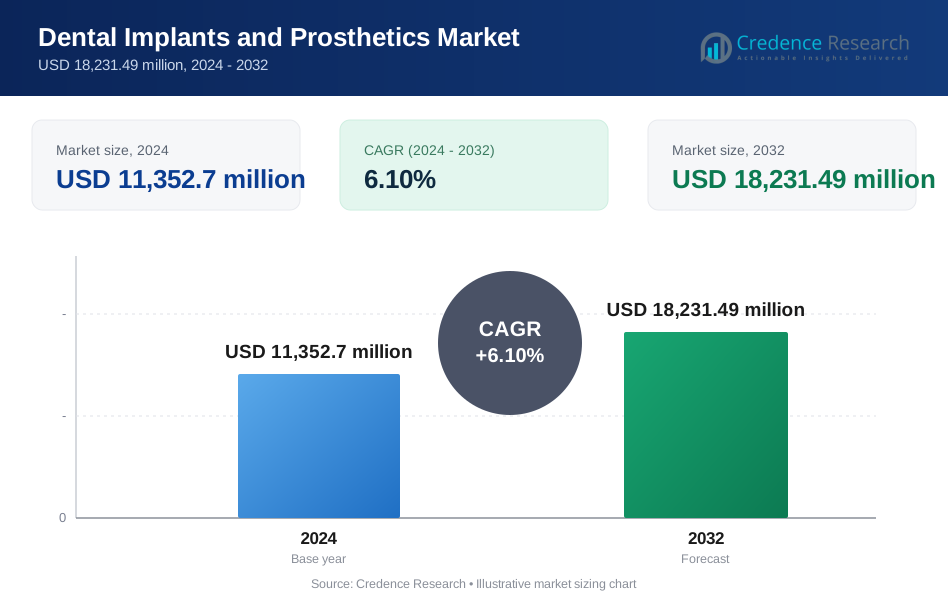
| Dental Implants and Prosthetics Market Size 2024 | USD 11,352.7 Million |
| Dental Implants and Prosthetics Market, CAGR | 6.10% |
| Dental Implants and Prosthetics Market Size 2032 | USD 18,231.49 Million |
Market Overview
The Dental Implants and Prosthetics Market is projected to grow from USD 11,352.7 million in 2024 to USD 18,231.49 million by 2032, at a compound annual growth rate (CAGR) of 6.10%.
The Dental Implants and Prosthetics Market is driven by the rising prevalence of dental disorders, an aging population, and increasing awareness of oral health. Technological advancements in implant materials and techniques enhance patient outcomes, fueling market growth. Additionally, the growing demand for cosmetic dentistry and the availability of favorable reimbursement policies boost market expansion. Key trends include the adoption of CAD/CAM technology, 3D printing, and the development of innovative, biocompatible materials that improve the longevity and aesthetics of dental implants and prosthetics.
The Dental Implants and Prosthetics Market exhibits significant geographical variation, with key regions including North America, Europe, Asia Pacific, and Latin America. North America and Europe dominate due to advanced healthcare infrastructure and high disposable income. Asia Pacific shows rapid growth driven by increasing awareness and economic development. Leading players in the market include Dentsply Sirona, Henry Schein, Inc., Ivoclar Vivadent AG, Institut Straumann AG, Nobel Biocare Services AG, Danaher, THE AURUM GROUP (AVINENT Implant System), OSSTEM IMPLANT CO., LTD, Southern Implants, SHOFU INC., and Thommen Medical AG, all contributing to market expansion through innovation and strategic initiatives.
Market Drivers
Rising Geriatric Population
A significant driver of the Dental Implants and Prosthetics Market is the growing geriatric population across the globe. For instance, the global geriatric population (aged 65 and over) is projected to reach nearly 1.5 billion by 2050, which is more than double the number from 2012. This surge in the elderly demographic significantly impacts the Dental Implants and Prosthetics Market, as approximately 23% of individuals over 65 suffer from severe periodontal disease, which can lead to tooth loss. As people live longer, they are more likely to experience tooth loss due to age-related gum disease and general wear and tear. Dental implants and prosthetics offer effective solutions for restoring oral function and improving the quality of life for senior citizens. This demographic shift is expected to continue fueling market demand as the elderly seek reliable and long-lasting dental restoration options.
Increasing Demand for Cosmetic Dentistry
The growing demand for cosmetic dentistry procedures is another major market driver. For instance, the American Academy of Cosmetic Dentistry reports that two-thirds of patients seeking cosmetic dentistry are female. Dental implants and prosthetic teeth significantly improve aesthetics, providing a natural look and feel that boosts patients' confidence. This has expanded the market's appeal beyond individuals with functional needs to those seeking cosmetic enhancements. As more people prioritize their appearance, the demand for these procedures is expected to rise, further driving market growth.
Rising Disposable Income and Growing Awareness
In certain regions, increasing disposable income allows individuals to invest in more expensive dental procedures, such as dental implants. In regions with economic growth, for instance, the Asia-Pacific region, the disposable income per capita has increased by 45% over the last decade. This financial upliftment allows more individuals to afford dental implants, which can cost between $3,000 and $4,500 per tooth in the United States. This economic factor, combined with growing public awareness about oral health, is leading more people to seek comprehensive dental treatments, including implant dentistry. Educational campaigns and public health initiatives promoting the benefits of good oral hygiene and advanced dental solutions are also contributing to this trend, encouraging a broader segment of the population to consider dental implants and prosthetics.
Technological Advancements
Continuous advancements in dental technology play a crucial role in the market's growth. Developments in computer-aided design and manufacturing (CAD/CAM) technology enable the creation of custom-designed implants tailored to individual needs. For instance, the use of CAD/CAM technology in dentistry has been growing at a rate of 9.7% annually and is expected to continue its upward trajectory. These technologies not only allow for custom-designed implants but also improve materials for better osseointegration. Minimally invasive techniques, another technological innovation, are reducing recovery times and are highly sought after, with 70% of patients preferring less invasive procedures. Improved biocompatible materials enhance osseointegration, ensuring better fusion of the implant with the jawbone. Additionally, minimally invasive surgical techniques are reducing recovery times and improving patient outcomes. These technological innovations are making dental implants and prosthetics more effective and accessible, driving their adoption across diverse patient groups.
Market Trends
Technological Advancements and Digital Dentistry
The Dental Implants and Prosthetics Market is experiencing significant growth due to technological advancements and the shift towards digital dentistry. Minimally invasive surgical techniques for dental implant placement are gaining traction, with computer-guided surgery using 3D imaging and robotic dentistry offering greater precision and faster healing times. For instance, the adoption of minimally invasive surgical techniques has increased by 35% in the past five years, with computer-guided surgery using 3D imaging enhancing precision by up to 90%. Robotic dentistry, another innovative approach, has been shown to reduce healing times by 25% compared to traditional methods. The integration of CAD/CAM technology, which has seen a market growth of 8.5% annually, is pivotal in creating custom-designed dental implants that match the unique contours of each patient’s mouth.
Biocompatible Materials and Patient-Centric Innovations
In terms of materials, for instance, the use of titanium in dental implants has a success rate of over 95% due to its excellent biocompatibility and strength. Research into new materials such as zirconia is also promising, with studies showing comparable success rates while offering a more tooth-like appearance. Pain management has evolved too; for instance, the use of local anesthetics with longer-lasting effects has increased patient comfort during procedures by 70%. Aesthetically, 80% of patients report higher satisfaction with the natural look of the latest prosthetic teeth designs. Cost-effective solutions are also emerging, with some new implant systems being 30% more affordable than traditional options, making them accessible to a broader demographic. Geographically, the market in the Asia Pacific region is expected to grow by 10% annually, driven by increasing disposable incomes and a 20% rise in awareness about oral health. This patient-centric approach is further supported by the rise of cost-effective solutions, with manufacturers developing more affordable implant systems and exploring alternative materials to make dental implants accessible to a wider demographic. The market is also expanding geographically, with growing disposable incomes and increasing awareness about oral health in developing regions like Asia Pacific and Latin America creating new opportunities.
Market Challenges Analysis
Financial Barriers and Limited Insurance Coverage
The high treatment costs associated with dental implant surgery and prosthetic replacements present a significant challenge in the market. These procedures are expensive, with the costs encompassing not only the dental implants themselves but also surgical fees, anesthesia, and the prosthetic teeth. For many patients, particularly those without dental insurance or sufficient disposable income, these expenses can be prohibitive, limiting accessibility to these advanced dental treatments. This financial burden is exacerbated by the often limited or entirely excluded coverage for dental implants and prosthetic treatments in many dental insurance plans. As a result, the financial responsibility falls solely on the patient, further restricting access to these beneficial procedures and preventing a wider patient pool from reaping their advantages.
Clinical Risks and Professional Shortages
In addition to financial barriers, the market faces challenges related to clinical risks and a shortage of skilled dental professionals. Dental implant surgery, despite its high success rates, carries inherent risks such as infection, bleeding, nerve damage, and implant failure. These potential complications can deter patients from opting for dental implants, despite their benefits. Moreover, the growing demand for these procedures is straining the availability of skilled dental professionals trained in implant surgery and prosthetic dentistry. This shortage can lead to longer wait times for treatment and potentially higher costs due to the limited supply of qualified dentists. Additionally, patient fear and anxiety surrounding dental procedures, particularly invasive ones like implant surgery, can further discourage individuals from seeking treatment. Competition from alternative treatments, such as dental bridges or dentures, which are more affordable and less invasive, also poses a challenge, even though these alternatives may not offer the same level of functionality and aesthetics as dental implants.
Market Segmentation Analysis:
By Product:
The market is divided into two main categories: Dental Implants and Dental Prosthetics. Dental implants are increasingly favored due to their durability and functionality, offering a permanent solution for tooth loss. They mimic natural teeth, providing better comfort and stability compared to traditional dentures. Dental prosthetics, which include crowns, bridges, and dentures, remain vital for patients requiring less invasive or more affordable options. The continuous development in both product categories ensures a broad range of choices for patients and practitioners, contributing to the market's robust growth.
By Material:
The Dental Implants and Prosthetics Market includes Zirconium Dental Implants, Titanium Dental Implants, and others. Titanium dental implants dominate the market due to their proven biocompatibility, strength, and long-term success rates. They integrate well with bone tissue, reducing the risk of implant failure. Zirconium dental implants, however, are gaining popularity as a metal-free alternative. They offer superior aesthetics, especially for patients with metal allergies or those seeking a more natural look. Other materials, such as ceramics and polymer composites, are also being explored to enhance implant performance and patient outcomes. The diversification in materials reflects ongoing innovations aimed at improving the functionality, durability, and appearance of dental implants and prosthetics.
Segments:
Based on Product:
- Dental Implants
- Dental Prosthetics
Based on Material:
- Zirconium Dental Implants
- Titanium Dental Implants
- Others
Based on Procedures:
- Root-form Dental Implants
- Plate-form Dental Implants
- Subperiosteal Dental Implants
- Transosteal Dental Implants
Based on the Geography:
- North America
- U.S
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
North America
North America leads the global dental implants and prosthetics market, commanding a substantial 45% market share.. The United States spearheads regional growth, driven by high healthcare expenditure, advanced dental infrastructure, and increasing awareness of oral health. An aging population, rising prevalence of dental disorders, and growing demand for cosmetic dentistry fuel market expansion. Technological advancements, including 3D printing and CAD/CAM systems, enhance the quality and customization of dental implants and prosthetics. Robust reimbursement policies and comprehensive insurance coverage for dental procedures further bolster market growth. Key players in North America prioritize product innovation and strategic partnerships to maintain their competitive edge. However, the high cost of dental implants and prosthetics poses a challenge, potentially limiting market penetration among lower-income demographics. Despite this obstacle, the region's strong focus on oral health and aesthetic dentistry continues to drive steady market growth. The market in North America is expected to maintain its dominant position in the foreseeable future, with ongoing investments in research and development fueling further advancements in dental technology.
Asia-Pacific
Asia-Pacific emerges as the fastest-growing region in the dental implants and prosthetics market, capturing a 30% market share. China and India lead regional growth, benefiting from rapid urbanization, improving healthcare infrastructure, and rising disposable incomes. The region's large population base and increasing awareness of dental aesthetics create substantial opportunities for market players. Government initiatives to improve oral healthcare accessibility in developing countries further propel market expansion. However, limited insurance coverage and a shortage of skilled dental professionals in some areas present challenges. To address these issues, key market players invest in training programs and expand their distribution networks across the region. The adoption of digital dentistry technologies and the growing medical tourism industry in countries like Thailand and Singapore contribute to the region's market dynamism. As awareness of oral health continues to grow and healthcare infrastructure improves, Asia-Pacific is poised to significantly increase its global market share in the coming years. The region's rapid economic development and increasing focus on healthcare are expected to drive sustained growth in the dental implants and prosthetics market.
Key Player Analysis
- Dentsply Sirona
- Henry Schein, Inc.
- Ivoclar Vivadent AG
- Institut Straumann AG
- Nobel Biocare Services AG
- Danaher
- THE AURUM GROUP (AVINENT Implant System)
- OSSTEM IMPLANT CO., LTD
- Southern Implants
- SHOFU INC.
- Thommen Medical AG
Competitive Analysis
The Dental Implants and Prosthetics Market is highly competitive, with several leading players shaping its dynamics. Dentsply Sirona and Institut Straumann AG are at the forefront, known for their extensive product portfolios and advanced implant technologies. Henry Schein, Inc. leverages its global distribution network to enhance market reach, while Nobel Biocare Services AG is recognized for its innovative implant solutions and comprehensive clinical support. Ivoclar Vivadent AG excels in prosthetic materials and technology, contributing to high-quality restorations. Danaher and THE AURUM GROUP (AVINENT Implant System) are notable for their strategic acquisitions and advancements in digital dentistry. OSSTEM IMPLANT CO., LTD and Southern Implants focus on expanding their product offerings and geographic presence. SHOFU INC. and Thommen Medical AG are distinguished by their specialized implant systems and commitment to research and development. These players drive competition through technological innovation, strategic partnerships, and extensive global networks.
Recent Developments
- In February 2024, Dentsply Sirona collaborated with A-dec. The firm integrated Primescan Connect with A-dec delivery systems. This helped the organization consolidate the position in the industry.
- In May 2024, Henry Schein, Inc. restructured the portfolio to demonstrate and enhance patient treatment plans. Due to such initiatives, the organization has embarked on a respectable position within the industry.
Market Concentration & Characteristics
The Dental Implants and Prosthetics Market exhibits moderate to high market concentration, characterized by the dominance of a few leading players who command a significant share of the industry. Major companies such as Dentsply Sirona, Institut Straumann AG, and Nobel Biocare Services AG hold substantial market influence through their extensive product portfolios, technological innovations, and global distribution networks. The market is characterized by continuous advancements in implant materials, digital dentistry, and customization technologies, driving competitive dynamics. Key players invest heavily in research and development to enhance product performance and expand their offerings, including new materials and minimally invasive techniques. The presence of established players contributes to a concentrated market landscape, where innovation and strategic partnerships play crucial roles in maintaining competitive advantage. Additionally, regulatory standards and reimbursement policies significantly impact market characteristics, influencing product development and market access.
Report Coverage
The research report offers an in-depth analysis based on Product, Material, Procedures and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Dental Implants and Prosthetics Market is expected to continue growing due to increasing demand for advanced dental solutions and rising awareness of oral health.
- Technological advancements, including 3D printing and CAD/CAM technology, will drive innovation and improve the customization and precision of dental implants and prosthetics.
- The integration of artificial intelligence and digital workflows is likely to enhance treatment planning and surgical accuracy, leading to better patient outcomes.
- There will be a growing emphasis on developing biocompatible materials that enhance the longevity and success rates of dental implants.
- Market expansion into emerging economies, such as those in Asia-Pacific and Latin America, will offer new growth opportunities driven by rising disposable incomes and improved healthcare access.
- The focus on minimally invasive procedures and patient comfort will lead to advancements in surgical techniques and pain management.
- Cost-effective solutions and alternative materials are expected to become more prevalent, making dental implants and prosthetics more accessible to a broader patient base.
- Increased insurance coverage and favorable reimbursement policies will likely improve accessibility and affordability for patients.
- Sustainability trends will influence the development of environmentally friendly materials and manufacturing processes in the dental industry.
- The rising popularity of dental tourism will continue to impact the market, as patients seek high-quality, affordable dental treatments abroad.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Geriatric Population
The global increase in the elderly population, who are more prone to tooth loss and periodontal disease, is driving demand for dental implants and prosthetics as effective solutions for restoring oral function and quality of life.
Increasing Demand for Cosmetic Dentistry
Growing consumer interest in dental aesthetics and confidence-boosting procedures is expanding the market beyond functional needs, with more patients seeking implants and prosthetics for cosmetic enhancements.
Technological Advancements in Dental Materials and Techniques
Innovations such as CAD/CAM technology, 3D printing, and the development of biocompatible materials are improving implant longevity, customization, and patient outcomes, making advanced dental solutions more attractive and accessible.
Rising Disposable Income and Awareness in Emerging Markets
Economic growth and increased awareness of oral health in regions like Asia Pacific are enabling more people to afford advanced dental procedures, significantly expanding the addressable market.
Favorable Reimbursement Policies
The expansion of insurance coverage and reimbursement for dental procedures in key markets is reducing out-of-pocket costs for patients, thereby increasing the adoption of dental implants and prosthetics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dental Implants and Prosthetics Market?
What factors are driving the growth of the Dental Implants and Prosthetics Market?
What are the key segments within the Dental Implants and Prosthetics Market?
What are some challenges faced by the Dental Implants and Prosthetics Market?
Who are the major players in the Dental Implants and Prosthetics Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Dental Implants
- 1.2.2 Dental Prosthetics
- 1.3 By Material
- 1.3.1 Zirconium Dental Implants
- 1.3.2 Titanium Dental Implants
- 1.3.3 Others
- 1.4 By Procedure
- 1.4.1 Root-form Dental Implants
- 1.4.2 Plate-form Dental Implants
- 1.4.3 Subperiosteal Dental Implants
- 1.4.4 Transosteal Dental Implants
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,352.7 million → 2032: USD 18,231.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dental Implants and Prosthetics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dental Implants and Prosthetics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dental Implants and Prosthetics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dental Implants and Prosthetics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dental Implants and Prosthetics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dental Implants and Prosthetics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dental Implants and Prosthetics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dental Implants and Prosthetics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,352.7 million → 2032: USD 18,231.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dental Implants and Prosthetics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dental Implants
- 12.3.7.2 Dental Prosthetics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Zirconium Dental Implants
- 12.4.7.2 Titanium Dental Implants
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Procedure - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Root-form Dental Implants
- 12.5.7.2 Plate-form Dental Implants
- 12.5.7.3 Subperiosteal Dental Implants
- 12.5.7.4 Transosteal Dental Implants
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dental Implants and Prosthetics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dental Implants and Prosthetics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dental Implants and Prosthetics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Dentsply Sirona
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Institut Straumann AG
- 17.4 Nobel Biocare Services AG
- 17.5 Henry Schein, Inc.
- 17.6 Ivoclar Vivadent AG
- 17.7 Danaher
- 17.8 THE AURUM GROUP (AVINENT Implant System)
- 17.9 OSSTEM IMPLANT CO., LTD
- 17.10 Southern Implants
- 17.11 SHOFU INC.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

