
Market Overview
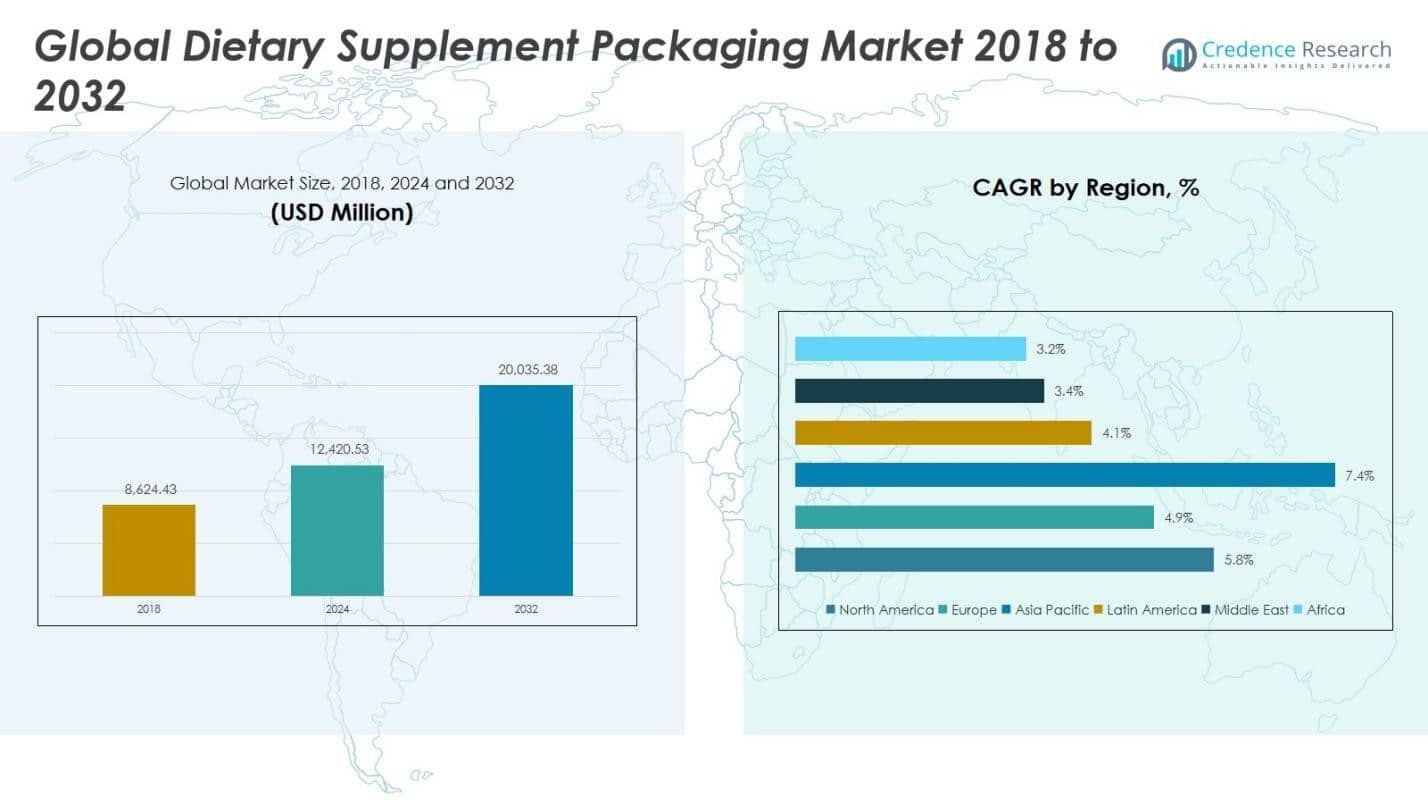
The Dietary Supplement Packaging Market size was valued at USD 8,624.43 million in 2018, growing to USD 12,420.53 million in 2024, and is anticipated to reach USD 20,035.38 million by 2032, at a CAGR of 5.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dietary Supplement Packaging Market Size 2024 | USD 12,420.53 Million |
| Dietary Supplement Packaging Market, CAGR | 5.73% |
| Dietary Supplement Packaging Market Size 2032 | USD 20,035.38 Million |
The competitive landscape of the Dietary Supplement Packaging Market is characterized by the presence of key players such as Amcor plc, Gerresheimer AG, Berry Global Inc., AptarGroup Inc., Alpha Packaging, Owens-Illinois Inc., and Sonoco Products Company. These companies focus on innovative, sustainable, and lightweight packaging solutions to meet the growing demand for dietary supplements. They invest in recyclable materials and advanced barrier technologies to enhance product protection and shelf life. Strategic collaborations and acquisitions further strengthen their market position and expand global reach. North America leads the Dietary Supplement Packaging Market, accounting for approximately 38% of the total share in 2024, driven by rising consumer health awareness, a well-established supplement industry, and strong adoption of eco-friendly packaging formats.
Market Insights
- The Dietary Supplement Packaging Market was valued at USD 12,420.53 million in 2024 and is projected to reach USD 20,035.38 million by 2032, growing at a CAGR of 5.73% during the forecast period. Plastic dominates the material segment with a 42% share, bottles lead the product segment at 38%, and tablets account for 33% of the formulation segment.
- Growth is driven by rising global health awareness and increasing adoption of dietary supplements, boosting demand for durable and safe packaging solutions. Expansion of e-commerce and direct-to-consumer channels further supports market growth by requiring protective, lightweight, and visually appealing packaging.
- Key trends include the shift toward sustainable and recyclable materials, increasing adoption of smart packaging technologies, and the rising popularity of personalized nutrition solutions that demand innovative, portion-controlled packaging.
- Competitive analysis shows leading players such as Amcor plc, Berry Global Inc., Gerresheimer AG, AptarGroup Inc., and Sonoco Products Company focusing on sustainability, product diversification, and strategic collaborations to strengthen market presence.
- Regionally, North America leads with a 43% share, followed by Europe at 27%, and Asia Pacific growing fastest at a CAGR of 7.4%, reflecting rising supplement consumption and adoption of innovative packaging formats.
Market Segmentation Analysis:
By Material: Plastic dominates the dietary supplement packaging market, accounting for nearly 42% of the total share in 2024. Its widespread use stems from its cost-effectiveness, lightweight nature, and excellent barrier properties that preserve product integrity. Plastic packaging formats such as PET and HDPE bottles remain the preferred choice for tablets, capsules, and powders due to their versatility and durability. Additionally, advancements in recyclable and bio-based plastics are driving sustainable adoption. However, the increasing demand for eco-friendly alternatives is gradually boosting the use of biodegradable and paper-based materials in premium supplement packaging.
For instance, for biodegradable, paper-based packaging, Sonoco Europe offers innovative solutions like the GREENCAN® and EnviroCan® rigid paperboard containers made from over 90% paper content.
By Product: Bottles hold the largest share in the dietary supplement packaging market, representing around 38% of the global segment in 2024. Their dominance is attributed to their suitability for diverse supplement forms such as tablets, capsules, and powders. Bottles offer superior protection against moisture and oxygen, extending shelf life while supporting branding through labeling and design flexibility. The growing trend of reusable and recyclable bottles, particularly PET and glass variants, further supports sustainability goals. Meanwhile, flexible packaging formats like pouches and sachets are gaining traction in single-serve and travel-friendly supplement applications.
For instance, NaKu's bottles made from biodegradable, plant-based materials, offering sustainable packaging options for dietary supplements with capacities tailored to powders, tablets, and liquids.
By Formulation: Tablets lead the dietary supplement packaging market, capturing approximately 33% of the total segment share in 2024. Their popularity is driven by dosage precision, long shelf life, and convenience in storage and transportation. Packaging solutions for tablets often include blister packs and HDPE bottles, ensuring optimal protection from light, humidity, and contamination. The rising consumer inclination toward vitamin and mineral tablets for daily wellness has reinforced this segment’s growth. Additionally, innovations in child-resistant closures and tamper-evident packaging further enhance safety and compliance standards in the tablet packaging category.
Key Growth Drivers
Rising Health Awareness and Nutritional Supplement Adoption
Growing global awareness of preventive healthcare and nutrition is a major driver for the dietary supplement packaging market. Consumers increasingly rely on supplements to support immunity, fitness, and overall well-being. This surge in demand has led to higher production of vitamins, minerals, and protein supplements, driving the need for reliable, durable, and visually appealing packaging. Brands are focusing on user-friendly formats such as resealable pouches and child-safe bottles to enhance convenience and safety, reinforcing the role of innovative packaging in maintaining consumer trust and product integrity.
For instance, Vitaquest offers child-resistant bottles and biodegradable pouches for vitamin supplements, enhancing safety and sustainability while meeting consumer demand for eco-friendly packaging.
Expansion of E-Commerce and Direct-to-Consumer Channels
The rapid rise of online supplement sales is fueling demand for protective and lightweight packaging solutions. E-commerce platforms require packaging that ensures product safety during transit while maintaining visual appeal for digital presentation. Manufacturers are adopting compact, tamper-proof, and eco-friendly packaging to meet these evolving requirements. Additionally, subscription-based supplement models are prompting brands to focus on consistent, premium, and branded packaging designs that boost customer retention and reinforce identity across digital touchpoints, positioning packaging as a critical factor in the online retail strategy.
For instance, Ritual’s Essential for Women multivitamin is packaged in bottles made from 100% post-consumer recycled (PCR) PET plastic, coupled with caps made from recyclable polypropylene, reflecting a strong commitment to sustainability while ensuring product safety during transit.
Growing Focus on Sustainable and Recyclable Packaging
Sustainability has become a defining growth driver, with consumers and regulatory bodies pressuring manufacturers to adopt environmentally responsible packaging solutions. Companies are increasingly using biodegradable materials, recyclable plastics, and paper-based alternatives to reduce carbon footprints. Eco-labeling and minimalistic designs are also gaining popularity, helping brands align with global sustainability goals. This shift toward green packaging not only enhances brand perception but also opens new opportunities in regions where environmental compliance and circular economy principles are becoming central to consumer purchasing decisions.
Key Trends and Opportunities
Integration of Smart and Interactive Packaging
Smart packaging technologies such as QR codes, NFC tags, and freshness indicators are transforming consumer engagement and transparency in the dietary supplement sector. These technologies enable users to verify product authenticity, access dosage information, and track nutritional benefits. Brands leveraging such packaging enhance consumer trust and loyalty while improving traceability across the supply chain. The integration of digital interaction with packaging also supports regulatory compliance and product differentiation, creating a more informed and interactive consumer experience in an increasingly digitalized market.
For instance, Nestlé integrates QR codes on its product packaging to provide consumers detailed information about ingredient sourcing and product life cycle, enhancing brand transparency and consumer trust.
Shift Toward Personalized Nutrition Solutions
The growing preference for personalized health and nutrition creates an opportunity for tailored packaging designs that cater to individual supplement needs. Brands are introducing portion-controlled packaging, multi-compartment formats, and easy-to-use sachets suited for daily intake. This trend aligns with the rise of customized supplement programs and subscription boxes, allowing packaging to enhance both functionality and personalization. As consumers seek convenience and precision, companies offering adaptive, portable, and innovative packaging solutions are positioned to capture emerging opportunities in this evolving segment.
For instance, OK Capsule offers private-label supplements in customizable, flexible packs that allow health-tech companies to deliver personalized supplements without large upfront investments.
Key Challenges
Stringent Regulatory and Labeling Requirements
Compliance with complex and region-specific packaging regulations presents a significant challenge for manufacturers. Dietary supplement packaging must meet strict labeling, ingredient disclosure, and tamper-evident requirements to ensure consumer safety and transparency. Variations in international standards often lead to higher operational costs and longer product launch timelines. Companies must invest in compliant design systems, accurate labeling, and sustainable materials that meet FDA, EFSA, and other regional guidelines while maintaining cost efficiency and brand consistency across multiple markets.
Rising Raw Material and Production Costs
Fluctuating prices of raw materials such as plastics, glass, and aluminum have intensified cost pressures across the dietary supplement packaging industry. High energy expenses, supply chain disruptions, and increasing demand for eco-friendly alternatives have further compounded these challenges. Manufacturers are adopting lightweight designs, local sourcing, and automation technologies to manage costs while sustaining product quality. Despite these efforts, balancing affordability with sustainability and performance remains a persistent obstacle for producers aiming to maintain profitability in a highly competitive market landscape.
Regional Analysis
North America
North America holds the dominant position in the global dietary supplement packaging market, accounting for 43% of the market share in 2024. The market grew from USD 3,780.48 million in 2018 to USD 5,388.16 million in 2024 and is projected to reach USD 8,715.60 million by 2032, registering a CAGR of 5.8%. Growth in the region is driven by high supplement consumption in the United States and Canada, strong health awareness, and expanding e-commerce distribution. The presence of major supplement brands and continuous innovation in sustainable and child-resistant packaging materials further strengthen North America’s leadership.
Europe
Europe represents a significant share of the dietary supplement packaging market, holding around 27% of the global market in 2024. The market increased from USD 2,455.12 million in 2018 to USD 3,408.72 million in 2024, and is projected to reach USD 5,178.00 million by 2032, at a CAGR of 4.9%. Growth is fueled by rising health consciousness, aging populations, and regulatory focus on sustainable and recyclable packaging. Countries such as Germany, France, and the UK lead regional demand, with strong consumer preference for eco-friendly and premium packaging formats that align with European sustainability goals.
Asia Pacific
Asia Pacific is the fastest-growing region in the dietary supplement packaging market, expanding at a CAGR of 7.4% and capturing 20% of the global market share in 2024. The market rose from USD 1,597.54 million in 2018 to USD 2,501.12 million in 2024, and is anticipated to reach USD 4,588.29 million by 2032. The region’s growth is driven by increasing supplement consumption in China, Japan, India, and South Korea, supported by rising disposable incomes and urban health awareness. Local manufacturers are investing in cost-effective, biodegradable, and lightweight packaging solutions to cater to the rapidly expanding nutraceutical industry.
Latin America
Latin America holds 5% of the global dietary supplement packaging market in 2024, expanding from USD 398.75 million in 2018 to USD 566.96 million in 2024, and projected to reach USD 807.17 million by 2032, growing at a CAGR of 4.1%. Market growth is primarily supported by increasing consumer spending on dietary supplements and expanding retail channels across Brazil, Mexico, and Chile. Packaging manufacturers are focusing on cost-efficient and tamper-resistant formats to meet rising demand, while gradual adoption of eco-friendly materials is shaping the region’s transition toward sustainable packaging practices.
Middle East
The Middle East dietary supplement packaging market accounted for 3% of the global share in 2024, growing from USD 235.84 million in 2018 to USD 309.76 million in 2024, and expected to reach USD 419.52 million by 2032, with a CAGR of 3.4%. The region’s growth is supported by rising awareness of preventive healthcare and growing consumption of vitamins and herbal supplements. Packaging companies are introducing durable and heat-resistant materials suitable for the region’s climatic conditions. Countries such as the UAE and Saudi Arabia are witnessing growing demand for premium and attractively designed supplement packaging.
Africa
Africa represents a smaller yet steadily developing segment, accounting for 2% of the global dietary supplement packaging market in 2024. The market increased from USD 156.70 million in 2018 to USD 245.81 million in 2024, and is forecasted to reach USD 326.79 million by 2032, registering a CAGR of 3.2%. The expansion is driven by improving healthcare access, growing awareness of nutritional supplements, and the gradual rise of local manufacturing in South Africa and Nigeria. Packaging innovation is centered on affordability and shelf-life enhancement, with opportunities emerging for recyclable and lightweight packaging materials in the long term.
Market Segmentations:
By Material
- Plastic
- Glass
- Paper & Paperboard
- Aluminum Foil
- Biodegradable Material
By Product
- Bottles
- Blister Packs
- Pouches
- Stick Packs
- Sachets
- Jars & Tubs
By Formulation
- Tablets
- Capsules
- Powders
- Syrups
- Softgels
- Gummies
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Dietary Supplement Packaging Market features leading players such as Amcor plc, Gerresheimer AG, Berry Global Inc., AptarGroup Inc., Alpha Packaging, Owens-Illinois Inc., and Sonoco Products Company. These companies focus on strategic partnerships, sustainable innovations, and product diversification to strengthen their global footprint. Amcor and Berry Global are advancing eco-friendly plastic packaging solutions, while Gerresheimer and Owens-Illinois emphasize premium glass packaging for high-end supplements. Manufacturers are increasingly adopting recyclable and biodegradable materials to align with sustainability goals and meet evolving consumer preferences. The market also witnesses growing investments in smart packaging technologies and tamper-evident closures to enhance product safety and authenticity. Intense competition encourages continuous innovation in design flexibility, lightweight structures, and digital printing for better brand differentiation. Furthermore, regional players are expanding their presence through mergers and acquisitions, enhancing capacity, and targeting emerging economies with cost-efficient, sustainable packaging alternatives.
Key Player Analysis
- Amcor plc (including former Bemis operations)
- Berry Global, Inc. (including Altium Packaging)
- Constantia Flexibles Group GmbH
- Sonoco Products Company
- Gerresheimer AG
- Owens-Illinois, Inc. (O-I Glass)
- AptarGroup, Inc.
- Alpha Packaging
- TricorBraun Holdings, Inc.
- Glenroy, Inc.
- Comar, LLC
- Graham Packaging Company
- ePac Holdings, LLC
- Law Print & Packaging Management Ltd.
- MPS (Molded Packaging Solutions)
- OPM Labels
- Container and Packaging Supply, Inc.
- Assemblies Unlimited
- Eagle Flexible Packaging
- Elis Packaging Solutions
- Others
Recent Developments
- In 2025, Amcor plc completed the acquisition of Berry Global Group, Inc., a move that strengthened its position in consumer and healthcare packaging markets, including dietary supplement packaging.
- In April 2025, TopGum Industries Ltd. (Israel) acquired Island Abbey Nutritionals (Canada), a CDMO specialising in supplement gummies & lozenges.
- On October 7 2025, NSF International announced it acquired Cambium Analytica, a specialist in analytical testing & development for natural food, beverage and dietary-supplement brands.
- In April 2024, Blue Ocean Closures launched a fiber-based screw cap designed for vitamin supplement bottles, particularly for Great Earth’s rPET packaging line. This innovation marked a significant step toward sustainable packaging solutions in the supplement industry.
Report Coverage
The research report offers an in-depth analysis based on Material, Product, Formulation and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by rising global health and wellness awareness.
- Sustainable and recyclable packaging materials will become a central focus for manufacturers.
- Smart packaging technologies will enhance product transparency and consumer engagement.
- The expansion of e-commerce will boost demand for durable and lightweight packaging solutions.
- Personalized nutrition trends will drive innovation in portion-controlled and customized packaging.
- Regulatory compliance will shape material selection and labeling standards across regions.
- Flexible packaging formats like pouches and sachets will gain popularity for on-the-go consumption.
- Investments in biodegradable materials will increase to meet environmental goals.
- Emerging markets in Asia Pacific and Latin America will present new growth opportunities.
- Collaboration between supplement brands and packaging innovators will define the industry’s competitive edge.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health Awareness and Nutritional Supplement Adoption
Increasing global focus on preventive healthcare and wellness is driving higher consumption of dietary supplements, which in turn boosts demand for reliable, safe, and visually appealing packaging solutions tailored to supplement products.
Expansion of E-Commerce and Direct-to-Consumer Channels
The growth of online supplement sales requires packaging that is protective, lightweight, and visually attractive for digital retail, prompting manufacturers to innovate with tamper-proof, eco-friendly, and branded packaging formats.
Growing Focus on Sustainable and Recyclable Packaging
Consumer and regulatory pressure for environmentally responsible packaging is accelerating the adoption of biodegradable, recyclable, and paper-based materials, helping brands align with sustainability goals and enhance market appeal.
Integration of Smart and Interactive Packaging
The adoption of smart packaging technologies such as QR codes and freshness indicators is enhancing product transparency, authenticity, and consumer engagement, differentiating brands and supporting regulatory compliance.
Shift Toward Personalized Nutrition Solutions
The trend toward personalized health and nutrition is driving demand for portion-controlled, customizable, and innovative packaging formats, enabling brands to cater to individual supplement regimens and subscription models.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Dietary Supplement Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dietary Supplement Packaging Market projected to grow between 2025 and 2032?
Which Dietary Supplement Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dietary Supplement Packaging Market?
Who are the leading companies in the Dietary Supplement Packaging Market?
Which region commanded the largest share of the Dietary Supplement Packaging Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Bottles
- 1.2.2 Blister Packs
- 1.2.3 Pouches
- 1.2.4 Stick Packs
- 1.2.5 Sachets
- 1.2.6 Jars & Tubs
- 1.3 By Material
- 1.3.1 Plastic
- 1.3.2 Glass
- 1.3.3 Paper & Paperboard
- 1.3.4 Aluminum Foil
- 1.3.5 Biodegradable Material
- 1.4 By Formulation
- 1.4.1 Tablets
- 1.4.2 Capsules
- 1.4.3 Powders
- 1.4.4 Syrups
- 1.4.5 Softgels
- 1.4.6 Gummies
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,420.53 million → 2032: USD 20,035.38 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dietary Supplement Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dietary Supplement Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dietary Supplement Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dietary Supplement Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dietary Supplement Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dietary Supplement Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dietary Supplement Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dietary Supplement Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,420.53 million → 2032: USD 20,035.38 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dietary Supplement Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bottles
- 12.3.7.2 Blister Packs
- 12.3.7.3 Pouches
- 12.3.7.4 Stick Packs
- 12.3.7.5 Sachets
- 12.3.7.6 Jars & Tubs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Plastic
- 12.4.7.2 Glass
- 12.4.7.3 Paper & Paperboard
- 12.4.7.4 Aluminum Foil
- 12.4.7.5 Biodegradable Material
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Formulation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Tablets
- 12.5.7.2 Capsules
- 12.5.7.3 Powders
- 12.5.7.4 Syrups
- 12.5.7.5 Softgels
- 12.5.7.6 Gummies
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dietary Supplement Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dietary Supplement Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dietary Supplement Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amcor plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Berry Global Inc.
- 17.4 Gerresheimer AG
- 17.5 AptarGroup Inc.
- 17.6 Sonoco Products Company
- 17.7 Owens-Illinois Inc. (O-I Glass)
- 17.8 Alpha Packaging
- 17.9 TricorBraun Holdings Inc.
- 17.10 Constantia Flexibles Group GmbH
- 17.11 Graham Packaging Company
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

