
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Digital Signature Software Market Size 2024 | USD 5460 million |
| Digital Signature Software Market, CAGR | 33.1% |
| Digital Signature Software Market Size 2032 | USD 53779.54 million |
Market Overview:
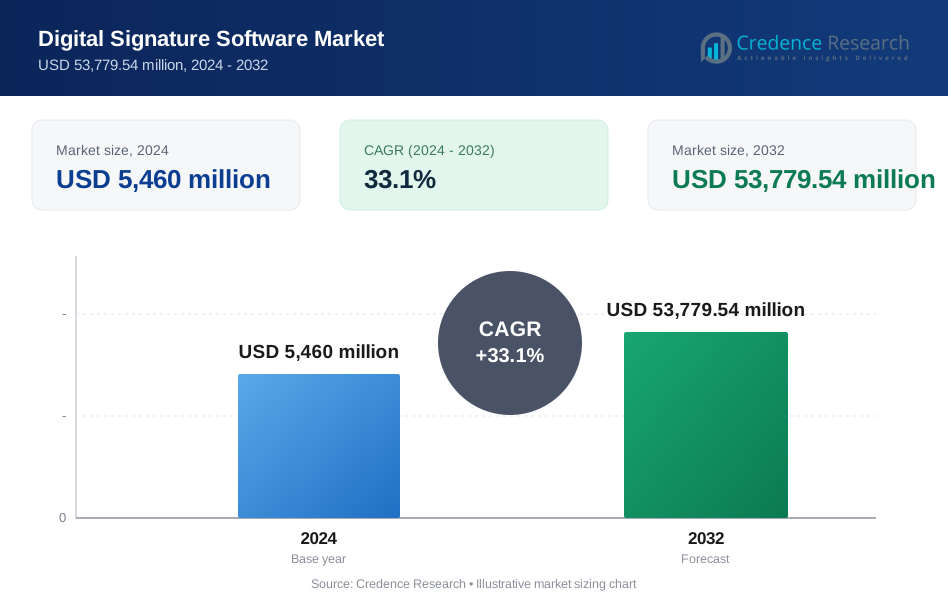
The Digital Signature Software Market is projected to grow from USD 5460 million in 2024 to an estimated USD 53779.54 million by 2032, with a compound annual growth rate (CAGR) of 33.1% from 2024 to 2032.
The Digital Signature Software Market drivers include the rising demand for enhanced security and authentication in digital transactions, driven by the global shift towards digitalization. As organizations increasingly adopt remote work practices, the need for secure digital document signing solutions has become paramount. Additionally, the growing regulatory requirements for data protection and compliance, such as the General Data Protection Regulation (GDPR) in Europe and the Electronic Signatures in Global and National Commerce (E-SIGN) Act in the United States, are pushing businesses to implement digital signature software. The increasing use of cloud-based solutions and the integration of digital signatures with existing enterprise software systems are further propelling market growth. Moreover, the need to reduce paper usage and streamline business processes is leading organizations to adopt digital signatures, contributing to the market's expansion.
Regional analysis reveals that North America dominates the Digital Signature Software Market, accounting for the largest market share due to the early adoption of digital technologies and stringent regulatory frameworks. The United States, in particular, is a key market, driven by the widespread adoption of digital signatures in government, finance, and healthcare sectors. Europe follows closely, with significant growth observed in countries like Germany, the UK, and France, where strong data protection regulations and the increasing digitalization of business processes are driving demand. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, fueled by the rapid adoption of digital technologies, government initiatives promoting digital transformation, and the growing awareness of data security. Emerging markets in Latin America and the Middle East & Africa are also anticipated to offer substantial growth opportunities as businesses in these regions increasingly recognize the benefits of digital signature software for enhancing operational efficiency and compliance.
Market Drivers:
Rising Demand for Secure and Efficient Document Management:
The increasing demand for secure and efficient document management solutions is a significant driver of the Digital Signature Software Market. As businesses continue to digitize their operations, the need to ensure the integrity, authenticity, and security of digital documents has become critical. Digital signatures provide a reliable solution for verifying the identity of signatories and ensuring that documents have not been altered after signing. This capability is particularly crucial in industries such as finance, healthcare, and legal services, where the confidentiality and authenticity of documents are paramount. For example, DocuSign, a leading digital signature provider, has been widely adopted in the healthcare industry to ensure the secure handling of patient records. According to a study by DocuSign, e-signature adoption can lead to a 28% faster time to revenue, 26% cost savings, and 19% revenue gains. Similarly, Adobe Sign is used by legal firms to streamline contract management processes, enhancing both security and efficiency. As a result, organizations across various sectors are increasingly adopting digital signature software to streamline their document management processes while enhancing security.
Regulatory Compliance and Legal Recognition:
Regulatory compliance and legal recognition of digital signatures are key factors driving the growth of the Digital Signature Software Market. Governments and regulatory bodies worldwide have implemented stringent regulations that mandate the use of secure digital signatures for electronic transactions and document management. For instance, the General Data Protection Regulation (GDPR) in Europe and the Electronic Signatures in Global and National Commerce (E-SIGN) Act in the United States have established clear guidelines for the use of digital signatures, providing them with the same legal status as handwritten signatures. These regulations not only ensure the legal enforceability of digital signatures but also compel organizations to adopt compliant solutions, thereby driving market demand.
Increasing Adoption of Cloud-Based Solutions:
The growing adoption of cloud-based solutions is another significant driver of the Digital Signature Software Market. Cloud-based digital signature software offers numerous advantages, including scalability, cost-effectiveness, and accessibility, making it an attractive option for businesses of all sizes. As organizations increasingly shift to cloud-based infrastructures, the integration of digital signature solutions with existing cloud platforms has become seamless, enabling businesses to easily implement and manage these solutions across their operations. The flexibility of cloud-based digital signatures allows users to sign documents from any location, facilitating remote work and enhancing productivity. This trend is particularly relevant in the current global landscape, where remote and hybrid work models are becoming the norm.
Growing Focus on Environmental Sustainability:
The growing focus on environmental sustainability is also contributing to the adoption of digital signature software. As businesses strive to reduce their environmental footprint, the move away from paper-based processes towards digital solutions is gaining momentum. Digital signatures eliminate the need for physical paperwork, reducing paper consumption, storage requirements, and associated costs. For example, Certinal’s eSignature solutions have been shown to save thousands of trees and millions of gallons of water annually by eliminating the need for paper. This shift not only aligns with corporate sustainability goals but also enhances operational efficiency by accelerating document workflows and reducing turnaround times. As more organizations prioritize sustainability, the demand for digital signature solutions is expected to increase, further driving market growth. The combination of environmental benefits and operational efficiencies makes digital signature software a compelling choice for businesses seeking to modernize their processes while contributing to a greener future. For instance, according to GlobalSign, adopting e-signatures contributes to environmental conservation, potentially saving 2.5 billion trees over 20 years.
Market Trends:
Increasing Integration with Advanced Technologies:
One of the prominent trends in the Digital Signature Software Market is the increasing integration of advanced technologies such as blockchain, artificial intelligence (AI), and machine learning (ML). Blockchain technology, in particular, is gaining traction for its ability to enhance the security and transparency of digital signatures. By providing a decentralized and immutable ledger, blockchain ensures that digital signatures cannot be tampered with, thereby adding an extra layer of security. AI and ML are also being leveraged to automate and optimize the digital signing process, improving accuracy and efficiency. These technologies are transforming digital signature solutions into more robust and intelligent systems, catering to the evolving needs of businesses.
Growing Adoption in Small and Medium-Sized Enterprises (SMEs):
The growing adoption of digital signature software among small and medium-sized enterprises (SMEs) is another significant trend shaping the market. Historically, digital signature solutions were predominantly used by large enterprises with extensive document management needs. However, as the technology has become more accessible and affordable, SMEs are increasingly recognizing the benefits of digital signatures for streamlining their operations. The rise of cloud-based solutions has further facilitated this adoption, allowing SMEs to implement digital signature software without the need for significant upfront investments. This trend is expected to continue as SMEs look for cost-effective ways to enhance efficiency and comply with regulatory requirements.
Expansion of Remote Work and Digital Transformation:
The expansion of remote work and the broader digital transformation of businesses are driving the adoption of digital signature software. The COVID-19 pandemic accelerated the shift towards remote work, highlighting the need for secure and efficient digital tools that enable business continuity. Digital signature software has become a critical component of this digital transformation, allowing organizations to maintain secure and legally binding document workflows regardless of physical location. For instance, according to a report by Adobe, 60% of respondents stated that digital solutions like e-signatures support business resilience, with adoption rates accelerating across regions and industries. As remote work becomes a permanent feature for many companies, the demand for digital signature solutions that support flexible and distributed work environments is expected to grow. This trend underscores the importance of digital signatures in facilitating modern, agile business operations.
Emphasis on User Experience and Ease of Integration:
Another key trend in the Digital Signature Software Market is the increasing emphasis on user experience and ease of integration. As businesses seek to implement digital signature solutions across their operations, there is a growing demand for platforms that are not only secure but also user-friendly and easy to integrate with existing systems. Vendors are responding by developing intuitive interfaces and offering seamless integration with popular document management systems, enterprise resource planning (ERP) platforms, and customer relationship management (CRM) tools. For example, SignWell is praised for its simplicity and effectiveness, making it easy for users to upload documents, add custom fields, and collect legally binding electronic signatures. According to a survey by Fujifilm, 67% of respondents benefit from an increase in efficiency, 65% from an increase in time savings, and 60% find it easier to prepopulate documents with data. This focus on user experience and integration capabilities is making digital signature software more accessible to a wider range of users, driving adoption across various industries and organizational sizes.
Market Restraints and Challenges:
High Implementation Costs and Resource Requirements:
One of the key restraints in the Digital Signature Software Market is the high implementation costs and resource requirements, particularly for small and medium-sized enterprises (SMEs). While digital signature solutions offer significant long-term benefits, the initial costs associated with acquiring the software, integrating it with existing systems, and training employees can be substantial. Additionally, the ongoing costs for maintenance, support, and upgrades can strain the budgets of smaller organizations. These financial barriers may deter some businesses from fully adopting digital signature solutions, limiting market growth, especially in cost-sensitive markets.
Security Concerns and Data Privacy Issues:
Security concerns and data privacy issues also pose significant challenges to the Digital Signature Software Market. Despite the advanced security features offered by digital signature solutions, such as encryption and authentication, there remains a risk of cyberattacks and data breaches. The increasing sophistication of cyber threats raises concerns about the vulnerability of digital signature systems, particularly in highly regulated industries like finance and healthcare, where data protection is paramount. Additionally, varying data privacy regulations across different regions can complicate the deployment of digital signature solutions, requiring organizations to navigate complex compliance landscapes. These security and privacy challenges can create hesitation among potential users, slowing down the adoption of digital signature software.
Resistance to Change and Lack of Awareness:
Resistance to change and a lack of awareness about the benefits of digital signature solutions are further challenges in the market. Many organizations, especially those in traditional industries, continue to rely on paper-based processes due to familiarity and perceived reliability. This resistance to adopting new technologies can be a significant barrier to the widespread adoption of digital signatures. Furthermore, in some regions, there is still a lack of awareness about the legal validity and potential advantages of digital signatures, which can hinder market penetration. Overcoming these challenges requires ongoing education and advocacy to demonstrate the value and effectiveness of digital signature solutions in improving operational efficiency and ensuring compliance.
Market Segmentation Analysis:
By deployment, the market is divided into cloud and on-premises solutions. Cloud-based digital signature software is gaining traction due to its scalability, cost-effectiveness, and ease of access, making it particularly appealing to small and medium-sized enterprises (SMEs). On-premises solutions, however, remain preferred by organizations with strict data security requirements, such as large enterprises and those in highly regulated industries.
By enterprise type, the market caters to both SMEs and large enterprises. SMEs are increasingly adopting digital signature software to streamline operations and reduce costs, while large enterprises utilize these solutions for their robust security features and ability to manage high volumes of digital transactions.
By level, the market is categorized into Advanced Electronic Signatures (AES) and Qualified Electronic Signatures (QES). AES offers a higher level of security and is commonly used across various industries, while QES, which provides the highest level of legal assurance, is often mandated in sectors with stringent regulatory requirements.
By industry, the digital signature software market serves a wide array of sectors, including BFSI (Banking, Financial Services, and Insurance), IT & Telecom, Government, Healthcare & Life Sciences, Defense & Legal, Retail, Real Estate, and others such as Education. The BFSI and government sectors are leading adopters due to the high importance of document security and regulatory compliance, while the healthcare and IT sectors are rapidly adopting these solutions to enhance operational efficiency and data protection. This segmentation highlights the versatility and critical role of digital signature software in ensuring secure and efficient digital transactions across various industries.
Segmentation:
By Deployment
- Cloud
- On-Premises
By Enterprise Type
- SMEs
- Large Enterprises
By Level
- Advanced Electronic Signatures (AES)
- Qualified Electronic Signatures (QES)
By Industry
- BFSI
- IT & Telecom
- Government
- Healthcare & Life Science
- Defense & Legal
- Retail
- Real Estate
- Others (Education)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America: Market Leader with Significant Share
North America dominates the Digital Signature Software Market, accounting for approximately 40% of the global market share. This leadership is primarily driven by the early adoption of digital technologies and the presence of a robust regulatory framework that mandates the use of secure digital signatures across various industries. The United States, in particular, plays a critical role in this dominance, with widespread adoption of digital signature software in sectors such as finance, healthcare, and government. The Electronic Signatures in Global and National Commerce (E-SIGN) Act, which provides digital signatures with the same legal standing as handwritten ones, has been a major catalyst for growth in the region. Additionally, the presence of key market players and ongoing technological advancements further contribute to North America's leading position.
Europe: Strong Growth Driven by Regulatory Compliance
Europe holds the second-largest share in the Digital Signature Software Market, representing about 30% of the global market. The region’s growth is significantly influenced by stringent data protection regulations, such as the General Data Protection Regulation (GDPR), which emphasizes the importance of secure digital transactions and document management. Countries like Germany, the United Kingdom, and France are at the forefront of this market, driven by the need to comply with these regulations and the increasing digitalization of business processes. Moreover, the European Union's strong focus on fostering digital innovation and promoting secure e-commerce practices is expected to further propel the adoption of digital signature software across the region.
Asia-Pacific: Fastest Growing Region
The Asia-Pacific region is expected to witness the fastest growth in the Digital Signature Software Market, with a projected market share of around 20%. This rapid expansion is fueled by the growing adoption of digital technologies, increasing government initiatives promoting digital transformation, and the rising awareness of data security. Countries such as China, India, Japan, and South Korea are leading this growth, driven by the burgeoning e-commerce sector, the expansion of the financial services industry, and the adoption of remote work practices. Additionally, the region’s large population base and the increasing penetration of the internet and mobile devices are creating a substantial demand for digital signature solutions, further accelerating market growth.
Rest of the World: Emerging Opportunities
The Rest of the World, including Latin America, the Middle East, and Africa, accounts for the remaining 10% of the global Digital Signature Software Market. These regions are gradually adopting digital signature solutions, driven by the expansion of digital infrastructure and the increasing focus on regulatory compliance. In Latin America, countries like Brazil and Mexico are seeing growing adoption of digital signatures, particularly in the financial and government sectors. In the Middle East and Africa, government initiatives aimed at digital transformation and enhancing cybersecurity are contributing to the market’s growth. While these regions currently hold a smaller market share, they present significant opportunities for future expansion as digital adoption continues to rise and regulatory landscapes evolve.
Key Player Analysis:
- Adobe, Inc. (U.S.)
- OneSpan, Inc. (U.S.)
- DocuSign, Inc. (U.S.)
- Thales Group (France)
- ASSA ABLOY (Sweden)
- GlobalSign, Inc. (Belgium)
- Entrust Corporation (U.S.)
- Ascertia Limited (Surrey)
- SIGNiX, Inc. (U.S.)
- IDEMIA (France)
Competitive Analysis:
The Digital Signature Software Market is highly competitive, with several key players vying for market dominance by offering innovative and secure solutions. DocuSign, Adobe Sign, and SIGNiX are among the market leaders, leveraging their strong brand recognition, extensive customer bases, and robust product offerings to maintain their competitive edge. These companies focus on enhancing user experience, integrating advanced technologies like blockchain and AI, and ensuring compliance with global regulatory standards to attract and retain customers. Additionally, smaller and regional players are entering the market, offering niche solutions tailored to specific industries or regulatory requirements. The market's competitive landscape is further intensified by the increasing demand for cloud-based solutions and the growing adoption of digital signatures in emerging markets. Continuous innovation, strategic partnerships, and expansion into new regions are critical strategies for companies aiming to strengthen their position in this rapidly growing market.
Recent Developments:
- In February 2023, Zoho enhanced its Zoho Sign service specifically for Independent Software Vendors (ISVs) and Original Equipment Manufacturers (OEMs). This update allows software vendors and manufacturers to integrate Zoho's digital signature capabilities directly into their products. The service now includes robust APIs, mobile SDKs for seamless app integration, Single Sign-On (SSO) authentication, and extensive customization options for branding, helping businesses reinforce their brand identity.
- In January 2023, DocuSign partnered with TechnoBind to introduce its eSignature technology to the Indian market, aligning with the Digital India initiative. This collaboration leveraged DocuSign's suite of applications and integrations to streamline the entire agreement process, including eSignature, contract lifecycle management, and document creation.
- In September 2022, Skribble secured over USD 10 million in a Series A funding round, co-led by Acton Capital Partners from Germany and VI Partners from Switzerland. This investment is aimed at strengthening Skribble’s market position and expanding its footprint across Europe.
- In September 2022, IDnow, a European leader in identity verification, partnered with Adobe Document Cloud to enhance the security and ease of verifying digital signatures. This integration allows Adobe Acrobat Sign users to validate their identities through IDnow’s videoident or autoident solutions, enabling the creation of legally binding electronic signatures.
Market Concentration & Characteristics:
The Digital Signature Software Market is moderately concentrated, with a few dominant players such as DocuSign, Adobe Sign, and SIGNiX holding significant market shares. These companies leverage their established brands, extensive product portfolios, and global reach to maintain a competitive advantage. The market is characterized by high entry barriers due to the need for compliance with stringent regulatory standards and the development of secure, scalable solutions. However, the market also features a growing number of smaller and regional players who focus on niche markets or offer specialized solutions, contributing to increased competition. As digital transformation accelerates across various industries, the market is witnessing rapid innovation and adoption, with cloud-based platforms and advanced technologies like AI and blockchain becoming integral to product offerings. The balance between innovation, security, and regulatory compliance defines the competitive dynamics of the Digital Signature Software Market.
Report Coverage:
The research report offers an in-depth analysis based on By Deployment, By Enterprise Type, By Level and By Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to see continued rapid growth, driven by increasing digitalization across industries.
- Adoption of AI and blockchain technologies will enhance the security and efficiency of digital signature solutions.
- Cloud-based digital signature platforms will dominate, offering scalability and flexibility to businesses.
- Regulatory compliance will remain a key driver, particularly in highly regulated sectors like finance and healthcare.
- Expansion into emerging markets will provide significant growth opportunities as digital infrastructure improves.
- The integration of digital signatures with existing enterprise systems will become more seamless, boosting adoption.
- Increased focus on environmental sustainability will drive the shift from paper-based processes to digital solutions.
- Competition will intensify as new players enter the market, offering niche and industry-specific solutions.
- User experience and ease of use will be critical factors in determining market leadership.
- The growing importance of remote work will continue to fuel demand for secure digital signature solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of Digital Signature Software by 2032?
What are the key drivers of the Digital Signature Software Market?
Which regions are leading in the Digital Signature Software Market?
What challenges does the Digital Signature Software Market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Digital Signature Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Digital Signature Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,460 million → 2032: USD 53,779.54 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Digital Signature Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Digital Signature Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Digital Signature Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Digital Signature Software Market Drivers
- 3.3 Digital Signature Software Market Restraints & Challenges
- 3.4 Digital Signature Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Digital Signature Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Digital Signature Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Digital Signature Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Digital Signature Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Digital Signature Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Digital Signature Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Digital Signature Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Digital Signature Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Digital Signature Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Digital Signature Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Digital Signature Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Digital Signature Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Digital Signature Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Digital Signature Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Digital Signature Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Digital Signature Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Digital Signature Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Digital Signature Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Digital Signature Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
