
Dimethyl Terephthalate Market Overview:
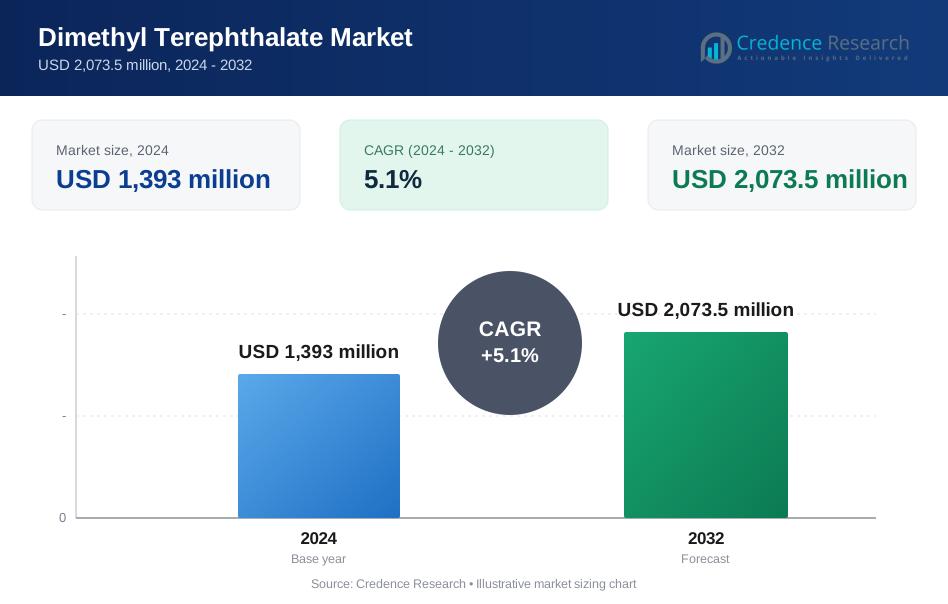
The dimethyl terephthalate (DMT) market was valued at USD 1,393 million in 2024 and is projected to reach USD 2,073.5 million by 2032, expanding at a CAGR of 5.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dimethyl Terephthalate Market Size 2024 | USD 1,393 million |
| Dimethyl Terephthalate Market, CAGR | 5.1% |
| Dimethyl Terephthalate Market Size 2032 | USD 2,073.5 million |
Dimethyl Terephthalate Market Insights
- Market growth is primarily driven by expanding PET and polyester resin production, with PET accounting for the dominant application segment due to its extensive use in packaging, fibers, and films, while technical grade DMT remains the leading grade segment owing to cost efficiency and large-scale industrial suitability.
- Key market trends include increasing focus on recyclable and sustainable polyesters, rising adoption of DMT in PBT and specialty polymers, and continued capacity expansion in Asia to support packaging and textile demand.
- The competitive landscape is moderately consolidated, led by integrated chemical producers and specialty suppliers competing on feedstock integration, product consistency, and long-term supply contracts with polyester manufacturers.
- Regionally, Asia-Pacific leads with ~49% market share, followed by Europe (~23%) and North America (~17%), while solid-form DMT dominates by form due to handling efficiency and suitability for bulk polymer manufacturing.

Dimethyl Terephthalate Market Segmentation Analysis:
By Form:
By form, solid dimethyl terephthalate dominates the segment, accounting for the largest market share due to its ease of handling, storage stability, and compatibility with large-scale polymer manufacturing processes. Solid DMT, particularly in flake and granular formats, is widely preferred by PET and engineering plastics producers for consistent feed rates and controlled reactivity during esterification and transesterification. Powder and granular forms support niche blending and specialty formulations, while liquid DMT remains limited due to handling constraints. Demand growth is driven by expanding polyester capacity and operational efficiency advantages in solid-form logistics.
- For instance, "Eastman Chemical Company produces molten Dimethyl Terephthalate (DMT)at its Kingsport, Tennessee facility, which includes a world-scale molecular recycling (methanolysis) plant with a nameplate capacity of 110,000 metric tons per year of recycled plastic feedstock.
By Grade:
By grade, technical grade dimethyl terephthalate holds the dominant market share, supported by its extensive use in bulk polymer production where ultra-high purity is not critical. Technical grade DMT is favored in PET, PBT, and PTT manufacturing due to its cost efficiency, reliable performance, and availability at industrial scale. Reagent and pure grades serve laboratory, pharmaceutical, and specialty chemical applications, while synthesis grade supports controlled reaction environments. Market demand is primarily driven by downstream polyester resin expansion, where technical grade meets performance specifications without the cost burden of higher-purity alternatives.
- For instance, Tokyo Chemical Industry (TCI) supplies high-purity Dimethyl Terephthalate (DMT)for academic and industrial research. While catalog sizes typically range from 25g to 500g, TCI provides bulk quantities and custom synthesis options that can scale from kilograms to tons upon request.
By Application:
By application, polyethylene terephthalate (PET) represents the dominant sub-segment, capturing the majority of market share due to its widespread use in packaging, fibers, and films. DMT serves as a critical precursor in PET resin production, benefiting from steady demand across beverage bottles, food packaging, and textile fibers. Polybutylene terephthalate (PBT) follows, driven by electrical and automotive components, while polytrimethylene terephthalate (PTT) supports niche textile and carpet applications. PET dominance is reinforced by global packaging demand, recyclability initiatives, and sustained polyester fiber consumption.
Key Growth Driver
Expanding Polyester and PET Resin Production
Rising global production of polyester resins remains a primary growth driver for the dimethyl terephthalate (DMT) market. DMT is a critical intermediate in the manufacture of polyethylene terephthalate (PET), polybutylene terephthalate (PBT), and polytrimethylene terephthalate (PTT), all of which are widely used across packaging, textiles, automotive components, and consumer goods. The steady expansion of PET bottle, film, and fiber manufacturing capacities particularly in Asia-Pacific and the Middle East continues to support consistent demand for DMT. Its advantages in process stability, ease of purification, and suitability for large-scale transesterification make it a preferred feedstock for polyester producers. Ongoing investments in polymer plants and capacity debottlenecking further reinforce DMT consumption growth.
- For instance, "Indorama Ventures operates multiple integrated PET manufacturing complexes across Asia and the Middle East, with regional combined capacities reaching millions of metric tons per year. These individual sites typically utilize PTA-based (Purified Terephthalic Acid) direct esterificationrather than DMT-based transesterification, enabling high-throughput production with stable polymerization kinetics and precise intrinsic viscosity control."
Growth of the Packaging and Textile Industries
The rapid growth of the global packaging and textile industries significantly drives demand for dimethyl terephthalate. PET-based packaging materials are extensively used for food, beverages, and consumer goods due to their clarity, strength, and lightweight characteristics. Simultaneously, polyester fibers produced using DMT are widely utilized in apparel, home textiles, and industrial fabrics because of durability and cost efficiency. Urbanization, rising disposable incomes, and changing consumer lifestyles continue to boost packaged food and fast-fashion consumption. These trends directly translate into higher polyester resin output, strengthening DMT demand. Additionally, increasing preference for synthetic fibers over natural alternatives in performance textiles further supports sustained consumption of DMT-based polyester intermediates.
- For instance, "Coca-Cola Europacific Partners (CCEP) sources bottle-grade PET resin from regional producers, such as Indorama Ventures, that utilize world-scale continuous polymerization (CP) lines with single-line capacities typically ranging from 600 to 900 metric tons per day.
Cost and Processing Advantages over Alternative Intermediates
Dimethyl terephthalate benefits from favorable cost economics and processing advantages compared with alternative intermediates such as purified terephthalic acid (PTA) in certain applications. DMT offers better storage stability, lower corrosiveness, and easier handling, particularly in regions with less-developed chemical logistics infrastructure. These characteristics reduce operational risks and maintenance costs for manufacturers. In specialty polyester and engineering plastic applications, DMT enables precise control over polymer properties and reaction conditions. This flexibility supports its continued adoption in niche and high-performance polymer segments. As manufacturers seek operational efficiency and reliability, DMT remains a viable and attractive raw material choice across multiple downstream industries.
Key Trend & Opportunity
Rising Focus on Sustainable and Recyclable Polyesters
Sustainability initiatives across packaging and textiles are creating new opportunities for the dimethyl terephthalate market. PET and other polyester materials derived from DMT align well with recycling systems and circular economy models. Manufacturers are increasingly investing in recycled PET (rPET) and chemical recycling technologies, where DMT can be recovered and reused as a monomer. This trend enhances the long-term relevance of DMT in sustainable polymer supply chains. Regulatory pressure to reduce plastic waste and improve recyclability is further accelerating adoption of polyester materials with established recycling pathways. These developments position DMT as a key contributor to environmentally responsible polymer production.
- For instance, Loop Industries has demonstrated depolymerization of low-value PET waste into DMT with purity levels suitable for direct PET resin synthesis, supplying output to brand owners conducting commercial-scale bottle production trials on industrial filling lines.
Growth in Engineering Plastics and Specialty Applications
Increasing use of engineering plastics in automotive, electrical, and electronics applications presents a significant growth opportunity for DMT. Polybutylene terephthalate (PBT), produced using DMT, is widely used in connectors, housings, and under-the-hood automotive components due to its heat resistance and dimensional stability. Demand for lightweight, high-performance materials continues to rise as manufacturers pursue energy efficiency and miniaturization. Additionally, specialty polyester grades used in coatings, films, and high-end textiles require consistent raw material quality, supporting steady demand for DMT. Expansion of these value-added applications enhances market resilience beyond commodity polyester demand.
- For instance, BASF produces PBT under its Ultradur® portfolio, with grades engineered to withstand continuous operating temperatures up to 150 °C while maintaining dielectric strength and mechanical integrity in automotive connector systems manufactured at annual volumes exceeding several million units.
Key Challenge
Volatility in Raw Material Prices
Fluctuations in the prices of key raw materials, particularly methanol and paraxylene derivatives, pose a major challenge for the dimethyl terephthalate market. These inputs are closely linked to crude oil price movements, making DMT production costs sensitive to global energy market volatility. Sudden price swings can compress margins for manufacturers and create uncertainty in long-term supply contracts. Smaller producers are particularly exposed, as they often lack hedging mechanisms or diversified feedstock sourcing. Persistent cost instability can also discourage capacity expansions and impact downstream pricing strategies, creating challenges for maintaining competitiveness in price-sensitive polyester markets.
Competition from Purified Terephthalic Acid (PTA)
Increasing adoption of purified terephthalic acid presents a structural challenge to the dimethyl terephthalate market. PTA is widely used in large-scale PET production due to process integration advantages and lower conversion steps in modern plants. Many new polyester facilities are designed around PTA-based processes, limiting DMT penetration in new capacities. As PTA production technology advances and economies of scale improve, its cost competitiveness strengthens. This shift reduces DMT’s share in commodity PET manufacturing, confining its growth largely to specialty, regional, or operationally constrained applications. Maintaining relevance requires DMT producers to focus on performance-driven and niche market segments.
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the dimethyl terephthalate market, accounting for approximately 48-50% of global market share, driven by extensive polyester and PET manufacturing capacity across China, India, South Korea, and Southeast Asia. The region benefits from strong demand in packaging, textiles, and industrial fibers, supported by large-scale production ecosystems and cost-efficient manufacturing. China remains the primary consumer due to its integrated polyester value chain, while India shows rising demand from packaging and fiber applications. Continuous investments in polymer capacity expansion and export-oriented production sustain Asia-Pacific’s leadership in the global DMT market.
Europe
Europe represents around 22-24% of the global dimethyl terephthalate market, supported by steady demand from packaging, automotive, and engineering plastics applications. The region emphasizes high-quality polyester materials, driving consistent consumption of DMT in PBT and specialty PET grades. Germany, Italy, and France are key contributors due to strong automotive and industrial manufacturing bases. Sustainability regulations and advanced recycling initiatives further support polyester usage, indirectly reinforcing DMT demand. Although growth is moderate compared to Asia-Pacific, Europe maintains stable market share due to technological sophistication and strong downstream demand for engineered polymer applications.
North America
North America accounts for approximately 16-18% of the dimethyl terephthalate market, driven by demand from packaging, consumer goods, and engineering plastics. The United States leads regional consumption, supported by established PET resin production and strong demand for food and beverage packaging. While PTA dominates large-scale PET production, DMT maintains relevance in specialty polyester and PBT applications. Growth is supported by stable industrial output and demand for durable, high-performance materials. However, market expansion remains moderate due to mature end-use industries and limited new polyester capacity additions in the region.
Latin America
Latin America holds an estimated 6-7% share of the global dimethyl terephthalate market, supported by growing packaging and textile industries in Brazil, Mexico, and Argentina. Rising consumption of packaged food and beverages is increasing PET resin demand, indirectly supporting DMT usage. The region benefits from improving industrial infrastructure and increasing investments in polymer processing. However, limited domestic production capacity results in reliance on imports, constraining rapid growth. Despite these challenges, gradual expansion of consumer markets and industrial manufacturing continues to support steady demand for DMT across Latin America.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4-5% of the global dimethyl terephthalate market, driven primarily by emerging polyester production and packaging demand. Countries in the Middle East benefit from strong petrochemical integration and access to feedstocks, supporting gradual development of polyester intermediates. In Africa, demand is driven by urbanization and increasing use of packaged consumer goods. Although market penetration remains relatively low, ongoing investments in petrochemical complexes and downstream polymer industries are expected to support long-term growth, gradually increasing the region’s contribution to global DMT demand.
Dimethyl Terephthalate Market Segmentations:
By Form
- Solid
- Powder
- Granular
- Flakes
- Liquid
By Grade
- Technical
- Reagent
- Pure
- Synthesis
By Application
- Polyethylene Terephthalate (PET)
- Polytrimethylene Terephthalate (PTT)
- Polybutylene Terephthalate (PBT)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The dimethyl terephthalate market features a moderately consolidated competitive landscape characterized by the presence of integrated petrochemical producers and specialized polyester intermediate manufacturers. Leading companies compete primarily on production scale, feedstock integration, product consistency, and long-term supply agreements with polyester and engineering plastics manufacturers. Players with backward integration into aromatics and methanol benefit from cost efficiencies and supply stability, strengthening their competitive positioning. Market participants also focus on operational reliability, process optimization, and compliance with environmental standards to maintain customer confidence. While large producers dominate bulk volumes for PET and PBT applications, smaller players remain active in serving regional and specialty-grade requirements. Strategic priorities include capacity optimization, selective expansion in high-growth regions, and alignment with downstream polyester demand, enabling firms to sustain competitiveness amid pricing pressure and substitution from alternative intermediates.
Key Player Analysis
- Eastman Chemical Company
- SK Chemical
- Oxxynova
- Connect Chemical
- Fiber Intermediate Product Company
- Merck
- Haihang Industry Co. Ltd.
- Kanto Chemical Co., Inc.
- Kishida Chemicals
- Sarna Chemicals
Recent Developments
- In December 2025, SK Chemicals announced a joint venture with China-based PET recycler Kelinle to establish a Feedstock Innovation Center in Shaanxi Province, China. The facility will be developed on an approximately 13,200-square-meter site and is planned to initially process about 16,000 tons of waste plastics per year into recycled feedstock. Capacity is expected to increase to about 32,000 tons per year in the future, strengthening SK Chemicals’ access to circular polyester feedstocks, including DMT-related recycled intermediates.
- In April 2025, SK Chemicals showcased its depolymerization-based recycling technologies and sustainable polyester and copolyester materials at CHINAPLAS 2025, held from April 15-18 in Shenzhen, China. The company highlighted chemically recycled feedstock-derived materials already used in consumer and industrial applications, underscoring the commercial deployment of recycled PET materials.
Report Coverage
The research report offers an in-depth analysis based on Form, Grade, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for dimethyl terephthalate will continue to track the expansion of global polyester and PET resin production.
- Asia-Pacific will remain the primary growth engine due to sustained capacity additions in packaging and textile polymers.
- PET applications will retain dominance, supported by steady consumption in food, beverage, and consumer packaging.
- Technical grade dimethyl terephthalate will maintain the largest share due to cost efficiency and industrial-scale usability.
- Solid and flake forms will continue to be preferred for large-volume polymer manufacturing operations.
- Growth in engineering plastics will support incremental demand from PBT-based automotive and electrical components.
- Sustainability initiatives will encourage recovery and reuse of dimethyl terephthalate in chemical recycling pathways.
- Producers will focus on operational efficiency and feedstock integration to manage cost volatility.
- Competitive pressure from purified terephthalic acid will confine growth to specialty and regional applications.
- Incremental investments in specialty grades will enhance market resilience and diversify end-use exposure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dimethyl terephthalate, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dimethyl terephthalate projected to grow between 2024 and 2032?
Which Dimethyl terephthalate segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dimethyl terephthalate market?
Who are the leading companies in the Dimethyl terephthalate market?
Which region commanded the largest share of the Dimethyl terephthalate market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dimethyl Terephthalate Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dimethyl Terephthalate Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,393 million → 2032: USD 2,073.5 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dimethyl Terephthalate Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dimethyl Terephthalate Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dimethyl Terephthalate Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dimethyl Terephthalate Market Drivers
- 3.3 Dimethyl Terephthalate Market Restraints & Challenges
- 3.4 Dimethyl Terephthalate Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dimethyl Terephthalate Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dimethyl Terephthalate Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dimethyl Terephthalate category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dimethyl Terephthalate Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dimethyl Terephthalate Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dimethyl Terephthalate market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dimethyl Terephthalate Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dimethyl Terephthalate Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dimethyl Terephthalate Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dimethyl Terephthalate (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dimethyl Terephthalate Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dimethyl Terephthalate Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dimethyl Terephthalate Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dimethyl Terephthalate Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dimethyl Terephthalate Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dimethyl Terephthalate Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dimethyl Terephthalate Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dimethyl Terephthalate Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dimethyl Terephthalate Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
