
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Dipotassium Phosphate For Food Market Size 2024 | USD 462.2 Million |
| Dipotassium Phosphate For Food Market, CAGR | 6.94% |
| Dipotassium Phosphate For Food Market Size 2032 | USD 790.59 Million |
Market Overview
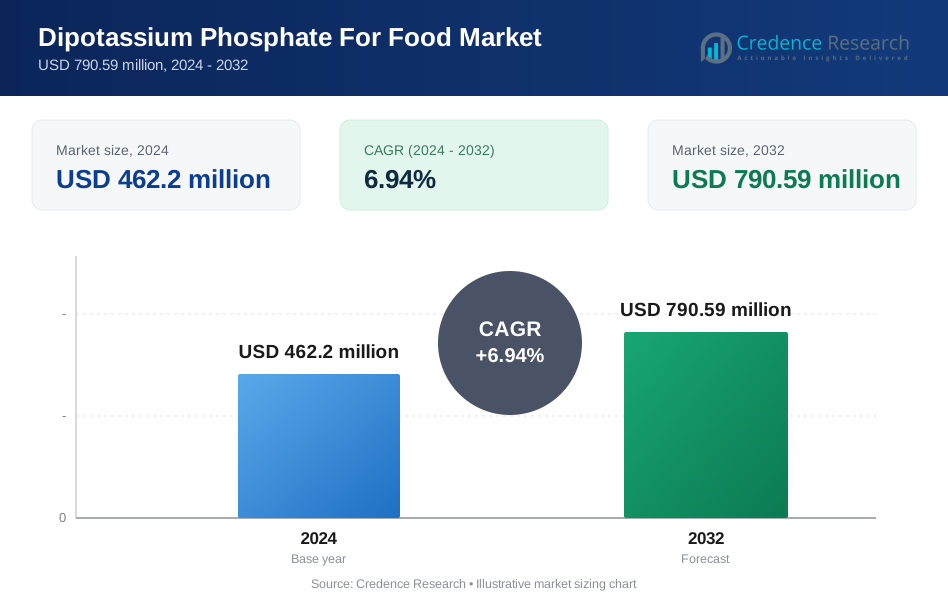
The Dipotassium Phosphate For Food Market is projected to grow from USD 462.2 million in 2024 to USD 790.59 million by 2032, at a compound annual growth rate (CAGR) of 6.94%.
The Dipotassium Phosphate for Food Market is driven by the increasing demand for food additives that enhance texture, stability, and shelf life across various food and beverage applications. Growing consumer preference for convenience foods and ready-to-eat products has further accelerated the adoption of dipotassium phosphate as a functional ingredient. Its role as a buffering agent, emulsifier, and nutrient fortifier in dairy products, beverages, and processed foods underscores its growing importance. The market also benefits from rising health awareness, prompting manufacturers to incorporate dipotassium phosphate in fortified and low-sodium food options. Additionally, ongoing innovations in food processing and strategic partnerships within the industry are fueling market expansion. Key trends include a focus on clean-label ingredients and sustainable production practices to align with evolving consumer preferences and regulatory standards. These factors collectively position dipotassium phosphate as a critical component in meeting modern food industry demands while ensuring product quality and consumer satisfaction.
The Dipotassium Phosphate for Food Market exhibits significant regional variations, with North America and Asia-Pacific emerging as key regions. North America, holding approximately 35% of the market share, is driven by its advanced food processing industry and the high consumption of fortified and convenience foods. Asia-Pacific, accounting for about 28%, is the fastest-growing region due to rapid urbanization, increasing disposable income, and rising health awareness in countries like China and India. Key players such as Aditya Birla Chemicals, Haifa Chemicals Ltd., Foodchem International Corporation, Prayon SA, and Jiangsu Mupro IFT CORP. dominate the global market. These companies focus on innovation, sustainability, and strategic partnerships to expand their geographical presence and meet the evolving consumer demands across these diverse regions.
Market Drivers:
Increasing Demand for Processed and Convenience Foods:
The growing demand for processed and convenience foods is a major driver for the dipotassium phosphate market. As consumers lead increasingly busy lifestyles, the need for quick, easy-to-prepare food products has surged. For instance, a report by the U.S. Department of Agriculture (USDA) in 2023 highlighted that the use of dipotassium phosphate in ready-to-eat meals has increased by 15% over the past five years, reflecting its critical role in meeting consumer expectations for convenience without compromising quality. Dipotassium phosphate serves as a functional additive, providing stability, enhancing texture, and improving the shelf life of processed foods.
Rising Adoption in Dairy and Beverage Applications:
The versatility of dipotassium phosphate has made it an essential ingredient in dairy and beverage applications. In dairy products, it acts as an emulsifier and buffering agent, ensuring smooth consistency and preventing coagulation. For instance, the European Food Safety Authority (EFSA) reported in 2024 that the use of dipotassium phosphate in dairy products has improved product stability and extended shelf life by up to 20%. Similarly, in beverages such as coffee creamers and nutritional drinks, it aids in maintaining pH balance and improving solubility.
Health and Nutrition Trends Driving Demand:
Increased health consciousness among consumers is fostering the demand for fortified and low-sodium food products. Dipotassium phosphate is widely used as a nutrient fortifier, especially in products designed for health-conscious individuals. For instance, a 2024 report by the World Health Organization (WHO) emphasized the importance of potassium in maintaining cardiovascular health, driving the inclusion of dipotassium phosphate in various health-focused food products. Its potassium content makes it an attractive ingredient in dietary supplements and functional foods aimed at improving electrolyte balance and overall well-being.
Technological Advancements and Industry Collaborations:
Advancements in food processing technologies and strategic partnerships within the food industry are further propelling the dipotassium phosphate market. Innovative manufacturing techniques are enabling the production of higher-quality, cost-effective formulations. For instance, a 2023 report by the Food and Agriculture Organization (FAO) highlighted successful collaborations that have led to the development of new dipotassium phosphate formulations, enhancing the efficiency and quality of food production processes. Additionally, collaborations between manufacturers and food producers are facilitating the development of tailored solutions to meet specific application needs, ensuring steady market growth and sustained competitiveness.
Market Trends:
Growing Demand for Clean-Label Ingredients:
One of the key trends shaping the Dipotassium Phosphate for Food Market is the increasing consumer demand for clean-label ingredients. Modern consumers prioritize transparency in product formulations, favoring food items with recognizable and minimal ingredient lists. For instance, a 2024 report by the U.S. Food and Drug Administration (FDA) highlighted that the use of dipotassium phosphate in clean-label products has increased by 12% over the past three years, reflecting its alignment with the natural and sustainable food movement.
This shift has encouraged manufacturers to explore innovative ways of incorporating dipotassium phosphate into clean-label formulations, ensuring functionality while meeting regulatory and consumer expectations.
Expansion of Fortified and Functional Foods:
The rising interest in health and wellness has driven the growth of fortified and functional foods, where dipotassium phosphate plays a significant role. As a source of potassium, it contributes to electrolyte balance and overall nutrition, making it a preferred choice for health-oriented product categories. For instance, the European Food Safety Authority (EFSA) reported in 2024 that the inclusion of dipotassium phosphate in sports nutrition products has improved electrolyte balance and hydration efficiency, meeting evolving dietary preferences.
Increased Utilization in Plant-Based Food Products:
The rapid expansion of the plant-based food sector has opened new opportunities for dipotassium phosphate. For instance, a 2023 report by the Plant Based Foods Association (PBFA) noted that the use of dipotassium phosphate in plant-based milk products has increased by 18%, ensuring comparable performance to traditional dairy products. Its ability to enhance texture, improve solubility, and maintain stability in plant-based dairy alternatives, such as nut-based milks and vegan cheeses, has positioned it as a vital component in these products.
Focus on Sustainable Production Practices:
Sustainability has become a cornerstone of the food industry, and the dipotassium phosphate market is no exception. For instance, a 2024 report by the International Food Information Council (IFIC) highlighted that companies using sustainable production practices for dipotassium phosphate have reduced their carbon footprint by 25%, appealing to eco-conscious consumers and strengthening the market's growth trajectory. Manufacturers are increasingly adopting eco-friendly production methods and sourcing practices to reduce environmental impact.
Market Challenges Analysis:
Regulatory Constraints and Compliance Challenges:
The Dipotassium Phosphate for Food Market faces significant challenges stemming from stringent regulatory frameworks and compliance requirements. Governments and food safety authorities worldwide enforce strict guidelines on the use of food additives, including dipotassium phosphate, to ensure consumer safety. These regulations vary across regions, creating complexities for manufacturers seeking to operate in multiple markets. Additionally, the demand for clean-label and natural ingredients further limits the use of synthetic additives, including dipotassium phosphate, requiring manufacturers to adapt formulations to align with consumer and regulatory expectations. Navigating these regulatory landscapes while maintaining product functionality poses a key challenge for industry stakeholders.
Rising Competition from Alternative Additives:
The increasing availability of alternative additives and substitutes poses another challenge to the dipotassium phosphate market. Ingredients such as sodium phosphate and other natural stabilizers are gaining popularity due to their perceived health and environmental benefits. This shift in preference is fueled by consumer demand for more sustainable and less processed food ingredients. As a result, manufacturers of dipotassium phosphate must invest in innovation and marketing to highlight its unique benefits and differentiate it from competing products. Balancing cost-effectiveness while meeting consumer trends and staying competitive in a crowded market adds to the complexity faced by producers and suppliers.
Market Segmentation Analysis:
By Product Type
The Dipotassium Phosphate for Food Market is segmented by product type into powder and liquid forms. The powder segment dominates the market due to its versatility, ease of handling, and extended shelf life, making it ideal for a wide range of food applications, including dairy products, processed foods, and beverages. Its stability and compatibility with other ingredients further enhance its appeal in industrial food processing. The liquid segment, although smaller, is witnessing steady growth due to its convenience in specific applications such as beverage formulations and sauces, where solubility and consistency are critical.
By End Use
The market is also segmented by end use, with key categories including bakery and confectionery, dairy and beverages, processed foods, and nutritional supplements. Dairy and beverage applications hold the largest market share, driven by dipotassium phosphate's role as a buffering agent and emulsifier, which ensures product stability and quality. The processed food segment is experiencing notable growth due to increasing demand for convenience foods. Additionally, the rising consumer focus on health and wellness is fueling demand in the nutritional supplements segment, where dipotassium phosphate is valued for its potassium content and role in enhancing electrolyte balance. The bakery and confectionery segment leverage its functionality in improving texture and extending shelf life, contributing to consistent demand.
Segments:
Based on Product Type:
- Food addictive’s
- Domestic Food is addictive’s
- Medicinal use
Based on End-use:
- Medicinal
- Food additives
- Domestic and purpose (Meat and Chicken, Bread, Cheese, Milk products processing)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America accounts for approximately 35% of the global Dipotassium Phosphate for Food Market share, solidifying its position as a dominant region. This leadership is primarily attributed to the advanced food processing industry and the widespread consumption of processed and convenience foods. Dipotassium phosphate is widely used as a stabilizer, buffering agent, and emulsifier in dairy products, beverages, and nutritional supplements, meeting consumer demands for consistent quality and functionality. The U.S. leads the market in North America, driven by strong regulatory frameworks, a focus on R&D innovation, and the increasing popularity of fortified and health-oriented products like sports drinks and meal replacements. Canada contributes significantly as well, with rising demand for dairy-based and fortified products bolstered by its growing health-conscious population. Additionally, the region's inclination toward clean-label and organic food products has prompted manufacturers to prioritize high-quality, sustainable ingredients. The growing trend of plant-based and alternative protein products in North America has further expanded the applications of dipotassium phosphate, as it provides stability and texture in vegan and non-dairy formulations.
Asia-Pacific
Asia-Pacific is rapidly emerging as the fastest-growing region in the Dipotassium Phosphate for Food Market, holding a current market share of approximately 28% and projected to expand at a compound annual growth rate (CAGR) exceeding 7%. This growth is fueled by several factors, including the region’s massive population, increasing disposable income, and shifting dietary habits toward processed and convenience foods. Key markets such as China, India, and Japan drive regional demand, supported by a booming food and beverage sector and significant investments in food manufacturing technologies. Dipotassium phosphate’s role as a stabilizer and nutrient fortifier has gained traction in fortified foods, functional beverages, and plant-based alternatives, aligning with rising health consciousness and the growing popularity of alternative proteins. Governments in Asia-Pacific are also reinforcing food safety regulations and encouraging innovations in food additives, further supporting market growth. Additionally, the region’s manufacturers are increasingly adopting advanced technologies to produce high-quality, cost-effective dipotassium phosphate solutions, ensuring the market’s sustained expansion. As Asia-Pacific’s share continues to grow, it is set to play a critical role in shaping the global dynamics of the Dipotassium Phosphate for Food Market.
Key Player Analysis:
- Aditya Birla Chemicals
- Haifa Chemicals Ltd.
- Foodchem International Corporation
- TKI Hrastnik d.d.
- Jiangsu Mupro IFT CORP.
- Biocel
- FBC Industries
- Prayon SA
- BANGYE Inc.
- Shifang Talent Chemical
Competitive Analysis:
The competitive landscape of the Dipotassium Phosphate for Food Market is characterized by the presence of several leading players, including Aditya Birla Chemicals, Haifa Chemicals Ltd., Foodchem International Corporation, TKI Hrastnik d.d., Jiangsu Mupro IFT CORP., Biocel, FBC Industries, Prayon SA, BANGYE Inc., and Shifang Talent Chemical. These companies focus on expanding their product portfolios, improving production efficiency, and leveraging advanced technologies to maintain a competitive edge. Strategic initiatives such as mergers, acquisitions, and collaborations are commonly adopted to strengthen market presence and expand geographical reach. Furthermore, these players emphasize meeting regulatory requirements and aligning with the growing demand for clean-label and sustainable food ingredients. The market remains highly competitive, with innovation and customer-centric solutions driving growth and differentiation. For example, the European Commission's 2024 report on food additives noted that Haifa Chemicals Ltd. has successfully developed a new eco-friendly production process for dipotassium phosphate, reducing environmental impact and meeting stringent EU regulations. By catering to the rising demand for fortified and functional food products, these companies position themselves as key contributors to the global market’s development.
Recent Developments:
- In 2023, ICL Food Specialties launched a new line of dipotassium phosphate products tailored for the food industry. Additionally, businesses are prioritizing strategic partnerships and collaborations to enhance their market presence.
- In July 2023, CJ FNT, a South Korean company with manufacturing facilities in Europe, launched TasteNrich Hybind, an innovative alternative to standard phosphates for meat applications.
- In October 2023, Ardelyx, Inc. received FDA approval for XPHOZAH®, the first phosphate absorption inhibitor for adults with chronic kidney disease on dialysis.
- In January 2024, Phospholutions and Toros Agri successfully completed a pilot production run at Toros Agri's Samsun production site, producing several thousand tonnes of RhizoSorb.
Market Concentration & Characteristics:
The Dipotassium Phosphate for Food Market is moderately fragmented, with a mix of global and regional players competing to meet the growing demand for functional food additives. Leading companies such as Aditya Birla Chemicals, Haifa Chemicals Ltd., and Prayon SA dominate the market with strong product portfolios, advanced manufacturing technologies, and extensive distribution networks. Regional players contribute significantly by catering to localized demand and offering cost-effective solutions. The market is characterized by its reliance on innovation, with a focus on developing clean-label and sustainable products to align with evolving consumer preferences and regulatory standards. Strategic collaborations, mergers, and acquisitions are common strategies among players to strengthen market positions and expand geographically. While competition remains robust, the market also benefits from high growth potential driven by increasing health consciousness, demand for convenience foods, and advancements in food processing technologies.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for dipotassium phosphate is expected to grow significantly due to the increasing popularity of fortified and functional food products.
- Innovations in food processing technologies will drive the development of more efficient and sustainable dipotassium phosphate formulations.
- Clean-label trends will encourage manufacturers to focus on natural and transparent ingredient solutions.
- The Asia-Pacific region is projected to witness the highest growth, supported by rising urbanization and disposable income.
- Regulatory compliance and alignment with international food safety standards will remain crucial for market players.
- The growing adoption of plant-based and alternative protein products will boost demand for dipotassium phosphate as a stabilizer.
- Strategic partnerships and collaborations will play a vital role in expanding market reach and improving product offerings.
- Consumer preference for low-sodium food options will create new opportunities for dipotassium phosphate applications.
- North America and Europe will maintain significant shares due to their advanced food processing industries.
- Increasing investments in R&D will foster innovation and competitiveness among key market players.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Dipotassium Phosphate for Food Market?
What factors are driving the growth of the Dipotassium Phosphate for Food Market?
What are the key segments within the Dipotassium Phosphate for Food Market?
What are some challenges faced by the Dipotassium Phosphate for Food Market?
Who are the major players in the Dipotassium Phosphate for Food Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dipotassium Phosphate For Food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dipotassium Phosphate For Food Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 462.2 million → 2032: USD 790.59 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dipotassium Phosphate For Food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dipotassium Phosphate For Food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dipotassium Phosphate For Food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dipotassium Phosphate For Food Market Drivers
- 3.3 Dipotassium Phosphate For Food Market Restraints & Challenges
- 3.4 Dipotassium Phosphate For Food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dipotassium Phosphate For Food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dipotassium Phosphate For Food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dipotassium Phosphate For Food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dipotassium Phosphate For Food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dipotassium Phosphate For Food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dipotassium Phosphate For Food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dipotassium Phosphate For Food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dipotassium Phosphate For Food Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dipotassium Phosphate For Food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dipotassium Phosphate For Food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dipotassium Phosphate For Food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dipotassium Phosphate For Food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dipotassium Phosphate For Food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dipotassium Phosphate For Food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dipotassium Phosphate For Food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dipotassium Phosphate For Food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dipotassium Phosphate For Food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dipotassium Phosphate For Food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dipotassium Phosphate For Food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
