
Market Overview
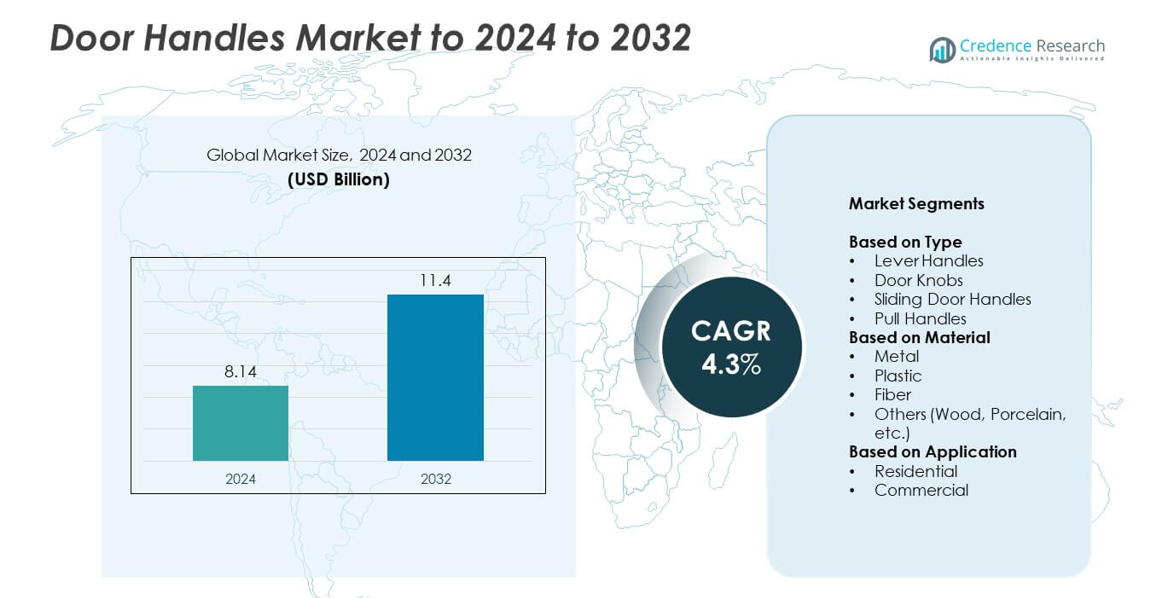
Door Handles Market size was valued USD 8.14 Billion in 2024 and is anticipated to reach USD 11.4 Billion by 2032, at a CAGR of 4.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Door Handles Market Size 2024 | USD 8.14 Billion |
| Door Handles Market, CAGR | 4.3% |
| Door Handles Market Size 2032 | USD 11.4 Billion |
The door handles market is shaped by prominent players such as Allegion Plc, Sugatsune America, Inc., Kuriki Manufacture Co., Baldwin Hardware, Hoppe Holding AG, Assa Abloy AB, Aarkay Vox, The Häfele Group, West INX Ltd., Kwikset, Emtek Products Inc., and Ace Hardware Corp. These companies focus on technological innovation, design customization, and sustainable production to enhance competitiveness. Product advancements include smart locking systems, ergonomic designs, and eco-friendly materials, catering to both residential and commercial demand. Regionally, Asia Pacific led the global market in 2024 with a 34% share, driven by rapid urbanization, infrastructure growth, and expanding housing developments, while North America and Europe followed as mature yet innovation-driven markets.
Market Insights
- The door handles market was valued at USD 8.14 billion in 2024 and is projected to reach USD 11.4 billion by 2032, growing at a CAGR of 4.3%.
- Rising residential and commercial construction activities, coupled with home renovation trends, are driving market expansion globally.
- Lever handles held the largest share of about 46% in 2024, supported by ergonomic design and high demand in modern buildings.
- The market is competitive, with key players focusing on smart, decorative, and sustainable handle designs to strengthen their global presence.
- Asia Pacific led the market with a 34% share in 2024, followed by North America at 28% and Europe at 25%, driven by strong infrastructure growth and product innovation.
Market Segmentation Analysis:
By Type
Lever handles dominated the door handles market in 2024, accounting for around 46% share. Their popularity stems from ergonomic design, ease of use, and compatibility with modern door systems. Lever handles are increasingly preferred in both residential and commercial settings for accessibility and aesthetic appeal. Manufacturers focus on smart lever designs with integrated locking systems to meet growing security and convenience demands. Rising renovation and construction projects globally continue to drive demand for lever handles, particularly in the premium architectural and hospitality sectors.
- For instance, dormakaba’s FOUR+ lever handles surpassed 1,000,000 test cycles under BS EN 1906 load testing.
By Material
Metal-based door handles held the leading position with nearly 58% market share in 2024. Stainless steel, brass, and aluminum are widely used due to durability, corrosion resistance, and elegant finishes. The material’s strength supports usage in heavy-duty commercial and industrial environments. The growing preference for metallic finishes in interior design also supports this dominance. Sustainable production of metal handles and growing use of recyclable alloys are emerging as additional growth drivers in the segment.
- For instance, Sugatsune’s 316-grade stainless handles list exact specs, such as 200 mm width and 1,000 g weight on model FT-T-220.
By Application
The residential segment accounted for the largest share of around 62% in 2024. Rapid urbanization, rising housing investments, and renovation activities are key growth drivers. Consumers increasingly prefer decorative and smart door handle solutions, aligning with modern home automation trends. Additionally, higher disposable income in developing nations supports demand for premium handles with advanced locking and aesthetic features. The increasing emphasis on home safety and customized interior design continues to strengthen the residential segment’s leadership in the overall door handles market.
Key Growth Drivers
Expanding Construction and Renovation Activities
The global rise in residential and commercial construction directly fuels demand for door handles. Rapid urbanization and infrastructure projects in developing nations increase installations across housing and office spaces. Renovation and remodeling trends in developed markets further boost replacement demand. The growing emphasis on energy-efficient and aesthetic building materials encourages adoption of modern and durable handle designs, driving steady market expansion.
- For instance, ASSA ABLOY completed 24 acquisitions in 2023, including the acquisition of Spectrum Brands' Hardware and Home Improvement (HHI) division.
Rising Demand for Smart and Aesthetic Handles
The growing popularity of smart homes and connected devices is driving demand for digital and sensor-based door handles. Consumers seek advanced locking mechanisms with touchless or biometric features for enhanced convenience and safety. At the same time, modern interior design trends promote decorative finishes, customized shapes, and luxury aesthetics, encouraging premium product innovation among manufacturers.
- For instance, Häfele’s Genesis DL8800 smart lock stores 300 user codes and is rated IP55.
Increasing Focus on Material Innovation and Sustainability
The shift toward eco-friendly and durable materials is a major growth enabler. Manufacturers are adopting stainless steel, zinc, and recyclable alloys to enhance longevity and reduce environmental impact. Sustainable manufacturing processes and low-emission coatings also align with green building standards. These innovations enhance product performance and appeal to environmentally conscious consumers and construction firms.
Key Trends and Opportunities
Integration of Smart Technology in Door Hardware
The adoption of electronic and IoT-enabled door handles is transforming building security systems. Smart locks with wireless connectivity allow remote access and real-time monitoring, catering to residential and hospitality sectors. This shift toward digital door solutions opens new opportunities for hardware companies to collaborate with smart home technology providers.
- For instance, GEZE networked over 180 door systems in one campus and supports up to 200 connected devices per controller.
Growing Popularity of Premium and Customizable Designs
Consumers increasingly value personalization and aesthetics in home interiors. Manufacturers respond with customizable handles featuring varied textures, finishes, and color options. The surge in luxury housing projects and boutique hotels creates a lucrative opportunity for high-end handle designs that blend functionality with visual appeal.
- For instance, KURIKI's catalog details configurable hardware, with an adjustable strike plate that provides a front-back adjustment range of ±2 mm.
Key Challenges
Price Fluctuations in Raw Materials
Volatility in prices of metals such as stainless steel and aluminum poses challenges to manufacturers. Rising raw material costs affect production budgets and profit margins, especially for mid-range and small-scale producers. This volatility also limits the affordability of premium designs for cost-sensitive markets.
Intense Market Competition and Product Imitation
The presence of numerous local and global manufacturers leads to intense price competition. Low-cost imitations and counterfeit products erode brand loyalty and hinder innovation investments. Maintaining product differentiation through quality assurance and design innovation remains a significant challenge for established brands.
Regional Analysis
North America
North America accounted for nearly 28% of the global door handles market in 2024. The region’s growth is driven by strong residential construction, renovation projects, and demand for smart locking systems. The United States dominates regional consumption due to rapid adoption of automated and designer handles. Energy-efficient housing and commercial remodeling trends also support product demand. Manufacturers focus on premium metal finishes and digital integration to meet evolving consumer preferences, strengthening the region’s competitive edge in the global market.
Europe
Europe held around 25% market share in 2024, supported by sustainable construction practices and demand for high-quality architectural hardware. Countries such as Germany, the U.K., and France lead consumption due to rising renovation activities and luxury housing trends. European consumers prefer handles made from recyclable materials, reflecting the region’s emphasis on eco-friendly designs. Regulatory standards promoting energy-efficient and sustainable products further drive innovation. Increasing adoption of contemporary and minimalist interior styles contributes to steady market expansion across residential and hospitality segments.
Asia Pacific
Asia Pacific dominated the global market with about 34% share in 2024. Rapid urbanization, housing demand, and government-backed infrastructure projects in China, India, and Southeast Asia boost product consumption. Growing middle-class income and rising interest in modern interior design support higher adoption of decorative and smart door handles. Local manufacturers are expanding capacity to meet domestic demand while competing with international brands. The region’s large construction sector and ongoing urban development make Asia Pacific the fastest-growing and most dynamic regional market.
Latin America
Latin America represented close to 7% market share in 2024, driven by recovery in residential construction and increasing commercial property development. Brazil and Mexico lead demand with growing investments in housing and hospitality infrastructure. Rising consumer preference for stylish and durable handles encourages the use of metal and fiber-based products. However, economic fluctuations and uneven supply chains affect product availability. Manufacturers are focusing on affordable yet durable solutions to cater to expanding urban populations and mid-range housing projects.
Middle East and Africa
The Middle East and Africa held nearly 6% market share in 2024. Growth is fueled by rapid urban development, hospitality expansion, and premium real estate projects in Gulf nations. The UAE and Saudi Arabia drive regional demand for luxury and smart handle designs. Increasing adoption of energy-efficient and decorative hardware in commercial buildings enhances market potential. However, limited awareness in rural areas and economic disparities constrain overall market penetration, though infrastructure investment continues to support steady growth across key cities.
Market Segmentations:
By Type
- Lever Handles
- Door Knobs
- Sliding Door Handles
- Pull Handles
By Material
- Metal
- Plastic
- Fiber
- Others (Wood, Porcelain, etc.)
By Application
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The door handles market is highly competitive, with key players such as Allegion Plc, Sugatsune America, Inc., Kuriki Manufacture Co., Baldwin Hardware, Hoppe Holding AG, Assa Abloy AB, Aarkay Vox, The Häfele Group, West INX Ltd., Kwikset, Emtek Products Inc., and Ace Hardware Corp. leading product innovation and global expansion. The market includes both multinational and regional manufacturers focusing on material advancement, ergonomic design, and integrated security solutions. Companies are investing in research to develop sustainable, smart, and aesthetically refined handles that cater to evolving architectural and consumer trends. Partnerships with construction developers and smart home solution providers are expanding product reach. Manufacturers emphasize high-quality metal finishes, touchless operation, and energy-efficient features to appeal to both residential and commercial sectors. Competitive strength is driven by design innovation, durability, and safety compliance. Growing e-commerce presence, customizable options, and eco-friendly production methods continue to define the industry’s future landscape.
Key Player Analysis
- Allegion Plc
- Sugatsune America, Inc.
- Kuriki Manufacture Co.
- Baldwin Hardware
- Hoppe Holding AG
- Assa Abloy AB
- Aarkay Vox
- The Häfele Group
- West INX Ltd.
- Kwikset
- Emtek Products Inc.
- Ace Hardware Corp.
Recent Developments
- In 2025, Kwikset launched the Mirada collection, which features a reeded lever and handleset.
- In 2024, Aarkay Vox launched a new ball bearing drawer runner from its manufacturing plant, diversifying its hardware offerings beyond door handles.
- In 2023, Baldwin Hardware's Graphite Nickel finish received the "DPHA Door Hardware Product of the Year" award. The finish was praised for its durability and unique fusion of warm and cool tones.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Smart and connected door handles will gain momentum with rising home automation adoption.
- Manufacturers will focus on sustainable materials and recyclable metals to meet green standards.
- Demand for decorative and customizable handles will increase in luxury housing projects.
- Integration of biometric and touchless locking technologies will become a key differentiator.
- Asia Pacific will continue to dominate global demand driven by urbanization and construction growth.
- Rising renovation activities in developed markets will boost replacement handle sales.
- Compact and ergonomic handle designs will attract wider consumer preference.
- Partnerships between hardware and smart tech firms will expand digital handle offerings.
- E-commerce platforms will play a vital role in product visibility and distribution growth.
- Innovation in anti-corrosion and antimicrobial coatings will enhance product longevity and appeal.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Door Handles Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Door Handles Market projected to grow between 2025 and 2032?
Which Door Handles Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Door Handles Market?
Who are the leading companies in the Door Handles Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.14 Billion → 2032: USD 11.4 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Door Handles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Door Handles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Door Handles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Door Handles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Door Handles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Door Handles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Door Handles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Door Handles Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.14 Billion → 2032: USD 11.4 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Door Handles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Door Handles Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Door Handles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Door Handles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

