
Market Overview
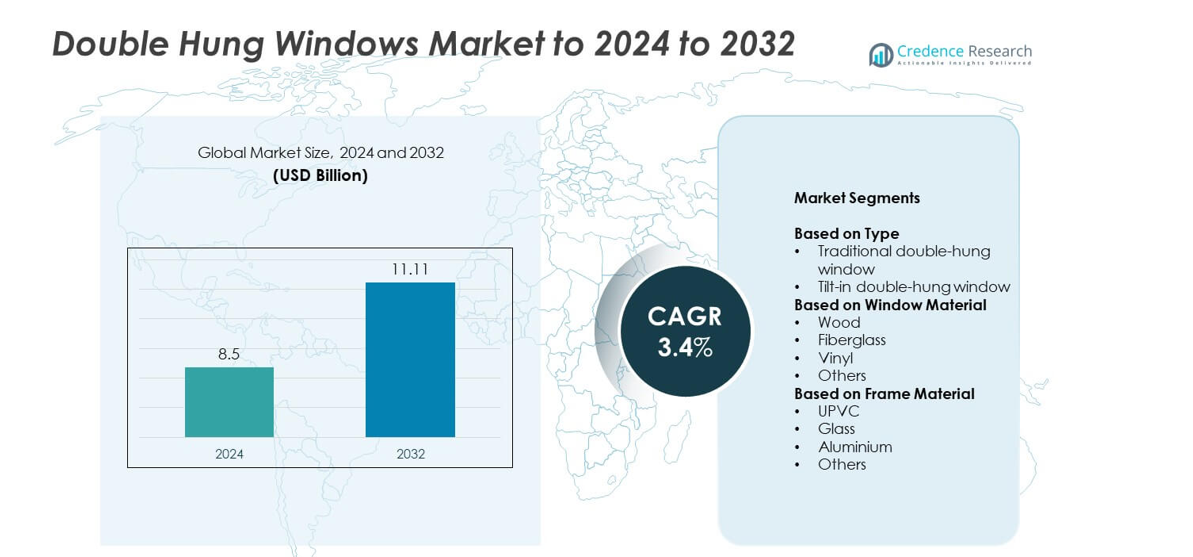
Double Hung Windows Market size was valued at USD 8.5 Billion in 2024 and is anticipated to reach USD 11.11 Billion by 2032, at a CAGR of 3.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Double Hung Windows Market Size 2024 | USD 8.5 Billion |
| Double Hung Windows Market, CAGR | 3.4% |
| Double Hung Windows Market Size 2032 | USD 11.11 Billion |
The double-hung windows market is shaped by major players such as Milgard Windows and Doors, Andersen, Pella, Jeld-Wen, Marvin Windows and Doors, Therma-Tru Doors, and Weather Shield Windows and Doors. These companies dominate through innovation in energy-efficient designs, durable materials, and customizable aesthetics suited for modern and traditional housing. Strategic advancements in UPVC, vinyl, and fiberglass frames enhance thermal performance and sustainability. North America leads the global market with a 37% share in 2024, supported by high renovation activity and stringent building efficiency standards, while Europe and Asia Pacific collectively account for over half of the global demand.
Market Insights
- The double-hung windows market was valued at USD 8.5 billion in 2024 and is projected to reach USD 11.11 billion by 2032, growing at a CAGR of 3.4%.
- Growth is driven by rising demand for energy-efficient housing, increased residential renovation projects, and government initiatives promoting sustainable building materials.
- The tilt-in double-hung window segment accounted for 61% share in 2024, supported by easy maintenance and modern design appeal, while vinyl and UPVC materials continue to dominate due to affordability and insulation benefits.
- The market is competitive with leading companies focusing on product innovation, eco-friendly materials, and digital design tools to enhance customization and compliance with green standards.
- North America led with 37% market share in 2024, followed by Europe at 28% and Asia Pacific at 24%, driven by urban construction growth and energy-efficient housing initiatives across major economies.
Market Segmentation Analysis:
By Type
The tilt-in double-hung window segment dominated the market with a 61% share in 2024. This dominance is driven by its easy cleaning and maintenance features, as both sashes tilt inward for convenient access. Homeowners prefer these windows for improved ventilation and energy efficiency. Growing adoption in residential remodeling projects and energy-efficient home designs further supports demand. Traditional double-hung windows continue to hold steady demand in heritage restorations and classic architecture, but tilt-in designs are becoming the preferred choice for modern, low-maintenance homes.
- For instance,The Harvey Classic vinyl double-hung window features a standard DP40 rating for single units, with specific sizes and configurations performing even better. While the overall line's air infiltration ratings range from 0.03 to 0.14 cfm/ft², testing has shown that certain single units, such as the 48" x 84" model, can achieve ratings as low as 0.01 cfm/ft². This air infiltration performance is significantly better than the industry maximum of 0.30 cfm/ft².
By Window Material
Vinyl-based double-hung windows accounted for the largest share of 54% in 2024. Their popularity stems from high durability, affordability, and strong insulation performance. Vinyl materials resist moisture and temperature fluctuations, making them ideal for diverse climates. Manufacturers focus on UV-resistant and recycled vinyl formulations to meet green-building standards. Wood and fiberglass materials appeal to premium and sustainable housing projects, yet vinyl remains dominant due to low maintenance costs and wide availability across both residential and light commercial applications.
- For instance, VEKA Class-A profiles use 3.0 mm outer walls and ~14% more material than Class-B, improving strength.
By Frame Material
UPVC frames led the segment with a 57% market share in 2024, driven by superior thermal efficiency and cost-effectiveness. These frames offer excellent insulation, corrosion resistance, and easy customization in design and color. Rising demand for energy-efficient window solutions in residential and institutional construction is boosting UPVC adoption. Aluminium and glass frames maintain relevance in modern architecture for aesthetic appeal and structural strength, but UPVC continues to lead due to its recyclability and low lifecycle costs, aligning with global sustainability and building efficiency goals.
Key Growth Drivers
Rising Demand for Energy-Efficient Housing
Growing awareness of energy conservation and sustainability is driving the adoption of double-hung windows with improved insulation and thermal performance. These windows minimize air leakage and support low-energy building designs. Governments and green certification programs encourage energy-efficient materials, boosting replacement and retrofit projects. Homeowners prefer double-hung windows for their dual-pane glass and low-emissivity coatings that enhance indoor comfort while reducing energy costs.
- For instance, Simonton Premium double-hung reports whole-window U-factor 0.29 with argon glass packages
Urbanization and Residential Construction Growth
Rapid urban expansion and increased housing development worldwide are fueling market growth. Builders and developers favor double-hung windows due to their aesthetic appeal, ease of installation, and ventilation control. Expansion of mid-rise and high-rise housing projects has amplified demand for durable and cost-efficient window systems. Increasing investment in smart and sustainable housing further enhances market opportunities for modern, tilt-in double-hung window designs.
- For instance, Andersen states a ground-level full-frame replacement typically takes 4–6 hours per window.
Technological Advancements in Materials and Design
Advancements in materials like UPVC, fiberglass, and insulated vinyl are reshaping product innovation. These materials improve thermal insulation, noise reduction, and weather resistance. Manufacturers integrate features such as low-maintenance coatings and improved locking systems for enhanced security. Growing use of automation in production also reduces costs, enabling large-scale customization. Such innovations increase adoption across both new construction and renovation projects.
Key Trends and Opportunities
Growing Focus on Sustainable Building Materials
Sustainability initiatives are pushing manufacturers toward eco-friendly materials and recyclable window components. Consumers and builders increasingly prefer products with reduced environmental footprints. UPVC and recycled vinyl windows are gaining traction for their durability and low maintenance. The trend aligns with global green certification standards, creating new opportunities for energy-efficient and sustainable double-hung window solutions.
- For instance, The REHAU ARTEVO profile system uses up to 78% recycled content. The ARTEVO Max variant, which includes a LowE film for additional insulation, can achieve a Uf value of up to 0.79 W/m²·K, while the standard ARTEVO profile has a Uf value of up to 0.97 W/m²·K.
Adoption of Smart and Automated Window Systems
The integration of smart technology in double-hung windows is emerging as a new opportunity. Automated control systems enable remote operation, improved ventilation, and better energy regulation. Demand for connected homes encourages manufacturers to incorporate sensors and smart glass technologies. These innovations enhance convenience and align with the growing trend of home automation across developed urban markets.
- For instance, VinylPlus reports 2023 rPVC uptake at 469,916 t, down 16.4% year-over-year.
Key Challenges
High Installation and Replacement Costs
Despite their energy and aesthetic benefits, double-hung windows often involve high installation and replacement expenses. Labor, customized fitting, and premium materials increase overall costs, limiting adoption in cost-sensitive markets. Manufacturers face challenges in maintaining affordability while meeting advanced performance standards, particularly in large-scale housing projects.
Fluctuating Raw Material Prices
Volatility in the prices of raw materials such as aluminum, vinyl, and glass poses a major challenge. Cost fluctuations affect manufacturing budgets and profit margins, leading to supply chain instability. Unpredictable material costs also make long-term pricing strategies difficult, compelling manufacturers to seek alternative sourcing and efficient production techniques.
Regional Analysis
North America
North America held the largest share of 37% in the double-hung windows market in 2024. The region benefits from strong residential renovation activity and widespread adoption of energy-efficient windows. The United States dominates due to high demand for vinyl and UPVC window frames in both new construction and retrofits. Favorable government programs promoting green building materials also drive regional growth. Manufacturers continue to introduce advanced designs that comply with Energy Star standards, supporting long-term demand across suburban and urban housing sectors.
Europe
Europe accounted for a 28% market share in 2024, supported by stringent energy efficiency regulations and a growing trend toward sustainable housing solutions. The United Kingdom, Germany, and France are leading markets due to extensive modernization of residential buildings. Consumers prefer double-hung windows for their insulation properties and aesthetic compatibility with traditional European architecture. Demand for eco-certified and recyclable materials is rising, particularly in Western Europe. Ongoing initiatives to achieve net-zero energy buildings are likely to sustain double-hung window adoption across the region.
Asia Pacific
Asia Pacific captured a 24% market share in 2024, driven by rapid urbanization and expanding residential construction across China, India, and Japan. Rising income levels and government-backed housing programs are accelerating the replacement of traditional window systems with modern, energy-efficient alternatives. Local manufacturers are investing in cost-effective vinyl and UPVC materials to serve growing domestic demand. Increasing awareness of sustainable building solutions and smart home integration further strengthens the region’s market position, particularly in emerging economies with large-scale urban development projects.
Latin America
Latin America held a 7% market share in 2024, with moderate growth driven by urban infrastructure development and residential construction in Brazil and Mexico. Consumers favor double-hung windows for improved ventilation and affordable maintenance. Rising adoption of UPVC and aluminum frames supports market penetration, though high installation costs limit broader uptake. Manufacturers are focusing on durable materials suited to tropical climates. Gradual economic recovery and regional construction investments are expected to enhance market potential in coming years, especially within mid-income housing segments.
Middle East and Africa
The Middle East and Africa region accounted for a 4% market share in 2024. Growth is supported by expanding construction projects in the United Arab Emirates, Saudi Arabia, and South Africa. Increasing preference for insulated and dust-resistant window systems drives adoption in residential and commercial buildings. Energy-efficient UPVC and aluminum-framed double-hung windows are gaining traction in high-temperature zones. However, limited awareness and availability of advanced designs pose challenges. Rising investments in smart city and sustainable housing initiatives are expected to gradually boost market demand.
Market Segmentations:
By Type
- Traditional double-hung window
- Tilt-in double-hung window
By Window Material
- Wood
- Fiberglass
- Vinyl
- Others
By Frame Material
- UPVC
- Glass
- Aluminium
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The double-hung windows market is led by prominent players such as Milgard Windows and Doors, Vinylmax, Kolbe Windows and Doors, Andersen, Weather Shield Windows and Doors, Therma-Tru Doors, Champion Windows, Pella, Jeld-Wen, Window World, Marvin Windows and Doors, American Craftsman, Blair Window and Door, Simonton Windows and Doors, and Harvey Building Products. The market is characterized by strong competition based on product innovation, design flexibility, energy efficiency, and durability. Companies focus on developing high-performance materials like UPVC, vinyl, and fiberglass to enhance thermal insulation and sustainability. Strategic investments in automated manufacturing technologies improve precision and reduce production costs. Many players also emphasize customizable designs and eco-friendly coatings to align with evolving building standards and consumer preferences. Expansion through partnerships with homebuilders and distributors remains a key strategy. Additionally, digital sales platforms and smart home integration capabilities are becoming essential differentiators in a competitive and design-driven market landscape.
Key Player Analysis
- Milgard Windows and Doors
- Vinylmax
- Kolbe Windows and Doors
- Andersen
- Weather Shield Windows and Doors
- Therma-Tru Doors
- Champion Windows
- Pella
- Jeld-Wen
- Window World
- Marvin Windows and Doors
- American Craftsman
- Blair Window and Door
- Simonton Windows and Doors
- Harvey Building Products
Recent Developments
- In 2025, Andersen expands its 100 Series with a new double-hung window, blending timeless design with the durability of Fibrex composite material
- In 2025, Marvin Windows and Doors Announced a new 400,000-square-foot manufacturing facility in Kansas City, Kansas, scheduled to open this year to increase production. The facility is a hub for manufacturing and assembling fiberglass windows and doors, and the company aims to grow its local workforce to 600 by 2028.
- In 2025, Kolbe Windows and Doors Displayed windows with integrated technology, such as privacy glass, at the 2025 International Builders' Show.
Report Coverage
The research report offers an in-depth analysis based on Type, Window Material, Frame Material and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for energy-efficient and low-maintenance window systems will continue to rise.
- Smart window technologies with automated control features will gain wider adoption.
- Manufacturers will invest more in recyclable and eco-friendly window materials.
- Vinyl and UPVC frames will remain the preferred choice for cost-effective construction.
- Renovation and home improvement projects will drive steady replacement demand.
- Integration of double-hung windows in smart homes will enhance product value.
- Asia Pacific will emerge as the fastest-growing regional market.
- Advances in glass coatings will improve insulation and noise reduction performance.
- Customization and aesthetic versatility will attract modern residential buyers.
- Strategic collaborations among manufacturers and builders will expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Double Hung Windows Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Double Hung Windows Market projected to grow between 2025 and 2032?
Which Double Hung Windows Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Double Hung Windows Market?
Who are the leading companies in the Double Hung Windows Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Double Hung Windows Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Double Hung Windows Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8.5 billion → 2032: USD 11.11 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Double Hung Windows Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Double Hung Windows Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Double Hung Windows Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Double Hung Windows Market Drivers
- 3.3 Double Hung Windows Market Restraints & Challenges
- 3.4 Double Hung Windows Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Double Hung Windows Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Double Hung Windows Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Double Hung Windows category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Double Hung Windows Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Double Hung Windows Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Double Hung Windows market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Double Hung Windows Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Double Hung Windows Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Double Hung Windows Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Double Hung Windows (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Double Hung Windows Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Double Hung Windows Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Double Hung Windows Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Double Hung Windows Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Double Hung Windows Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Double Hung Windows Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Double Hung Windows Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Double Hung Windows Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Double Hung Windows Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
