
Market Overview
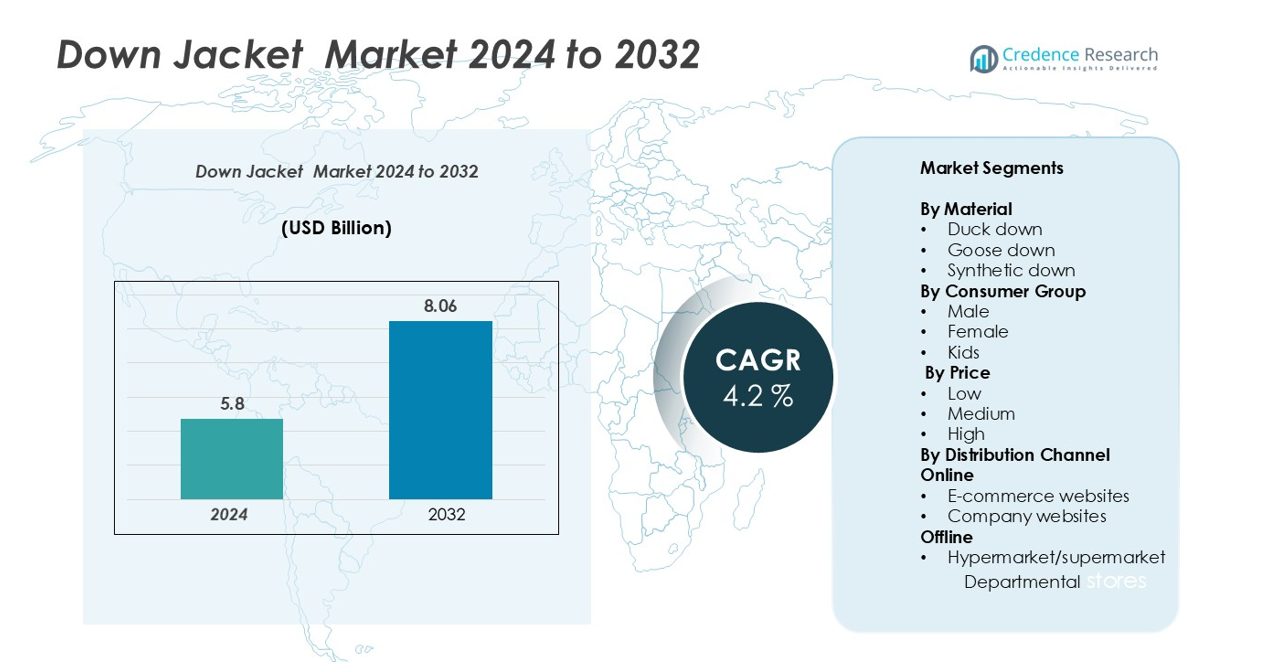
Down jacket market size was valued at USD 5.8 billion in 2024 and is anticipated to reach USD 8.06 billion by 2032, at a CAGR of 4.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Down Jacket Market Size 2024 | USD 5.8 billion |
| Down Jacket Market, CAGR | 4.2% |
| Down Jacket Market Size 2032 | USD 8.06 billion |
The down jacket market is led by prominent brands including Canada Goose, The North Face, Patagonia, Arc’teryx, Columbia Sportswear, Eddie Bauer, Marmot, Helly Hansen, Fjallraven, Black Diamond, Jack Wolfskin, Mountain Hardwear, Rab, Nike, and Mammut. Canada Goose and The North Face dominate the premium segment, leveraging superior insulation, design innovation, and brand recognition. North America holds the largest regional share at approximately 35%, driven by high consumer awareness, cold climates, and strong e-commerce penetration. Europe follows with a 28% share, supported by fashion-conscious consumers and winter sports demand. Asia-Pacific is emerging rapidly, accounting for 22% of the market, fueled by rising disposable incomes and urbanization. Market competition is intensified by product differentiation, technological innovation, and expansion across online and offline distribution channels.
Market Insights
- The global down jacket market was valued at USD 5.8 billion in 2024 and is projected to reach USD 8.06 billion by 2032, growing at a CAGR of 4.2%.
- Rising demand for premium and functional winter apparel, including goose and duck down jackets, is driving market growth across North America, Europe, and Asia-Pacific. Male consumers and the premium price segment account for the largest share, supported by outdoor activity and fashion trends.
- Key trends include increasing adoption of sustainable and ethically sourced materials, integration of smart features, and growth in online and omnichannel retail, which enhances accessibility and personalized shopping experiences.
- The market is highly competitive, led by Canada Goose, The North Face, Patagonia, Arc’teryx, and Columbia Sportswear, with differentiation based on quality, innovation, and brand positioning. High production costs and seasonal demand remain key restraints.
- North America dominates with a 35% market share, followed by Europe at 28% and Asia-Pacific at 22%, while Latin America and MEA account for smaller but growing shares.
Market Segmentation Analysis:
By Material
The down jacket market is segmented by material into duck down, goose down, and synthetic down. Goose down emerges as the dominant sub-segment, capturing a significant market share due to its superior insulation, lightweight nature, and durability. Consumers increasingly prefer goose down for premium winter apparel, driving demand in both urban and high-altitude regions. Synthetic down, while gaining traction for affordability and hypoallergenic properties, remains secondary. The growth in the goose down segment is supported by rising consumer awareness of thermal performance, enhanced cold-weather protection, and brand differentiation strategies by leading manufacturers.
- For instance, Canada Goose reported that its Non-Heavyweight Down sales represented 46% of total revenue in fiscal 2024, up from 43% in fiscal 2023. This increase is a result of the company's strategic focus on expanding its product categories to include more year-round apparel, such as rainwear, knitwear, and footwear, in addition to its traditional heavy-down parkas.
By Consumer Group
The market is segmented into male, female, and kids categories. Male consumers represent the dominant sub-segment, accounting for the largest market share, driven by higher purchasing power and a growing interest in outdoor and sportswear fashion. Female jackets are witnessing steady growth due to increasing adoption of stylish yet functional winter wear, while the kids’ segment benefits from rising parental spending on seasonal apparel. The male segment’s growth is fueled by brand campaigns targeting performance, durability, and lifestyle appeal, alongside expanding availability across both online and offline retail channels.
- For instance, the North Face offers down products with various weights and fill powers, ranging from 550-fill to 900-fill, catering to diverse consumer needs. The 900-fill down is available in extremely limited quantities and primarily in their high-performance Summit Series® gear.
By Distribution Channel
Distribution channels are classified into online and offline networks, with online further divided into e-commerce platforms and company websites, and offline comprising hypermarkets, supermarkets, and departmental stores. Online channels dominate the market, accounting for the highest share, driven by convenience, broader product availability, and personalized shopping experiences. E-commerce websites are particularly influential, offering competitive pricing, easy comparison, and rapid delivery. Offline channels maintain relevance through in-store experiences and immediate product access. The online segment’s growth is underpinned by rising internet penetration, mobile commerce adoption, and targeted digital marketing initiatives.
Key Growth Drivers
Rising Demand for Premium and Functional Winter Apparel
The growing consumer preference for high-performance winter wear is a major driver in the down jacket market. Increasing awareness of thermal efficiency, lightweight insulation, and durability has led consumers to invest in premium goose and duck down jackets. Urban populations in cold climates are particularly inclined toward jackets that combine style with functionality. Brands are responding by innovating with advanced fill power, water-resistant coatings, and ergonomic designs, which further boost market growth. Seasonal fashion trends, coupled with outdoor activities and sports, have expanded usage occasions beyond traditional winter wear. Consequently, manufacturers focusing on product quality and brand positioning are gaining a competitive edge, fueling the adoption of premium down jackets across both online and offline channels globally.
- For instance, the North Face offers Summit Series down jackets, such as the Pumori Down Parka, which feature 800-fill ProDown™ insulation, a water-resistant down that maintains loft and warmth even when damp. These jackets are valued for their high warmth-to-weight ratio and compressibility, making them a suitable choice for alpine mountaineering in cold, dry climates.
Expansion of E-commerce and Omnichannel Retail
E-commerce penetration has significantly transformed the down jacket market, offering consumers access to a wide variety of products, competitive pricing, and convenient delivery options. Online platforms, including e-commerce marketplaces and brand websites, dominate the market by enabling quick comparisons, personalized recommendations, and promotions targeting specific consumer groups. Omnichannel strategies, integrating online and offline touchpoints, allow brands to maintain visibility while catering to changing shopping behaviors. This distribution flexibility supports rapid inventory turnover, expands geographical reach, and attracts younger, digitally savvy consumers. As a result, online retail has become a critical driver for sales growth, particularly for premium and mid-range segments, while offline channels continue to complement with in-store experiences for high-touch product evaluation.
- For instance, Patagonia is a privately held company and as such, it does not publicly release detailed monthly financial reports like online store revenue. However, third-party analytics sources estimate that patagonia.com received approximately 7.57 million visits (sessions) in August 2025.
Rising Outdoor and Adventure Activities
The surge in outdoor recreation, adventure sports, and travel activities is propelling demand for durable and high-performance down jackets. Consumers increasingly prioritize protective apparel suitable for skiing, trekking, hiking, and other cold-weather activities, where insulation and comfort are crucial. This trend is particularly pronounced in North America, Europe, and parts of Asia-Pacific, where lifestyle changes have spurred interest in premium and functional outerwear. Brands leverage this demand by developing specialized collections, using advanced fill materials, ergonomic fits, and water-repellent fabrics. Marketing campaigns highlighting performance, technical specifications, and lifestyle appeal further drive adoption. Consequently, the focus on active and adventure-oriented consumer segments has emerged as a strategic growth lever, boosting both product diversification and market expansion.
Key Trends & Opportunities
Sustainable and Eco-friendly Materials
Sustainability has become a critical trend in the down jacket market, with consumers increasingly favoring eco-friendly and ethically sourced materials. Brands are adopting responsibly sourced goose and duck down, recycled synthetics, and biodegradable packaging to meet consumer expectations and regulatory requirements. This trend provides opportunities for differentiation, particularly among environmentally conscious millennials and Gen Z buyers. Companies investing in transparent supply chains and certifications, such as Responsible Down Standard (RDS), gain trust and enhance brand reputation. The adoption of sustainable practices not only aligns with global environmental initiatives but also drives product innovation, encouraging the development of jackets that are lightweight, durable, and low-impact, expanding market reach and long-term growth potential.
- For instance, Patagonia's Men's Down Sweater Hoody features a NetPlus® 100% postconsumer recycled nylon ripstop shell made from recycled fishing nets and 800-fill-power 100% Responsible Down Standard (RDS) certified goose down, highlighting the brand's commitment to sustainable materials.
Integration of Smart and Functional Features
Technological innovation in down jackets presents opportunities for market expansion through smart features such as temperature regulation, built-in heating elements, and moisture management systems. Brands are integrating wearable technology and performance-enhancing materials to appeal to tech-savvy and active consumers. These advancements improve comfort, safety, and functionality, enhancing the overall value proposition of high-end jackets. Additionally, customization through modular designs, detachable layers, and adjustable insulation offers differentiated experiences, attracting premium buyers. The convergence of fashion, performance, and technology presents a significant growth avenue, allowing manufacturers to command higher margins and expand into niche markets within outdoor and lifestyle segments globally.
- For instance, the PYKRS connected sustainable jacket (specifically the X-TREME Parka model) includes features like app-controlled lighting, heating, and fall detection, made of durable sustainable materials.
Growth in Tier-2 and Tier-3 Markets
Emerging markets in tier-2 and tier-3 cities offer significant opportunities for down jacket brands. Increasing disposable incomes, rising cold-weather awareness, and expanding retail infrastructure in these regions drive adoption of both premium and mid-range products. E-commerce plays a pivotal role in reaching these consumers, while offline stores provide experiential touchpoints to build brand loyalty. Market players focusing on affordable, durable, and stylish options for these regions can capture untapped demand. This expansion strategy allows brands to diversify revenue streams, reduce dependency on saturated urban markets, and leverage localized marketing campaigns, ultimately fostering sustained market growth in previously underserved areas.
Key Challenges
High Production Costs and Price Sensitivity
Down jackets, particularly those using premium goose and duck down, are associated with high production costs due to sourcing, processing, and quality control requirements. These costs often translate into higher retail prices, limiting affordability for certain consumer segments. Price sensitivity is particularly evident in developing markets, where mid-range and low-price jackets dominate. Balancing quality with affordability poses a significant challenge for manufacturers seeking to maintain margins while expanding market penetration. Companies must invest in cost-effective production, supply chain optimization, and strategic pricing models to overcome these barriers without compromising insulation performance and durability, ensuring sustainable growth in competitive markets.
Seasonal Demand and Inventory Management
The down jacket market is highly seasonal, with peak sales concentrated during winter months. This seasonality creates challenges in inventory management, distribution planning, and demand forecasting. Overstocking can lead to markdowns and margin erosion, while understocking risks lost sales and customer dissatisfaction. Rapidly changing fashion trends and varying climate conditions further complicate supply planning. Manufacturers and retailers need agile production schedules, flexible supply chains, and data-driven forecasting systems to mitigate these risks. Efficient inventory management, coupled with strategic promotional campaigns during off-season periods, is essential to maintain revenue stability and optimize operational efficiency.
Regional Analysis
North America
North America holds a leading position in the down jacket market, accounting for a significant share due to high consumer awareness, cold climatic conditions, and strong purchasing power. The U.S. dominates the region, driven by demand for premium goose down jackets and functional outdoor apparel. Canada also contributes substantially, particularly in outdoor and winter sports segments. E-commerce penetration and omnichannel retailing further bolster sales, offering convenience and product variety. Market growth is supported by lifestyle trends emphasizing outdoor recreation and branded apparel. The region’s focus on innovation, quality, and performance jackets positions North America as a key contributor to global market expansion.
Europe
Europe represents a major market for down jackets, with notable shares in Western and Northern Europe. Countries such as Germany, France, and the U.K. lead demand for high-quality goose and duck down jackets, driven by fashion-conscious consumers and outdoor activity enthusiasts. Seasonal variations and cold climates increase the need for thermal wear, while sustainability trends encourage adoption of responsibly sourced materials. Retail expansion through online and offline channels ensures broad product accessibility. Strong brand presence, technological innovation in insulation, and a preference for premium outerwear contribute to Europe’s stable growth, making the region a crucial player in the global down jacket landscape.
Asia-Pacific
The Asia-Pacific region is emerging as a high-growth market for down jackets, capturing a growing market share driven by rising disposable incomes, urbanization, and increasing cold-weather awareness in countries like China, Japan, and South Korea. Youth adoption of fashion-oriented winter apparel and the expansion of e-commerce platforms are key growth catalysts. Seasonal tourism and outdoor activity trends further propel demand for functional and premium jackets. Market players are leveraging localized designs, affordable mid-range products, and targeted marketing to tap into diverse consumer segments. The region’s rapid retail modernization and growing consumer base make it a strategic growth hub.
Latin America
Latin America holds a moderate share in the down jacket market, with Brazil, Argentina, and Chile leading demand. Consumers increasingly favor warm, lightweight, and affordable winter wear in urban and high-altitude regions. Market growth is supported by rising disposable incomes, exposure to international fashion trends, and expanding e-commerce platforms. Localized pricing strategies and mid-range product offerings cater to price-sensitive buyers, while offline retail continues to play an important role in consumer experience. Despite seasonal fluctuations and climatic variations, the region offers opportunities for growth through targeted marketing, expansion into tier-2 cities, and partnerships with local distributors and retail chains.
Middle East & Africa (MEA)
The MEA region holds a smaller yet growing share of the down jacket market, primarily driven by cold-weather pockets in countries like the UAE, Saudi Arabia, and South Africa. Premium and branded jackets see traction among affluent consumers and travelers, while urbanization and rising fashion consciousness contribute to increasing adoption. Seasonal demand and limited winter months influence market cycles, making targeted promotions and e-commerce channels vital for growth. Companies focus on a mix of premium and mid-range products to cater to niche consumer segments. Strategic collaborations with local retailers and online platforms further enhance market penetration in this emerging region.
Market Segmentations:
By Material
- Duck down
- Goose down
- Synthetic down
By Consumer Group
- Male
- Female
- Kids
By Price
- Low
- Medium
- High
By Distribution Channel
- Online
- E-commerce websites
- Company websites
- Offline
- Hypermarket/supermarket
- Departmental stores
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The down jacket market is highly competitive, dominated by established global brands such as Canada Goose, The North Face, Patagonia, Arc’teryx, Columbia Sportswear, and Moncler, alongside emerging regional players. Companies compete through product innovation, quality, and differentiation in materials, including premium goose and duck down or advanced synthetic alternatives. Strategic initiatives such as expanding e-commerce presence, omnichannel retailing, and targeted marketing campaigns strengthen brand visibility and consumer loyalty. Collaborations, limited-edition collections, and sustainability initiatives further enhance competitive positioning. Mid-range and value-focused brands, including Eddie Bauer, Marmot, and Helly Hansen, leverage affordability and functional designs to capture price-sensitive segments. Overall, the market’s competitive landscape is shaped by technological innovation, brand reputation, and consumer preferences for performance, style, and sustainability, driving continuous innovation and expansion across both mature and emerging regions.
Key Player Analysis
- Arc'teryx
- Black Diamond
- Canada Goose
- Columbia Sportswear
- Eddie Bauer
- Fjallraven
- Helly Hansen
- Jack Wolfskin
- Mammut
- Marmot
- Mountain Hardwear
- Nike
- Patagonia
- Rab
- The North Face
Recent Developments
- In December 2024, Helly Hansen introduced its lightest-ever Odin Everdown Hooded Jacket. Designed for mountain professionals seeking lightweight yet warm insulation, the jacket weighs just 325g for men’s large and 275g for women’s medium. This launch highlights Helly Hansen’s commitment to performance-driven innovation, catering to outdoor enthusiasts who demand high-quality, ultra-light insulated gear.
- In September 2022, Dude Perfect, a sports and entertainment organization, joined forces with Columbia Sportswear in a partnership aimed at promoting outdoor activities and encouraging people to spend more time outside. This collaboration marks a celebration of the great outdoors as Dude Perfect and Columbia come together to inspire outdoor enthusiasts.
Report Coverage
The research report offers an in-depth analysis based on Material, Consumer Group, Price, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for premium goose and duck down jackets will continue to grow globally.
- Sustainable and eco-friendly materials will see wider adoption across brands.
- Online and omnichannel retail will become the dominant distribution strategy.
- Asia-Pacific will emerge as a high-growth market with expanding consumer base.
- Technological innovations, including smart and heated jackets, will gain traction.
- Mid-range and affordable segments will expand in emerging markets.
- Seasonal trends will drive limited-edition and fashion-oriented collections.
- Partnerships and collaborations between brands will increase to strengthen market presence.
- Consumer preference for multifunctional and adventure-ready jackets will rise.
- Market competition will intensify, with focus on differentiation through quality, performance, and sustainability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Down jacket market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Down jacket market projected to grow between 2024 and 2032?
Which Down jacket market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Down jacket market?
Who are the leading companies in the Down jacket market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.8 billion → 2032: USD 8.06 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Down Jacket Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Down Jacket Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Down Jacket Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Down Jacket Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Down Jacket Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Down Jacket Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Down Jacket Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Down Jacket Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.8 billion → 2032: USD 8.06 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Down Jacket Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Down Jacket Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Down Jacket Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Down Jacket Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

