
Market Overview:
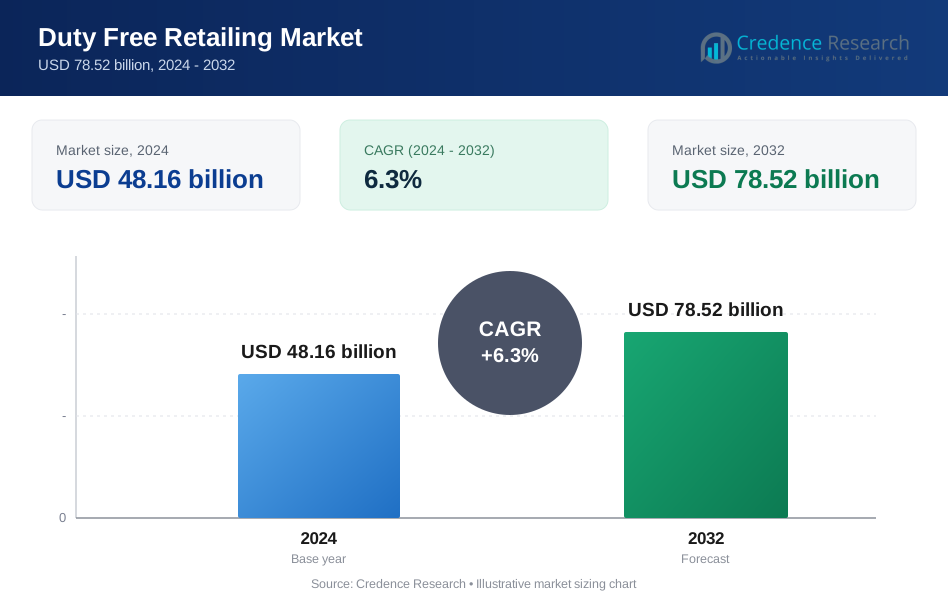
The duty free retailing market size was valued at USD 48.16 billion in 2024 and is anticipated to reach USD 78.52 billion by 2032, at a CAGR of 6.3 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Duty Free Retailing Market Size 2024 | USD 48.16 Billion |
| Duty Free Retailing Market, CAGR | 6.3% |
| Duty Free Retailing Market Size 2032 | USD 78.52 Billion |
Key drivers fueling the duty free retailing market include rising disposable incomes, growing preference for premium and luxury products, and increasing air connectivity worldwide. The expansion of product categories such as cosmetics, perfumes, fashion, liquor, and confectionery further attracts diverse consumer groups. Travel retail operators are also leveraging digital platforms, omnichannel models, and personalized marketing strategies to enhance customer engagement and maximize revenue.
Regionally, Asia Pacific dominates the duty free retailing market, supported by strong tourism in China, South Korea, Japan, and Southeast Asia. Europe remains a key contributor, driven by luxury shopping hubs such as Paris, London, and Rome. The Middle East, particularly the UAE, is emerging as a strategic hub due to Dubai’s position as a global transit destination. North America maintains steady growth, while Latin America and Africa show rising potential through airport expansions and growing tourism flows.
 Market Insights:
- The duty free retailing market was valued at USD 48.16 billion in 2024 and is projected to reach USD 78.52 billion by 2032 at a CAGR of 6.3%.
- Rising global air travel and increasing passenger traffic continue to expand the potential customer base for duty free retailers.
- Growing demand for luxury and premium products, including cosmetics, fragrances, and liquor, fuels consistent sales growth.
- Digital transformation with online pre-order platforms, mobile apps, and loyalty programs enhances customer engagement.
- Tourism growth and airport infrastructure expansion in Asia Pacific, the Middle East, and Europe drive stronger revenue streams.
- Strict regulatory restrictions, high compliance costs, and varying tax policies create significant operational challenges for global retailers.
- Asia Pacific holds 45% share, Europe accounts for 28%, and the Middle East with North America represent 20%, reflecting strong regional dominance in this sector.
Market Drivers:
Rising Global Air Travel and Passenger Traffic:
The steady recovery of international air travel acts as a primary growth driver for the duty free retailing market. Growing passenger volumes at airports increase the potential customer base for retailers. Expanding routes and enhanced connectivity across major regions strengthen demand for travel retail outlets. It benefits from airports evolving into commercial hubs that emphasize shopping alongside travel convenience.
- For instance, Chicago O’Hare International Airport set a new record on July 20, 2025, when over 115,000 passengers passed through security in a single day, reflecting the airport's role as a major travel hub expanding retail opportunities.
Increasing Demand for Luxury and Premium Products:
The growing preference for high-end cosmetics, fragrances, fashion, and liquor significantly fuels the duty free retailing market. International travelers often view duty free stores as destinations for exclusive brands and tax-free luxury purchases. It gains strength from rising disposable incomes and the aspirational spending habits of middle-class consumers. Limited editions and exclusivity in duty free outlets further enhance demand among global travelers.
- For instance, LVMH's Perfumes & Cosmetics division maintained stable revenue of €4.08 billion in the first half of 2025, with Dior's "Sauvage" fragrance remaining the world's best-seller, demonstrating strong brand loyalty and exclusivity commanding a resilient market presence.
Digital Transformation and Omnichannel Retail Strategies:
The adoption of digital technology supports the evolution of the duty free retailing market. Retailers implement online pre-order platforms, mobile applications, and personalized marketing to attract travelers. It benefits from omnichannel models that connect physical stores with digital engagement for improved customer experience. Integration of data analytics enables targeted promotions and loyalty programs, which boost repeat purchases.
Tourism Growth and Expansion of Airport Infrastructure:
The global rise in tourism continues to support strong sales across the duty free retailing market. Expanding airport capacity, modern terminals, and enhanced retail spaces create more opportunities for operators. It thrives in destinations that promote shopping as part of the tourism experience. Investments in infrastructure across Asia Pacific, the Middle East, and Europe further strengthen revenue streams.
Market Trends:
Growing Integration of Digital Platforms and Personalization in Travel Retail:
The adoption of digital technology has become a defining trend in the duty free retailing market. Retailers are introducing pre-order platforms, mobile applications, and data-driven promotions to strengthen customer engagement. It gains momentum from omnichannel retail strategies that link online services with in-store experiences for seamless convenience. Loyalty programs supported by analytics offer personalized rewards that build stronger consumer relationships. Retailers also experiment with virtual product trials and AI-powered recommendations to enhance purchase decisions. This digital shift aligns with evolving traveler expectations for convenience, speed, and tailored experiences in international retail environments.
- For instance, Lagardère Travel Retail's partnership with Inflyter enabled travelers to pre-order duty-free products online, significantly boosting engagement with over 30,000 users adopting the platform within its first year of launch.
Expansion of Sustainable Practices and Diversification of Product Categories:
Sustainability has emerged as a critical trend influencing the duty free retailing market, with consumers demanding eco-friendly products and responsible sourcing. Retailers are introducing organic cosmetics, recyclable packaging, and green-certified goods to align with these values. It strengthens its relevance by targeting health-conscious and environmentally aware travelers. At the same time, operators are diversifying product categories to include electronics, gourmet food, and local cultural items. Exclusive launches and limited editions continue to attract premium buyers seeking unique experiences. Airport operators and retailers are collaborating to expand retail spaces with dedicated zones for sustainable and premium categories, creating new revenue opportunities.
- For instance, Lotte Duty Free implemented biodegradable packaging such as bubble wrap and paper bags, expected to save around 200 tons of vinyl waste annually through this initiative across its Korean distribution network by 2025.
Market Challenges Analysis:
Regulatory Restrictions and Complex Tax Policies:
The duty free retailing market faces challenges from strict regulatory frameworks and varying tax policies across countries. Differences in duty free allowances, customs rules, and import restrictions create barriers for operators. It must adapt business models to comply with multiple regulations, often increasing operational complexity. Stricter government monitoring of cross-border trade also affects pricing flexibility and product availability. These issues reduce efficiency for global retailers aiming to offer consistent experiences. High compliance costs and delays in approvals further weaken profitability for both large and small players.
Intensified Competition and Shifting Consumer Behavior:
The duty free retailing market also encounters rising competition from online platforms and domestic retail outlets. Travelers increasingly compare prices and may prefer convenient online shopping options. It struggles when airport traffic slows due to geopolitical tensions, pandemics, or economic downturns. High rental costs at prime airport locations add pressure to profit margins. Changing consumer behavior toward sustainable products also demands faster adaptation of assortments. Limited differentiation among operators increases price sensitivity, making long-term growth more challenging.
Market Opportunities:
Emergence of New Consumer Segments and Product Categories:
Expanding consumer diversity creates significant growth prospects for the duty free retailing market. Younger travelers seek affordable luxury, while affluent consumers demand exclusivity and personalized service. It benefits from the introduction of sustainable, organic, and health-focused products that align with shifting preferences. Retailers can capture more revenue by expanding categories beyond cosmetics and liquor to electronics, fashion, and gourmet food. Targeted offerings for niche segments such as millennial and Gen Z travelers provide strong opportunities for growth.
Expansion into Emerging Markets and Digital Retail Integration:
Emerging markets in Asia, Latin America, and Africa present attractive opportunities for the duty free retailing market. Rapid urbanization and rising disposable incomes in these regions expand the traveler base. It gains further support from airport expansions and new tourism-focused infrastructure projects. Digital integration through online pre-orders, mobile engagement, and omnichannel retail strategies allows operators to maximize sales opportunities. Retailers that combine physical outlets with advanced digital platforms are positioned to build stronger global footprints and capture long-term demand.
Market Segmentation Analysis:
By Product Category:
The duty free retailing market records strong demand for cosmetics, fragrances, liquor, fashion, and confectionery. Cosmetics and fragrances dominate due to global brand presence and frequent purchases by international travelers. It gains momentum from liquor and tobacco sales, especially in regions with favorable regulations. Fashion and accessories attract high-spending customers seeking exclusive editions. Confectionery maintains steady demand by appealing to both adults and family travelers.
- For instance, Dubai Duty Free reported a 62.7% year-on-year increase in confectionery sales to AED 412.52 million in the first half of 2025 following the launch of its chocolate category in October 2024.
By Distribution Channel:
Airports hold the largest share of the duty free retailing market, driven by high international passenger traffic. It benefits from strategic locations that make shopping convenient for travelers. Downtown duty free stores and border shops contribute to steady revenue growth, particularly in Asia and Europe. Cruise liners and ferries also expand retail opportunities by offering tax-free shopping during international journeys. Online platforms integrated with pre-order services further boost accessibility and customer engagement.
- For instance, Dubai Duty Free recorded over 90 million passengers passing through Dubai International Airport in 2023, enabling it to achieve record-breaking sales and maintain its position as one of the world’s top airport retail operators.
By Consumer Demographics:
The duty free retailing market serves diverse consumer groups, with Millennials and Gen Z emerging as influential buyers. It benefits from their demand for digital engagement, exclusive products, and personalized services. High-income travelers remain the largest revenue contributors due to luxury product purchases. Middle-class consumers contribute steadily through growing disposable incomes and aspirational buying behavior. Business travelers also strengthen sales, particularly in premium categories such as electronics and fashion.
Segmentations:
By Product Category:
- Cosmetics and Fragrances
- Liquor and Tobacco
- Fashion and Accessories
- Confectionery and Food Items
- Electronics and Gadgets
By Distribution Channel:
- Airports
- Downtown Duty Free Stores
- Border Shops
- Cruise Liners and Ferries
- Online Platforms
By Consumer Demographics:
- Millennials
- Gen Z Travelers
- High-Income Consumers
- Middle-Class Consumers
- Business Travelers
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
Asia Pacific:
Asia Pacific holds 45% share of the duty free retailing market, driven by strong tourism flows. China, South Korea, Japan, and Southeast Asia are major hubs supporting retail expansion. It benefits from rising disposable incomes and a strong appetite for luxury and premium products. Airports in Seoul, Shanghai, and Singapore have become leading destinations for duty free shopping. Government-backed investments in tourism and airport modernization further enhance retail opportunities. Retailers expand product offerings to capture both international and domestic travelers across key markets.
Europe:
Europe accounts for 28% share of the duty free retailing market, supported by established shopping traditions. Paris, London, and Rome remain global luxury destinations that attract high spending travelers. It is reinforced by the presence of iconic fashion, fragrance, and liquor brands in regional outlets. Airports in Western Europe provide a strong network of high-value duty free stores. Tourist inflows from Asia and the Middle East contribute to steady demand across European retail hubs. Regional operators are also investing in digital platforms to integrate online and offline engagement.
Middle East and North America:
The Middle East and North America together represent 20% share of the duty free retailing market, supported by transit and tourism strength. Dubai International Airport and Doha Hamad Airport act as major global retail hubs. It thrives in these regions due to strong airport infrastructure and diverse passenger bases. North America benefits from international traffic through airports in New York, Miami, and Los Angeles. Expanding retail spaces and diversified product categories strengthen sales growth across both regions. Retailers leverage the combination of tourism and business travel to maximize revenue opportunities.
Key Player Analysis:
- Relay
- Dufry
- ICF Duty-Free
- DFS Group
- Heinemann
- Aelia Duty-Free
- Travel Retail Norway
- King Power International
- Abu Dhabi Duty-Free
- Duty-Free Americas
- Nuance Group
- Changi Airport Duty-Free
- Flemingo International
Competitive Analysis:
The duty free retailing market is highly competitive, with global and regional players striving to strengthen their market positions. Major companies include Relay, Dufry, ICF Duty-Free, DFS Group, Heinemann, Aelia Duty-Free, Travel Retail Norway, and King Power International. It is shaped by strong brand partnerships, airport concessions, and continuous expansion into new markets. Companies focus on enhancing customer experiences through digital platforms, loyalty programs, and exclusive product offerings. Strategic collaborations with airports and luxury brands help operators secure long-term contracts and high passenger visibility. Competitive intensity also grows with the integration of omnichannel models that blend physical retail with online engagement. Operators are investing in emerging regions and high-traffic airports to expand global footprints while aligning with evolving consumer preferences.
Recent Developments:
- In September 2025, Relay introduced the "Fleet Shield Program," aimed at ending the era of disposable frontline technology by improving operational efficiency and reducing downtime.
- In September 2025, Heinemann Americas launched a new cruise retail concept aboard Star of the Seas featuring exclusive luxury goods
Report Coverage:
The research report offers an in-depth analysis based on Product Category, Distribution Channel, Consumer Demographics and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Luxury and premium product demand will continue to shape the duty free retailing market, with travelers prioritizing exclusivity.
- Digital transformation will accelerate, with mobile apps, pre-order services, and data-driven personalization becoming standard.
- Asia Pacific will remain the leading region, supported by rising outbound travel and expanding airport infrastructure.
- Europe will sustain strong demand, fueled by luxury shopping hubs and high-spending international tourists.
- The Middle East will strengthen its position as a global transit hub with retail-focused airport expansions.
- North America will see steady growth, driven by premium product offerings and major airport upgrades.
- Retailers will diversify into sustainable, eco-friendly, and health-focused categories to align with consumer values.
- Omnichannel strategies will integrate online and offline channels, enhancing convenience and boosting traveler engagement.
- Emerging markets in Latin America and Africa will provide new opportunities through tourism growth and urbanization.
- Strategic partnerships between airports, brands, and retailers will expand global footprints and improve customer experiences.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the duty free retailing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the duty free retailing market projected to grow between 2024 and 2032?
Which duty free retailing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the duty free retailing market?
Who are the leading companies in the duty free retailing market?
Which region commanded the largest share of the duty free retailing market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Duty Free Retailing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Duty Free Retailing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 48.16 billion → 2032: USD 78.52 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Duty Free Retailing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Duty Free Retailing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Duty Free Retailing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Duty Free Retailing Market Drivers
- 3.3 Duty Free Retailing Market Restraints & Challenges
- 3.4 Duty Free Retailing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Duty Free Retailing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Duty Free Retailing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Duty Free Retailing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Duty Free Retailing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Duty Free Retailing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Duty Free Retailing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Duty Free Retailing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Duty Free Retailing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Duty Free Retailing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Duty Free Retailing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Duty Free Retailing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Duty Free Retailing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Duty Free Retailing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Duty Free Retailing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Duty Free Retailing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Duty Free Retailing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Duty Free Retailing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Duty Free Retailing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Duty Free Retailing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
