
Market Overview:
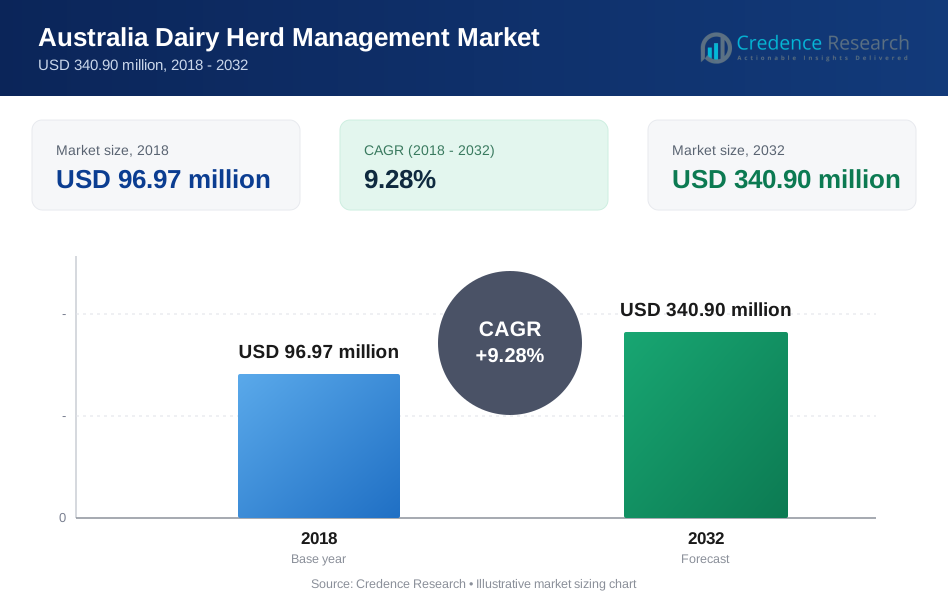
The Australia Dairy Herd Management Market size was valued at USD 96.97 million in 2018 to USD 166.34 million in 2024 and is anticipated to reach USD 340.9 million by 2032, at a CAGR of 9.28% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Dairy Herd Management Market Size 2024 | USD 166.34 million |
| Australia Dairy Herd Management Market, CAGR | 9.28% |
| Australia Dairy Herd Management Market Size 2032 | USD 340.9 million |
Growth in the market is fueled by increasing adoption of automation and precision farming across dairy farms. Farmers are investing in advanced technologies such as automated milking systems, IoT-enabled devices, and cloud-based platforms to improve efficiency and productivity. Rising demand for high-quality dairy products, coupled with government-backed programs supporting digital farming, also plays a significant role in boosting adoption. Labour shortages further encourage the use of automated systems, strengthening the momentum for advanced herd management practices.
Eastern and Southern regions dominate the Australia Dairy Herd Management Market due to strong dairy production hubs and well-developed farm infrastructure. These regions benefit from large-scale farm operations, high export activity, and early adoption of modern herd management tools. Western Australia continues to expand with medium-scale farms embracing breeding and health monitoring systems. Northern and remote areas are emerging with growing interest in mobile-based solutions, supported by government programs addressing connectivity and training challenges. This regional distribution highlights both mature adoption patterns and promising growth opportunities.

Market Insights:
- The Australia Dairy Herd Management Market was valued at USD 96.97 million in 2018, reached USD 166.34 million in 2024, and is projected to hit USD 340.90 million by 2032, growing at a CAGR of 9.28%.
- Eastern and Southern regions lead with 55% share due to strong dairy hubs, established infrastructure, and export-focused production.
- Western Australia follows with 25% share, supported by medium and large-scale farms, while Northern Australia holds 10% share, driven by basic herd monitoring adoption.
- Hardware contributes the largest share, accounting for about 45% of total revenue, supported by demand for milking systems and sensors.
- Software accounts for nearly 35% share, expanding quickly with cloud platforms, while services represent about 20%, growing steadily with training and maintenance support.
Market Drivers:
Rising Demand for Precision Farming and Data-Driven Dairy Practices
The Australia Dairy Herd Management Market benefits from rising adoption of precision farming practices. Farmers increasingly rely on data-driven tools to track herd health, milk yield, and nutrition. Digital solutions enhance decision-making by providing actionable insights. The demand for accurate monitoring systems drives software and sensor integration. It supports efficiency improvements and reduces operational waste. Sustainability concerns further encourage reliance on technology to optimise production. The market grows as farmers recognise the value of data-driven herd management.
- For instance, DeLaval markets its Herd Navigator system for dairy farms to provide early detection of mastitis, ketosis, and reproductive issues by analyzing milk components. The system uses proactive alerts to help farmers identify and treat potential health problems earlier, which can lead to reduced antibiotic use and lower health-related costs.
Government Support and Funding Programs Encouraging Dairy Sector Modernisation
Government initiatives in Australia push for greater efficiency in livestock farming. Subsidies and funding support dairy technology adoption at scale. Rural development programs encourage investment in modern herd management tools. Training and awareness campaigns increase technology penetration among small and mid-sized farmers. Policy support improves digital infrastructure in dairy-rich regions. The Australia Dairy Herd Management Market expands as farmers adopt advanced systems with financial backing. It ensures a faster transition from traditional practices to modern solutions.
- For instance, DataGene, an initiative of Dairy Australia and the broader dairy industry, works to drive genetic gain and herd improvement in the Australian dairy sector, enabling data-driven decisions. They collaborate with partner farms to gather data and implement research findings, such as improved fertility breeding values. DataGene's investments from 2016/17 to 2022/23 delivered an estimated $638 million in net benefits to the Australian dairy industry, with expected future benefits of $342 million from investments between 2023/24 and 2027/28.
Consumer Demand for High-Quality Milk Products Driving Farm Upgrades
Growing consumer preference for premium milk products impacts farm-level operations. Buyers seek assurance on quality, traceability, and sustainability. Farmers respond by upgrading their herd management systems to meet strict standards. Quality monitoring tools provide data that builds consumer trust. The need for consistent output fuels investment in automated feeding and health monitoring systems. Rising exports also create pressure to comply with global standards. The Australia Dairy Herd Management Market benefits from this consumer-driven transformation. It strengthens transparency across supply chains.
Labour Shortages Increasing Need for Automated Herd Management Solutions
Rural labour shortages push dairy farms toward automation. Automated milking systems reduce reliance on manual workforces. Digital platforms simplify routine tasks like feeding schedules and veterinary monitoring. Farmers adopt robotics and sensor-based systems to overcome labour gaps. Cost efficiency improves when automation complements skilled workers. It enables farms to scale operations without hiring large workforces. The Australia Dairy Herd Management Market grows as automation addresses staffing challenges. Technology ensures continuous productivity with minimal interruptions.
Market Trends:
Integration of Artificial Intelligence and Machine Learning in Dairy Analytics
Artificial intelligence drives efficiency in herd health and milk production analysis. Predictive analytics identify disease risks before they spread across herds. Machine learning algorithms optimise feed composition for better output. It ensures customised nutrition planning for different cow groups. Farmers embrace AI to improve yield predictability. The Australia Dairy Herd Management Market uses these tools to manage large data sets. Smart insights support both small farms and large-scale operations.
- For instance, a recent study concluded in August 2025 found that an AI-predicted milk yield model was successfully associated with behavioral parameters in a trial on eight dairy farms in the Netherlands, providing insights into optimizing dairy performance.
Adoption of Cloud-Based Platforms for Real-Time Herd Monitoring
Cloud-based systems gain popularity for centralised data management. Farmers access real-time herd data from any location. These platforms support collaboration among veterinarians, nutritionists, and farm managers. Data security and scalability make them attractive for long-term adoption. The Australia Dairy Herd Management Market benefits from efficient farm-to-cloud integration. Mobile applications enhance farmer engagement with instant updates. Cloud adoption ensures seamless upgrades and reduced dependency on hardware infrastructure.
- For instance,Allflex Australia deployed its SenseHub Dairy cloud platform on farms in Queensland, such as River Ridge Dairies on the Sunshine Coast, enabling live heat and health monitoring that has been reported by farmers to increase heat detection accuracy and improve conception rates.
Expansion of Smart Wearables and IoT Devices for Animal Tracking
Wearable devices improve monitoring of animal movement, health, and fertility cycles. IoT-enabled collars track behavioural changes and stress levels. Real-time alerts notify farmers of abnormal activities. It reduces losses linked to undetected illnesses. Adoption of smart wearables rises with falling sensor costs. The Australia Dairy Herd Management Market integrates IoT for proactive decision-making. Farmers gain reliable data that enhances breeding and productivity.
Growing Focus on Sustainability and Environmentally Friendly Dairy Practices
Environmental concerns push farmers toward eco-friendly herd management solutions. Water conservation tools and waste management systems gain traction. Carbon emission tracking becomes part of dairy operations. It encourages farms to adopt renewable-powered equipment. Consumers reward brands that align with sustainable practices. The Australia Dairy Herd Management Market aligns with national sustainability goals. It drives long-term competitiveness by combining productivity and environmental responsibility.

Market Challenges Analysis:
High Initial Investment Costs and Barriers for Small-Scale Farmers
Adoption of advanced herd management systems requires high upfront costs. Small and mid-sized farmers often lack capital for automation and digital tools. Limited access to financing creates hesitation in adopting new technologies. It restricts large-scale modernisation in the sector. Maintenance and upgrade expenses further raise the financial burden. Farmers in rural areas face challenges in securing loans for advanced systems. The Australia Dairy Herd Management Market faces uneven adoption due to these barriers. Long-term benefits remain clear, but initial costs slow expansion.
Limited Digital Infrastructure and Training Gaps in Rural Regions
Technology adoption depends on reliable internet and power availability. Rural regions in Australia still face infrastructure gaps. Farmers encounter issues with connectivity for real-time monitoring systems. It creates difficulties in using cloud platforms effectively. Lack of training and technical skills also limits usage. Many farmers hesitate to adopt tools without adequate support. The Australia Dairy Herd Management Market experiences slower penetration in remote areas. Bridging digital and knowledge gaps remains a major challenge for growth.
Market Opportunities:
Expansion of Automated and Sensor-Based Solutions Across Mid-Sized Farms
Mid-sized farms increasingly adopt automation to reduce labour costs and improve productivity. Sensor-based systems for health, fertility, and feeding create high adoption potential. Farmers recognise the benefits of data accuracy and timely alerts. It enables them to compete with larger players in efficiency. The Australia Dairy Herd Management Market grows as adoption widens beyond large farms. Automated systems also improve compliance with quality standards. Demand for scalable and affordable solutions creates clear growth opportunities.
Rising Export-Oriented Dairy Production and Focus on Quality Assurance
Australia’s dairy sector continues to expand exports to Asia and the Middle East. Quality assurance standards for export drive investment in modern herd systems. Advanced monitoring tools help ensure compliance with international regulations. It boosts farmer credibility in competitive export markets. The Australia Dairy Herd Management Market benefits from strong global dairy demand. Export-focused strategies push farms toward traceability technologies. Growing international trade ensures sustained opportunities for dairy management providers.
Market Segmentation Analysis:
By Product
The Australia Dairy Herd Management Market is segmented into hardware, software, and services. Hardware such as automated milking systems, feeding devices, and sensors forms the largest share due to strong adoption among large farms. Software platforms gain traction with rising demand for data-driven decision-making and cloud-based herd monitoring. Services expand steadily, supported by training, maintenance, and integration needs across diverse farm sizes. It demonstrates balanced growth across these three categories.
By Application
Key applications include milk harvesting, breeding, feeding, comfort and heat stress management, health management, and others. Milk harvesting remains dominant with strong automation adoption across large-scale farms. Breeding technologies improve productivity and genetic planning, while feeding systems optimise nutrition. Health management solutions rise in demand with increased disease monitoring needs. Comfort and heat stress management supports animal welfare, driving higher milk yields. Other applications include record management and waste control.
- For instance, CRV Australia offers a genomic breeding tool called HerdOptimizer to dairy farms, including those in Victoria. This program is designed to help farmers improve herd traits, including fertility, with the potential to reduce average calving intervals.
By End User
End users comprise large-scale, medium-scale, and small-scale dairy farms. Large-scale farms lead adoption with advanced hardware and automated platforms. Medium-scale farms increasingly embrace affordable cloud and sensor solutions. Small-scale farms face barriers but gradually shift toward basic herd monitoring services. It highlights varied adoption patterns across farm sizes.
By Region (Trade & Commerce Analysis)
Regional trade includes import and export analysis. Imports focus on advanced equipment and software tools sourced from global suppliers. Exports strengthen as Australia delivers high-quality dairy products to Asia-Pacific and Middle East markets. It reflects the role of trade in expanding technology penetration and dairy industry competitiveness.

Segmentation:
By Product
- Hardware
- Software
- Services
By Application
- Milk Harvesting
- Breeding
- Feeding
- Comfort and Heat Stress Management
- Health Management
- Others
By End User
- Large-Scale Dairy Farms
- Medium-Scale Dairy Farms
- Small-Scale Dairy Farms
By Region (Trade & Commerce Analysis)
- Import Analysis by Region
- Export Analysis by Region
Regional Analysis:
Regional Performance in Eastern and Southern Australia
Eastern and Southern Australia dominate the Australia Dairy Herd Management Market with nearly 55% share. Strong dairy production hubs in Victoria, New South Wales, and Tasmania drive this lead. Large-scale farms in these states adopt advanced hardware such as automated milking systems and feeding devices. It benefits from strong government support and research programs encouraging digital farming. Export-oriented dairy production in Southern Australia further strengthens market demand. The region’s well-developed infrastructure supports cloud platforms and IoT adoption. Growth in herd productivity and sustainability initiatives continues to fuel technology penetration.
Market Dynamics in Western and Northern Australia
Western Australia accounts for about 25% of market share, supported by medium and large-scale farms. Dairy operators adopt herd health management and breeding technologies to enhance efficiency. Import dependence on software and automation solutions remains high in this region. It faces infrastructure challenges but continues to expand through trade partnerships. Northern Australia contributes close to 10% market share, with small farms dominating the landscape. Farmers rely on basic monitoring systems with gradual movement toward cloud-based solutions. Climate conditions encourage investment in comfort and heat stress management applications.
Emerging Growth in Central and Remote Regions
Central and remote regions together hold nearly 10% market share in the Australia Dairy Herd Management Market. Limited digital infrastructure restricts the adoption of advanced herd management tools. It still sees growth in demand for mobile-based platforms that function with low connectivity. Small-scale farms dominate, but government support programs help bridge gaps in training and access. Rising emphasis on sustainable practices increases adoption of basic feeding and health management systems. Export potential also encourages gradual modernisation among farmers in these areas. Long-term growth depends on infrastructure improvements and stronger funding support.
Key Player Analysis:
- Dairy Australia Limited
- DeLaval
- VAS
- Jantec Systems
- Afimilk Ltd.
- UNIFORM-Agri
- GEA Group Aktiengesellschaft
- Fullwood JOZ
- Easy Dairy Automation Systems
Competitive Analysis:
The Australia Dairy Herd Management Market features a competitive landscape shaped by global leaders and regional specialists. International players such as DeLaval, GEA Group, and Afimilk dominate with advanced hardware and software solutions. Local firms including Easy Dairy Automation Systems and Dairy Australia Limited strengthen their presence through tailored services and farmer-focused programs. It is characterised by a mix of established brands with broad portfolios and niche players offering cost-effective solutions. Competition focuses on innovation in cloud platforms, IoT-enabled devices, and automated milking systems. Companies invest heavily in R&D to maintain technological leadership. Partnerships with cooperatives and government initiatives further reinforce competitive positioning. The market remains dynamic, with firms competing on pricing, reliability, and aftersales services.
Recent Developments:
- In September 2025, DeLaval and John Deere launched the strategic Milk Sustainability Center (MSC), a digital ecosystem partnering also with dsm-firmenich to empower dairy producers with real-time sustainability analytics and farm management insights for Australia and global markets.
- In September 2025, UNIFORM-Agri announced the acquisition of Egam and BelExpert software from Elda, advancing its dairy herd management offerings in Australia and strengthening support for local producers.
Report Coverage:
The research report offers an in-depth analysis based on product, application, end user, and regional trade segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Automation will remain a key focus, with higher adoption of milking and feeding systems.
- Cloud-based herd management platforms will expand among medium-scale farms.
- AI-driven analytics will enhance predictive insights for health and fertility monitoring.
- Export-oriented production will push adoption of traceability and compliance solutions.
- Local firms will gain market share by offering affordable, tailored services.
- IoT-enabled wearables will see stronger adoption to track real-time animal behaviour.
- Government-backed digital programs will accelerate adoption across rural areas.
- Sustainability goals will drive investment in eco-friendly herd management tools.
- Partnerships between global players and cooperatives will expand regional reach.
- Rising consumer demand for quality dairy will fuel investment in modern systems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Adoption of Automation and Precision Farming
Australian dairy farms are increasingly investing in automated milking systems, IoT devices, and precision farming tools to improve operational efficiency and productivity, driven by the need to optimize resources and reduce manual labor.
Government Support and Funding Programs
Subsidies, rural development initiatives, and digital infrastructure investments from the Australian government are accelerating the adoption of advanced herd management technologies, especially among small and medium-sized farms.
Rising Demand for High-Quality and Traceable Dairy Products
Consumer preference for premium, traceable, and sustainably produced milk is pushing farms to upgrade herd management systems, ensuring compliance with quality standards and boosting export competitiveness.
Labour Shortages in Rural Areas
Persistent labor shortages in rural Australia are compelling dairy farms to adopt automated and digital herd management solutions, enabling them to maintain productivity and scale operations with fewer workers.
Expansion of Export-Oriented Dairy Production
Australia’s growing dairy exports to Asia and the Middle East are driving investments in modern herd management systems that support traceability, compliance, and consistent product quality, strengthening the sector’s global position.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Australia Dairy Herd Management Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Dairy Herd Management Market projected to grow between 2024 and 2032?
Which Australia Dairy Herd Management Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Dairy Herd Management Market?
Who are the leading companies in the Australia Dairy Herd Management Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By End User
- 1.3.1 Large-Scale Dairy Farms
- 1.3.2 Medium-Scale Dairy Farms
- 1.3.3 Small-Scale Dairy Farms
- 1.4 By Application
- 1.4.1 Milk Harvesting
- 1.4.2 Breeding
- 1.4.3 Feeding
- 1.4.4 Comfort and Heat Stress Management
- 1.4.5 Health Management
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 96.97 million → 2032: USD 340.90 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Dairy Herd Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Dairy Herd Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Dairy Herd Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Dairy Herd Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Dairy Herd Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Dairy Herd Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Dairy Herd Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Dairy Herd Management Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 96.97 million → 2032: USD 340.90 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Dairy Herd Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Large-Scale Dairy Farms
- 12.4.7.2 Medium-Scale Dairy Farms
- 12.4.7.3 Small-Scale Dairy Farms
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Milk Harvesting
- 12.5.7.2 Breeding
- 12.5.7.3 Feeding
- 12.5.7.4 Comfort and Heat Stress Management
- 12.5.7.5 Health Management
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Dairy Herd Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Dairy Herd Management Geographic Market Outlook, 2018-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2018-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Dairy Herd Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Dairy Herd Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dairy Australia Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DeLaval
- 18.4 VAS
- 18.5 Jantec Systems
- 18.6 Afimilk Ltd.
- 18.7 UNIFORM-Agri
- 18.8 GEA Group Aktiengesellschaft
- 18.9 Fullwood JOZ
- 18.10 Easy Dairy Automation Systems
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

