
Market Overview:
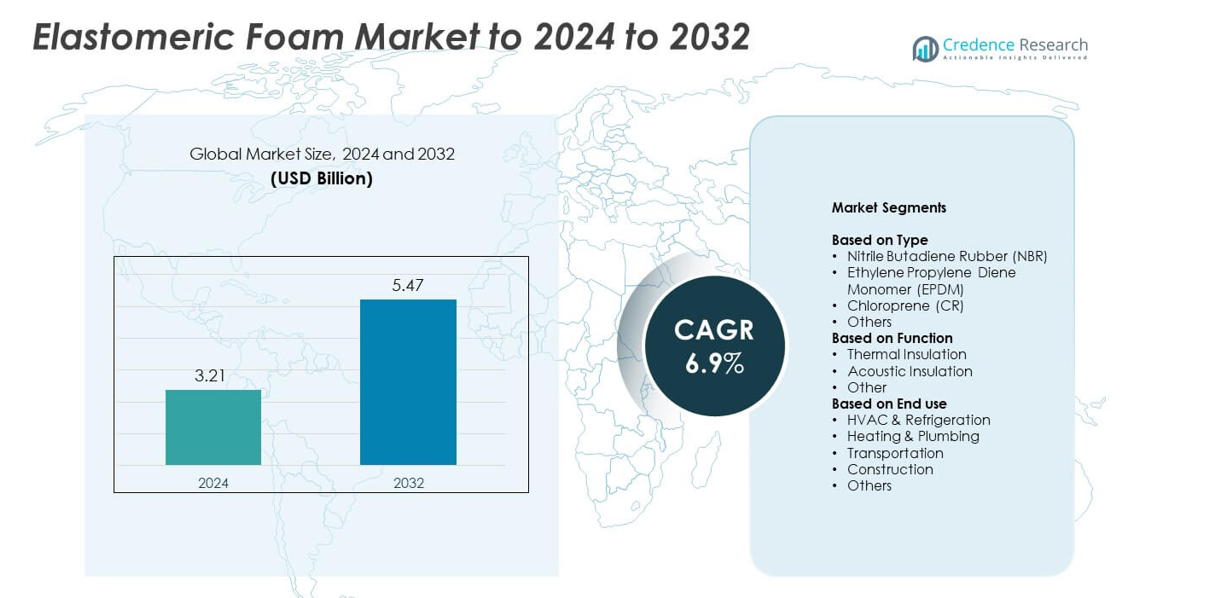
Elastomeric Foam Market size was valued at USD 3.21 billion in 2024 and is anticipated to reach USD 5.47 billion by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Elastomeric Foam Market Size 2024 | USD 3.21 billion |
| Elastomeric Foam Market, CAGR | 6.9% |
| Elastomeric Foam Market Size 2032 | USD 5.47 billion |
The elastomeric foam market is led by established players that focus on high-performance insulation solutions and strong global distribution. Key participants emphasize advanced thermal and acoustic insulation materials that meet energy-efficient building standards and industrial requirements. Their strategies center on product innovation, capacity expansion and compliance with strict fire-safety and environmental regulations. Asia Pacific stands as the leading region with a 38% market share, supported by large-scale construction, strong HVAC demand and rapid industrial growth. North America follows with a 30% share due to strict efficiency regulations and widespread adoption in commercial buildings, while Europe holds a 22% share driven by retrofit activity and regulatory compliance.
Market Insights
- The elastomeric foam market was valued at USD 3.21 billion in 2024 and is projected to reach USD 5.47 billion by 2032, growing at a CAGR of 6.9%. • Demand rises due to strong adoption in HVAC and refrigeration, where the dominant segment holds a 52% share driven by energy-efficient cooling systems and moisture-resistant insulation needs. • Key trends include rapid uptake of non-halogenated, low-emission foam and growing use in electric vehicles for thermal and acoustic management, supported by advancements in automated manufacturing. • Competition remains strong as major producers expand capacity, improve fire-safe formulations and strengthen distribution, while facing restraints from raw-material price fluctuations and competition from alternative insulation materials. • Asia Pacific leads with a 38% regional share due to construction and HVAC growth, followed by North America at 30% with strict efficiency standards, while Europe holds 22% supported by retrofit activity and insulation-focused regulations.
Market Segmentation Analysis:
By Type
Nitrile Butadiene Rubber holds the dominant position in the elastomeric foam market with a 46% share. NBR leads due to strong resistance to oils, chemicals, and moisture, which makes it suitable for HVAC, refrigeration, and industrial insulation. Its flexibility and durability support demand across temperature-sensitive applications. EPDM expands in outdoor and high-heat environments because of its strong weathering resistance, while CR finds use in specialized insulation tasks. Steady adoption across industrial facilities and commercial buildings strengthens NBR’s leadership as manufacturers prioritize performance and long service life.
- For instance, Armacell operates 26 manufacturing plants across 20 countries, enabling high-volume NBR insulation production supported by global supply reliability.
By Function
Thermal insulation is the leading function in the elastomeric foam market with a 68% share. This segment dominates due to rising use in HVAC systems, refrigeration lines, and industrial equipment where heat loss control and energy savings are crucial. The focus on meeting building efficiency codes boosts demand for thermal-grade elastomeric foams. Acoustic insulation grows in commercial buildings and transportation, driven by rising noise-control requirements. The broader shift toward energy-efficient infrastructure keeps thermal insulation ahead as the preferred application across residential, commercial, and industrial projects.
- For instance, K-FLEXsupplies insulation products through 14 global production facilities and distributes to more than 63 countries (served by 63 distribution areas and 25 sales offices), supporting thermal insulation availability at scale.
By End Use
HVAC and refrigeration hold the largest share in the elastomeric foam market at 52%. This dominance comes from extensive use in air-conditioning ducts, chilled-water pipes, and refrigeration lines that require moisture resistance and thermal stability. The sector benefits from rising global construction and strong replacement demand in commercial buildings. Heating and plumbing expand with growth in residential upgrades, while transportation uses foams for vibration control and thermal management. Increasing installation of energy-efficient cooling systems keeps HVAC and refrigeration as the primary consumer of elastomeric foam.
Key Growth Drivers
Rising Demand for Energy-Efficient HVAC Systems
Energy-efficient HVAC systems push strong demand for elastomeric foam. The material reduces heat loss and supports stable system performance. Strict building efficiency rules encourage wider use in commercial and residential projects. Many developers shift toward insulation materials that cut energy use. This trend strengthens long-term adoption across global construction markets.
- For instance, Johnson Controls is a leader in building technologies and solutions, and its 2023 Sustainability Report focuses on broader metrics such as reducing absolute operational emissions by 42% since 2017 and cutting customer emissions by 14% since 2017, using integrated solutions across various public and private sectors in multiple countries rather than a single, reported global figure of 1,200 modernized projects in that specific year.
Expansion of Cold-Chain Logistics and Refrigeration
Growth in food storage, pharmaceuticals, and frozen transport increases the need for reliable insulation. Elastomeric foam offers strong moisture control and stable thermal resistance. Cold-chain operators choose these materials to avoid condensation issues and maintain temperature accuracy. Rising vaccine transport and processed food trade add steady demand. This expansion boosts consumption across industrial refrigeration systems.
- For instance, As of May 2023, Schneider Electric reported a network of over 180 factories and almost 90 distribution centers, totaling around 270 sites.
Growth of Industrial and Infrastructure Projects
Industrial plants, data centers, and large utilities require insulation for safety and efficiency. Elastomeric foam handles vibration, temperature change, and moisture exposure in these settings. Infrastructure expansion in developing regions drives strong installation rates. Many facilities replace older insulation with higher-performance materials. This shift supports broad market growth across heavy-duty applications.
Key Trends and Opportunities
Shift Toward Non-Halogenated and Low-Emission Foam Grades
Many users prefer low-emission and non-halogenated foam due to safety needs. Green building rules expand demand for cleaner insulation materials. Manufacturers upgrade formulations to reduce VOC levels and meet global environmental standards. These improvements help win acceptance in sensitive spaces such as hospitals and schools. This trend creates strong long-term opportunities for high-purity elastomeric foam.
- For instance, Saint-Gobain insulation products meet stringent VOC emission thresholds under various international environmental compliance programs, with specific product lines certified to emit very low levels, often below 10 µg/m³ for Total Volatile Organic Compounds (TVOC) when tested according to standards such as the French A+ classification (ISO 16000).
Rising Use in Electric Vehicles and Modern Mobility Systems
Growth in electric vehicles increases demand for thermal and acoustic insulation. Elastomeric foam supports battery temperature control and reduces cabin noise. Mobility producers value its light weight and fire-resistant structure. EV manufacturing growth in Asia, Europe, and the US expands market potential. This creates a new opportunity outside traditional HVAC and refrigeration sectors.
- For instance, BYD delivered 3.02 million electric vehicles in 2023, increasing consumption of specialized insulation materials used in battery and cabin systems.
Adoption of Advanced Manufacturing and Automation
Producers adopt automated cutting, extrusion, and continuous foaming systems. These upgrades deliver consistent thickness and better performance. Automation reduces waste and improves distribution capacity. Large buyers prefer suppliers with predictable quality and fast output. This shift opens opportunities for global scale production.
Key Challenges
Fluctuating Raw Material Prices
Prices of synthetic rubber feedstocks change due to oil market shifts. These variations affect production cost and reduce pricing stability. Many manufacturers face pressure when large contracts require fixed rates. Some shift to blended or optimized formulations, yet volatility remains high. This challenge affects margins across global supply chains.
Competition from Alternative Insulation Materials
Mineral wool, polyurethane foam, and fiberglass compete in many sectors. Some alternatives offer lower upfront cost or higher temperature resistance. Buyers sometimes choose these options in industrial and construction projects. This competition pressures manufacturers to improve performance and reduce lifecycle cost. The challenge continues as new materials enter the market.
Regional Analysis
North America
The North America region commands around 30% of the global elastomeric foam market share, driven by strong insulation demand in HVAC, refrigeration, and automotive sectors. The United States leads with stringent energy-efficiency regulations and large infrastructure investments that support foam adoption. Canada follows with increasing retrofit projects in commercial buildings. Regional manufacturers benefit from integrated raw material supply chains, which boost production efficiency. Growth remains supported by shift toward green buildings and electric vehicle insulation. Nonetheless, the market faces cost pressures from feedstock volatility and shifting trade policies.
Europe
Europe accounts for about 22% of the global elastomeric foam market share, thanks to robust demand in the construction and automotive sectors. Germany, France and the UK lead due to focus on energy efficient building standards and noise-proofing needs in transport. Manufacturers in the region invest in halogen-free and fire-safe insulation grades to comply with EU regulations. The mature market drives incremental innovation rather than high growth. While opportunities exist in retrofit and infrastructure upgrade programs, competition from alternative insulation materials and raw material cost pressures remain notable challenges.
Asia Pacific
The Asia Pacific region leads with a market share of approximately 38%, driven by rapid urbanisation, infrastructure development and strong HVAC growth across China, India and Southeast Asia. Lower labour costs and local manufacturing capacities enhance competitiveness for foam producers. Governments promote energy-efficient building codes and cold-chain logistics expansions, creating new foam demand. Emerging automotive manufacturing hubs also favour elastomeric foam for thermal and acoustic insulation needs. The region presents the highest growth potential, though raw material supply chain constraints and quality standard gaps pose interim obstacles.
Latin America Latin America holds near 6% of the global elastomeric foam market share, with Brazil and Mexico as key contributors. Growing investments in commercial construction and HVAC systems support demand, albeit at a slower pace compared to mature regions. Manufacturers target retrofit projects in older buildings and modest infrastructure upgrades. While foam adoption remains moderate, rising awareness of insulation benefits offers growth potential. Challenges include under-penetration of advanced insulation standards and higher impact of economic volatility on building investments.
Middle East & Africa
The Middle East & Africa region covers around 4% of the global elastomeric foam market share, fueled by infrastructure expansion, oil & gas sector growth and commercial real-estate development. High climate demands intensify the need for thermal insulation in HVAC and refrigeration systems. Foam manufacturers increasingly serve construction and industrial projects in GCC countries and South Africa. However, market growth is constrained by lower insulation awareness, fragmented regulation, and greater dependence on imports, which elevates costs and limits adoption speed.
Market Segmentations:
By Type
- Nitrile Butadiene Rubber (NBR)
- Ethylene Propylene Diene Monomer (EPDM)
- Chloroprene (CR)
- Others
By Function
- Thermal Insulation
- Acoustic Insulation
- Other
By End use
- HVAC & Refrigeration
- Heating & Plumbing
- Transportation
- Construction
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the elastomeric foam market features leading companies such as NMC SA, Hira Industries, Armacell International S.A., Kaimann GmbH, Huamei Energy-Saving Technology Group Co., Ltd., Aeroflex USA, L'isolante K-Flex S.P.A., Roka Yalitim, Anavid Insulation Products Kiryat Anavim Ltd., and Jinan Retex Industries Inc. The market remains highly competitive due to strong demand from HVAC, refrigeration, construction and industrial applications. Manufacturers focus on producing high-performance insulation materials with improved thermal resistance, moisture control, low VOC emissions and fire safety compliance. Many producers expand capacity, adopt automated systems and strengthen distribution networks to meet rising global demand. Product differentiation often depends on technical performance, durability, and compliance with regional building standards. Companies also invest in R&D to develop non-halogenated, sustainable and energy-efficient insulation solutions. Growing emphasis on energy-efficient buildings, cold-chain logistics and industrial expansion continues to intensify competition across regions.
Key Player Analysis
- NMC SA
- Hira Industries
- Armacell International S.A.
- Kaimann GmbH
- Huamei Energy-Saving Technology Group Co., Ltd.
- Aeroflex USA
- L'isolante K-Flex S.P.A.
- Roka Yalitim
- Anavid Insulation Products Kiryat Anavim Ltd.
- Jinan Retex Industries Inc
Recent Developments
- In 2025, Armacell introduced ArmaGel XGC, a next-generation cryogenic and dual-temperature aerogel blanket that sets a new industry standard by combining superior insulation efficiency with improved worker safety through proprietary low-dust technology.
- In 2025, Armacell released an updated Environmental Product Declaration (EPD) for ArmaFlex FRV. This flexible elastomeric insulation product, designed for HVAC and refrigeration systems, includes documentation for its life-cycle environmental profile under the standards EN 15804 and ISO 14025
- In 2023, Aeroflex USA promoted AEROFLEX Breathe-EZ EPDM duct insulation, a fiber-free closed-cell elastomeric foam liner and wrap for HVAC systems, highlighting compliance with ASTM E84 / UL 723 25/50, CDPH 01350 low-VOC criteria and multiple ASHRAE / IECC energy-code requirements.
Report Coverage
The research report offers an in-depth analysis based on Type, Function, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily as global HVAC adoption increases.
- Energy-efficient building rules will push higher use of advanced insulation.
- Cold-chain expansion will raise demand from food, pharma and logistics sectors.
- Manufacturers will invest more in halogen-free and low-emission foam grades.
- Automation in production will improve quality and reduce material waste.
- Electric vehicles will create new opportunities for thermal and acoustic insulation.
- Infrastructure upgrades in developing regions will support long-term demand.
- Rising focus on moisture-resistant materials will strengthen foam adoption.
- Partnerships between foam producers and HVAC OEMs will expand product reach.
- Increased replacement of aging insulation systems will add recurring demand.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Elastomeric Foam Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Elastomeric Foam Market projected to grow between 2025 and 2032?
Which Elastomeric Foam Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Elastomeric Foam Market?
Who are the leading companies in the Elastomeric Foam Market?
Which region commanded the largest share of the Elastomeric Foam Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.21 billion → 2032: USD 5.47 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Elastomeric Foam Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Elastomeric Foam Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Elastomeric Foam Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Elastomeric Foam Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Elastomeric Foam Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Elastomeric Foam Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Elastomeric Foam Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Elastomeric Foam Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.21 billion → 2032: USD 5.47 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Elastomeric Foam Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Elastomeric Foam Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Elastomeric Foam Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Elastomeric Foam Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

