
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Construction Equipment Market Size 2024 | USD 12,169 Million |
| Electric Construction Equipment Market, CAGR | 11.14% |
| Electric Construction Equipment Market Size 2032 | USD 28,328.13 Million |
Market Overview:
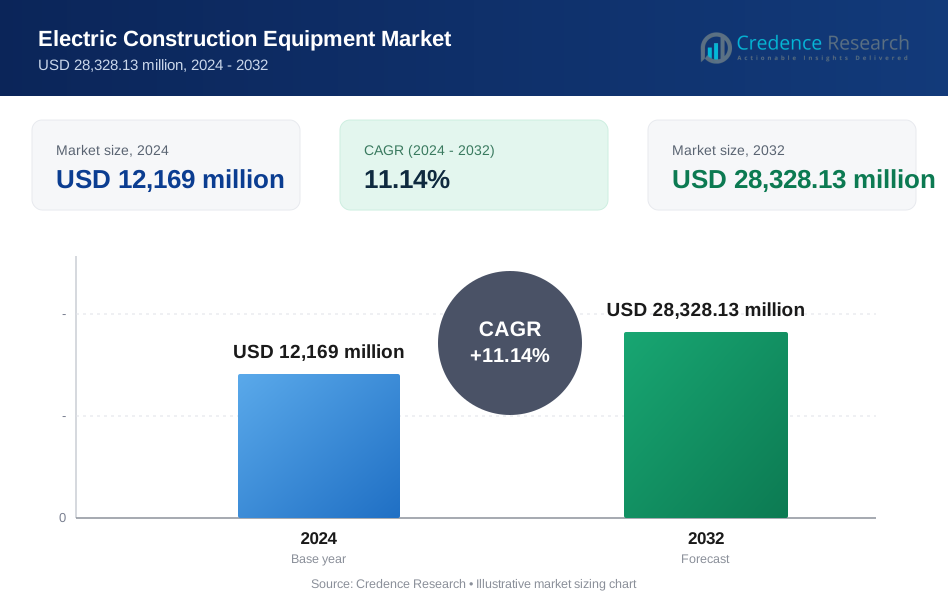
The Electric Construction Equipment Market is projected to grow from USD 12,169 million in 2024 to USD 28,328.13 million by 2032, with a compound annual growth rate (CAGR) of 11.14%.
The Electric Construction Equipment Market is driven by increasing demand for eco-friendly and sustainable construction solutions, along with stringent emissions regulations in several regions. Growing awareness of environmental concerns has accelerated the adoption of electric equipment, which offers zero emissions and reduced noise levels, making it ideal for urban projects. Technological advancements in battery technology, such as improved energy storage capacity and faster charging solutions, are further propelling market growth. Additionally, the rising costs of fossil fuels and the economic benefits of low operating costs associated with electric machinery are encouraging construction companies to transition from traditional diesel-powered equipment. Increasing investments in infrastructure development and smart cities are also contributing to the market's expansion. Moreover, manufacturers' focus on innovation, such as hybrid models and autonomous equipment integration, is shaping emerging trends in the industry, creating a competitive landscape aimed at enhancing efficiency, sustainability, and long-term profitability for construction companies globally.
The Electric Construction Equipment Market is geographically diverse, with North America, Europe, Asia-Pacific, and the Rest of the World (RoW) driving growth. North America, with around 30% of the market share in 2024, is driven by strict emissions regulations and a focus on sustainable infrastructure. Europe, holding nearly 25% of the market, benefits from strong government support for eco-friendly construction, especially in Germany, the UK, and France. Asia-Pacific leads the market with 35% share, fueled by rapid urbanization and infrastructure development in China, India, and Japan. The Rest of the World, capturing around 10%, is gaining traction with green initiatives in the Middle East, Africa, and Latin America. Key players, including Komatsu, Caterpillar, Volvo Construction Equipment, and Hitachi Construction Machinery, are expanding their presence across these regions.
Market Insights:
- The Electric Construction Equipment Market is projected to grow from USD 12,169 million in 2024 to USD 28,328.13 million by 2032, with a CAGR of 11.14%.
- Increasing demand for eco-friendly construction solutions and stringent emissions regulations are driving the market’s expansion.
- Advancements in battery technology, such as improved energy density and faster charging solutions, are propelling the adoption of electric construction machinery.
- Rising fossil fuel costs and the cost efficiency of electric equipment are encouraging companies to transition from diesel-powered machinery.
- Rapid urbanization and infrastructure development, particularly in smart city projects, are fueling demand for electric construction equipment globally.
- North America, Europe, Asia-Pacific, and the Rest of the World are key regions contributing to market growth, with Asia-Pacific projected to hold 35% of the market in 2024.
- Leading manufacturers like Komatsu, Caterpillar, Volvo Construction Equipment, and Hitachi Construction Machinery are focusing on innovation and expanding their presence across diverse regions.
Market Drivers:
Growing Demand for Sustainable Construction Solutions:
One of the key drivers in the Electric Construction Equipment Market is the increasing demand for sustainable and environmentally friendly construction practices. Governments worldwide are implementing stringent regulations aimed at reducing greenhouse gas emissions, driving companies to adopt electric machinery that produces zero emissions. This shift is particularly prominent in urban areas where reducing air pollution and noise is a priority. For instance, Volvo Construction Equipment has introduced a range of electric compact excavators and loaders that produce zero emissions and significantly reduce noise pollution in urban projects. The push for sustainable infrastructure, alongside the growing awareness of climate change, has created strong incentives for the use of electric equipment in construction projects.
Advancements in Battery Technology:
Technological advancements in battery technology are significantly boosting the adoption of electric construction equipment. Improvements in battery energy density, charging speed, and durability have enhanced the performance of electric machinery, allowing it to compete with, and even outperform, traditional diesel-powered equipment in certain applications. For instance, Caterpillar has developed electric excavators powered by advanced lithium-ion batteries that feature rapid charging capabilities, enabling continuous operation for extended periods. The development of fast-charging solutions and extended battery life reduces downtime, making electric equipment a more viable option for large-scale, long-duration construction projects.
Cost Efficiency and Lower Operating Costs:
Electric construction equipment offers significant cost savings in terms of fuel and maintenance compared to its diesel counterparts. As the cost of fossil fuels continues to rise, electric equipment becomes a more attractive option due to its lower operating costs. The reduced number of moving parts in electric engines also results in lower maintenance requirements and longer machine life. For instance, Komatsu’s line of electric mini-excavators requires minimal maintenance and offers significant fuel savings, making them a cost-effective choice for construction firms. These economic benefits are driving many construction companies to transition to electric equipment, viewing it as a long-term investment that can offer both financial savings and environmental advantages.
Growing Infrastructure Development and Urbanization:
Rapid urbanization and increasing infrastructure development projects globally are fueling the demand for electric construction equipment. Governments are focusing on building smart cities and sustainable infrastructure, which aligns with the use of clean and energy-efficient construction machinery. For instance, JCB has introduced electric telehandlers and loaders designed specifically for use in smart city projects, offering clean and efficient solutions for urban expansion. The growing trend of urban expansion and infrastructure development in emerging economies provides a significant growth opportunity for the Electric Construction Equipment Market. As these projects prioritize sustainability, electric machinery is becoming essential for modern construction practices.
Market Trends:
Increased Adoption of Zero-Emission Equipment:
A prominent trend in the Electric Construction Equipment Market is the growing adoption of zero-emission machinery. Construction companies are increasingly opting for electric equipment to comply with strict environmental regulations and to reduce their carbon footprint. Zero-emission equipment is particularly favored in urban areas where noise and air pollution regulations are tighter. For instance, Hitachi Construction Machinery has launched a series of battery-powered excavators that produce zero emissions, aligning with urban sustainability goals and stricter environmental policies. This shift towards electric machinery not only aligns with sustainable construction goals but also enhances the reputation of companies that prioritize environmentally friendly practices.
Technological Advancements and Automation Integration:
The integration of advanced technologies, including automation and telematics, is transforming the electric construction equipment market. Manufacturers are increasingly developing electric equipment with autonomous capabilities, enabling greater precision, efficiency, and safety on construction sites. These technologies help reduce labor costs and enhance productivity, particularly in repetitive or hazardous tasks. For instance, Bobcat introduced an autonomous electric loader with integrated telematics, allowing real-time performance monitoring and optimizing construction operations. Additionally, the use of telematics allows for real-time monitoring of equipment performance and battery life, optimizing operations and reducing downtime.
Growth in Hybrid Equipment:
While fully electric construction equipment is gaining popularity, hybrid models that combine electric motors with traditional diesel engines are also seeing increased demand. Hybrid equipment offers the benefits of reduced fuel consumption and lower emissions while retaining the reliability and power of conventional engines. For instance, Komatsu has developed hybrid excavators that combine diesel and electric power, reducing fuel consumption by up to 40% while maintaining operational reliability. This dual-power approach allows construction companies to operate in environments where charging infrastructure is limited, making hybrid models an attractive transitional solution as the industry moves toward full electrification.
Expansion of Charging Infrastructure:
As the electric construction equipment market grows, there is a corresponding rise in efforts to expand charging infrastructure. Governments and private entities are investing in the development of fast-charging stations to support the widespread use of electric equipment. For instance, ABB has been deploying fast-charging solutions for construction sites, significantly reducing downtime and supporting long-duration projects. This expansion is crucial to reducing downtime and increasing the efficiency of electric machinery on construction sites, making it more viable for long-term use in large-scale projects.
Market Challenges Analysis:
High Initial Costs and Limited Availability:
One of the significant challenges facing the Electric Construction Equipment Market is the high upfront cost associated with purchasing electric machinery. While electric equipment offers long-term savings through lower operating and maintenance costs, the initial investment is substantially higher compared to traditional diesel-powered equipment. Many construction companies, particularly small- to medium-sized enterprises, may find it difficult to justify the higher initial capital expenditure despite the potential long-term benefits. Additionally, the limited availability of certain types of electric construction machinery poses a challenge for companies seeking to transition to greener solutions. The production of electric construction equipment is still developing, with only a few manufacturers offering a full range of products. This limited availability can result in longer lead times and limited choices for businesses looking to adopt electric machinery.
Infrastructure and Battery Limitations:
The expansion of electric construction equipment is also hindered by infrastructure and battery-related limitations. One of the primary challenges is the lack of widespread charging infrastructure at construction sites, particularly in remote or underdeveloped areas. This makes it difficult for companies to rely solely on electric equipment, especially for large-scale projects that require continuous operation. Furthermore, despite advancements in battery technology, current batteries still face limitations in terms of energy storage capacity and charging times. For long-duration construction tasks, electric equipment may experience downtime due to the need for frequent recharging, which can negatively impact overall productivity. The issue is exacerbated by the fact that many construction sites do not have access to fast-charging facilities, further delaying operations. While hybrid equipment provides a temporary solution, the need for a more robust charging infrastructure and improvements in battery efficiency remains a critical challenge for the widespread adoption of electric construction equipment. Addressing these issues will be essential to unlocking the full potential of this market in the coming years.
Market Opportunities:
The Electric Construction Equipment Market presents significant opportunities as the global shift toward sustainable infrastructure and green energy continues to accelerate. Governments and regulatory bodies are increasingly promoting eco-friendly construction practices, creating a favorable environment for the growth of electric machinery. These incentives, coupled with stricter emissions regulations, offer construction companies the chance to differentiate themselves by adopting zero-emission technologies. With rising investments in renewable energy projects, smart cities, and sustainable urbanization, the demand for electric construction equipment is expected to surge. Companies that embrace this transition early can capitalize on these projects, positioning themselves as leaders in environmental responsibility while benefiting from government grants and subsidies.
Additionally, advancements in electric technology, such as enhanced battery efficiency and the development of fast-charging infrastructure, present new market opportunities. As battery performance improves and charging networks expand, the limitations associated with electric equipment, such as short operational range and long downtimes, are gradually being addressed. This creates a larger market for fully electric equipment, particularly in urban areas where charging infrastructure is more readily available. Moreover, the rise of automation and digitalization in the construction industry aligns well with electric equipment, as manufacturers integrate features like telematics and autonomous capabilities. These advancements create opportunities for electric equipment to become more competitive in terms of efficiency, precision, and overall productivity, further driving its adoption in the construction sector.
Market Segmentation Analysis:
By Vehicle
The Electric Construction Equipment Market can be segmented by vehicle type, including excavators, loaders, dump trucks, and others. Among these, electric excavators and loaders are witnessing the highest demand due to their versatility in construction projects and zero-emission benefits. Their growing adoption in urban development and infrastructure projects is driving market growth.
By Source
By source, the market is segmented into battery-powered and hybrid electric equipment. Battery-powered electric construction equipment is gaining significant traction as battery technology improves, offering longer operational hours and faster charging times. Hybrid electric equipment, combining diesel and electric power, remains popular in regions with limited charging infrastructure, providing a transitional solution.
By End Use
The end-use segment includes residential, commercial, and industrial applications. The commercial segment holds a significant share due to the rising demand for sustainable building practices in large-scale infrastructure projects. Government-backed green initiatives and urbanization trends in developing economies are further driving the adoption of electric equipment in industrial and residential sectors.
Segments:
Based on Vehicles
- Excavators
- Loaders
- Cranes
- Others
Based on Source
- Lithium-Ion
- Lead Acid
- Others
Based on End-use
- Residential
- Construction
- Industrial
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is expected to hold a significant share of the Electric Construction Equipment Market in 2024, accounting for 30% of the global market. The region’s growth is driven by stringent emissions regulations imposed by governments and environmental agencies, particularly in the United States and Canada. These regulations are pushing construction companies to adopt eco-friendly solutions, including electric equipment. Additionally, the presence of advanced infrastructure and widespread availability of charging facilities further support the market's growth in North America. Increased investments in sustainable infrastructure projects, including renewable energy and smart city initiatives, are creating further opportunities for electric construction machinery. The U.S. government’s focus on reducing carbon emissions and promoting green building practices will continue to drive market expansion in the region.
Europe
Europe is anticipated to capture 25% of the global Electric Construction Equipment Market in 2024, positioning itself as a major contributor to the market. The region's focus on sustainability, coupled with stringent environmental laws, is fueling the demand for electric construction machinery. Countries like Germany, the UK, and France are leading in the adoption of electric equipment, driven by strong government support for reducing emissions in urban areas. The European Union's Green Deal initiative, aimed at making Europe climate-neutral by 2050, is further accelerating the shift towards electric construction machinery. In addition, the region's well-developed infrastructure and increasing investments in renewable energy and transportation projects create ample growth opportunities.
Asia-Pacific
The Asia-Pacific region is projected to hold the largest market share of 35% in 2024. Rapid urbanization, infrastructure development, and industrialization in emerging economies like China, India, and Japan are key drivers of market growth. Governments in the region are increasingly investing in sustainable construction solutions to address rising environmental concerns and to meet global climate commitments. China, being one of the largest construction markets in the world, is witnessing significant adoption of electric construction equipment, supported by its aggressive push towards carbon neutrality by 2060. Additionally, ongoing smart city projects and growing demand for electric machinery in public infrastructure development across Asia-Pacific are expected to further boost the market.
Rest of the World (RoW)
The Rest of the World, including Latin America, the Middle East, and Africa, is expected to capture 10% of the Electric Construction Equipment Market in 2024. Although these regions currently represent a smaller market share, there is growing interest in sustainable construction practices, particularly in oil-rich economies like the UAE and Saudi Arabia, where governments are investing heavily in green building initiatives. Africa's infrastructure development efforts, backed by international funding, are also creating a market for electric construction equipment. As environmental regulations strengthen and demand for sustainable solutions rises, these regions hold potential for substantial growth in the coming years.
Key Player Analysis:
- Wacker Neuson
- Honda
- Hitachi Construction Machinery
- Komatsu
- Liebherr
- John Deere
- Caterpillar
- Doosan Infracore
- JCB
- Volvo Construction Equipment
- Cummins
- XCMG
Competitive Analysis:
The Electric Construction Equipment Market is highly competitive, with leading players such as Volvo Construction Equipment, Komatsu, Caterpillar, John Deere, Honda, Cummins, Wacker Neuson, XCMG, Hitachi Construction Machinery, Liebherr, JCB, and Doosan Infracore playing significant roles. These companies are focused on advancing electric technologies and expanding their portfolios to meet the rising demand for sustainable construction solutions. For instance, Volvo Construction Equipment has launched an innovative range of compact electric excavators and wheel loaders, designed to reduce emissions and meet urban construction requirements. Many of these manufacturers are heavily investing in research and development to improve battery efficiency, extend equipment life cycles, and integrate autonomous features. In addition, they are leveraging strategic partnerships and acquisitions to strengthen their market presence and scale production. Competition is further intensified by efforts to develop hybrid equipment as a transitional solution and cater to regions with limited charging infrastructure. As governments continue to enforce stringent emissions regulations, these leading players are positioning themselves to capture market share by offering innovative, environmentally friendly construction machinery.
Recent Developments:
- In 2023, Komatsu introduced the PC200LCE-11 and PC210LCE-11 Electric Excavators, their first large electric models, which promise performance comparable to diesel equivalents with zero emissions.
- In September 2023, Albemarle Corporation and Caterpillar Inc. partnered to advance sustainable mining technologies and operations, including deploying Caterpillar battery electric trucks and energy transfer solutions.
- In October 2023, Nevada Gold Mines (NGM) partnered with Komatsu Ltd. to acquire 62 Komatsu 930E-5 haul trucks between 2023 and 2025 for use at the Carlin Complex and Cortez site in Nevada.
- In 2023, Komatsu also launched the HB365LC-3 Hybrid Excavator at CONEXPO 2023, which offers improved fuel efficiency and reduced emissions by integrating a diesel engine with an electric motor and battery.
- In 2023, Albemarle Corporation and Caterpillar Inc. announced their goal of establishing a zero-emissions lithium mine in North America and driving innovation for a more sustainable mining future.
- In 2023, Komatsu made significant progress in the electric construction equipment market with notable launches, including the PC05E-1 Electric Micro Excavator, a 3-ton mini excavator offering zero emissions in Europe.
Market Concentration & Characteristics:
The Electric Construction Equipment Market is characterized by moderate to high market concentration, with a few dominant players holding a significant share of the global market. Leading companies such as Komatsu, Caterpillar, Volvo Construction Equipment, and Hitachi Construction Machinery drive innovation and set industry standards through continuous advancements in electric machinery technology. These manufacturers benefit from established brand recognition, extensive distribution networks, and strong R&D capabilities, giving them a competitive edge. However, the market is also witnessing an influx of new entrants, particularly in regions with growing demand for sustainable construction solutions. This competitive landscape encourages technological innovation, including the development of hybrid models, battery efficiency improvements, and autonomous features. As regulatory pressures increase globally, particularly regarding emissions standards, companies are compelled to invest in electric construction equipment, contributing to the market’s expansion while maintaining competition among key players. The focus remains on sustainability, cost-efficiency, and long-term profitability.
Report Coverage:
The research report offers an in-depth analysis based on Vehicle, Source, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of electric construction equipment will be driven by growing environmental awareness and stricter emission regulations globally.
- Technological advancements in battery technology, including faster charging and higher energy capacity, will improve the performance and efficiency of electric equipment.
- The rising cost of fossil fuels will encourage more construction companies to transition from diesel-powered to electric machinery for long-term cost savings.
- Urbanization and smart city projects will drive demand for electric equipment, especially in densely populated regions.
- Manufacturers will focus on developing hybrid models and fully electric machinery to cater to regions with limited charging infrastructure.
- Autonomous electric construction equipment will become more common, enhancing productivity and reducing labor costs.
- Government incentives and subsidies for green technology adoption will further accelerate market growth.
- Infrastructure development in emerging economies will create opportunities for electric machinery adoption in large-scale projects.
- Collaborations between equipment manufacturers and energy companies will focus on enhancing charging solutions for electric machinery.
- Global key players will continue to expand their portfolios to meet the rising demand for sustainable construction solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Construction Equipment Market?
What factors are driving the growth of the Electric Construction Equipment Market?
What are the key segments within the Electric Construction Equipment Market?
What are some challenges faced by the Electric Construction Equipment Market?
Who are the major players in the Electric Construction Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Electric Construction Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Electric Construction Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,169 million → 2032: USD 28,328.13 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Electric Construction Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Electric Construction Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Electric Construction Equipment Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Electric Construction Equipment Market Drivers
- 3.3 Electric Construction Equipment Market Restraints & Challenges
- 3.4 Electric Construction Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Electric Construction Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Electric Construction Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Electric Construction Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Electric Construction Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Electric Construction Equipment Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Electric Construction Equipment. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Electric Construction Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Electric Construction Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Electric Construction Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Electric Construction Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Electric Construction Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Electric Construction Equipment Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Electric Construction Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Electric Construction Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Electric Construction Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Electric Construction Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Electric Construction Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Electric Construction Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Electric Construction Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
