
Market Overview
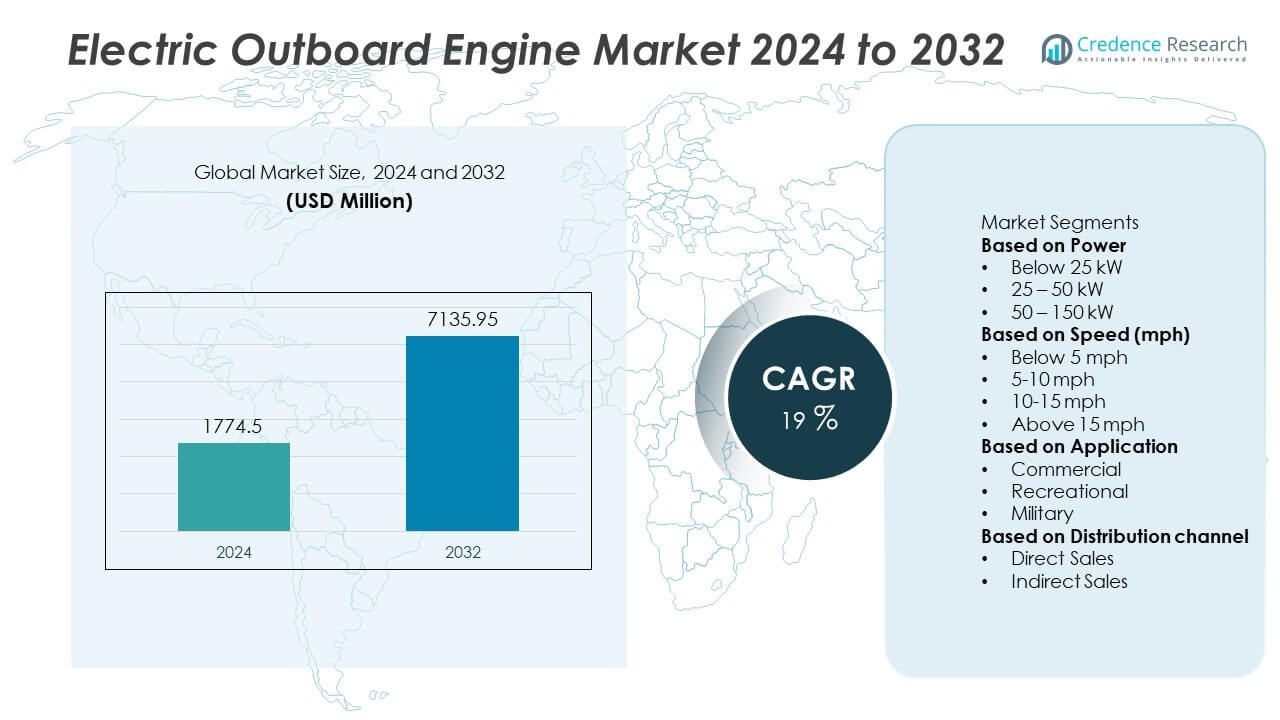
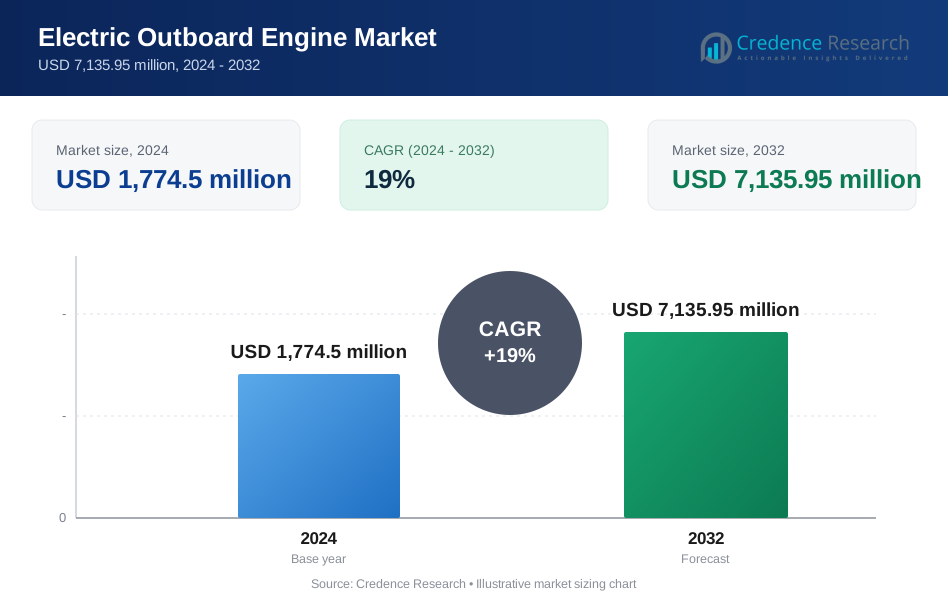
The Electric Outboard Engine Market was valued at USD 1,774.5 million in 2024 and is projected to reach USD 7,135.95 million by 2032, registering a CAGR of 19% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Outboard Engine Market Size 2024 | USD 1,774.5 Million |
| Electric Outboard Engine Market, CAGR | 19% |
| Electric Outboard Engine Market Size 2032 | USD 7,135.95 Million |
The Electric Outboard Engine market is led by key players including Torqeedo GmbH, Mitsubishi Electric Corporation, Pure Watercraft, Golden Motors, MINN KOTA, Schindler, Evoy, Parsun Power, Hitachi Ltd., and KONE. These companies dominate through advancements in battery-powered propulsion, energy efficiency, and low-noise marine technology. North America emerged as the leading region in 2024, holding a 35% share of the global market, driven by strong adoption in recreational boating and environmental compliance initiatives. Europe followed with a 30% share, supported by strict emission norms and expanding electric boating infrastructure, while Asia-Pacific accounted for 27%, boosted by growing domestic production and increasing demand for eco-friendly marine systems across coastal regions.
Market Insights
- The electric outboard engine market was valued at USD 1,774.5 million in 2024 and is projected to reach USD 7,135.95 million by 2032, growing at a CAGR of 19% during the forecast period.
- Rising demand for zero-emission marine propulsion and efficient electric systems is driving market expansion across recreational and commercial boating sectors.
- The market is witnessing trends such as the integration of lithium-ion batteries, digital control systems, and modular propulsion units to enhance performance and range.
- Leading companies like Torqeedo GmbH, Pure Watercraft, and MINN KOTA focus on innovation, strategic partnerships, and regional expansion to strengthen competitiveness.
- North America leads with 35% share, followed by Europe with 30% and Asia-Pacific with 27%, while the below 25 kW power segment holds 46% of total demand, driven by its widespread use in small and mid-size boats.
Market Segmentation Analysis:
By Power
The 25–50 kW segment dominated the electric outboard engine market in 2024, holding a 44% share. This range offers an ideal balance between power efficiency and performance for mid-sized boats used in both recreational and commercial applications. These engines deliver strong thrust and longer operating hours, making them suitable for fishing vessels, pontoons, and small ferries. Advancements in lithium-ion battery technology and improved motor efficiency are driving wider adoption. The below 25 kW segment follows due to its use in lightweight boats, while the 50–150 kW range caters to high-performance marine applications.
- For instance, Evoy's Breeze 120+ electric outboard system delivers a continuous output of 90+ kW (120+ hp) and a peak power of 137+ kW (185+ hp), providing propulsion for vessels up to 25 feet in length.
By Speed (mph)
The 5–10 mph segment led the market in 2024 with a 40% share, driven by its strong suitability for fishing boats, pontoons, and short-distance water transport. These engines deliver reliable cruising speeds while maintaining low noise and zero emissions, appealing to eco-conscious users. Improved torque delivery and extended battery life make them ideal for calm-water operations. The 10–15 mph range, with 32% share, is gaining momentum for performance boating and commercial ferry use. Growing demand for efficient, medium-speed propulsion systems continues to support the dominance of the 5–10 mph category.
- For instance, Torqeedo's Cruise 10.0 R outboard produces 12 kW peak power (comparable to a 20 HP combustion engine), operates on a 48V architecture with optional 5,000 Wh Power 48-5000 batteries, and includes an integrated GPS-based control for precise speed regulation and range tracking, ensuring optimal energy consumption during low-speed cruising.
By Application
The recreational segment accounted for 52% of the electric outboard engine market in 2024, driven by increasing adoption among leisure boaters, anglers, and sailing enthusiasts. Rising preference for silent, low-maintenance engines and environmental regulations on fuel-powered boats are accelerating demand. Manufacturers are introducing compact, lightweight models optimized for ease of use and portability. The commercial segment, with 36% share, is growing due to electric propulsion in water taxis and ferries. Expanding recreational boating activities and coastal tourism continue to strengthen the recreational segment’s market leadership worldwide.
Key Growth Drivers
Rising Demand for Eco-Friendly Marine Propulsion
Growing environmental awareness and strict emission regulations are driving the shift toward electric outboard engines. Consumers and commercial operators prefer these systems for their zero-emission operation, low noise, and reduced maintenance. Governments are enforcing policies to limit marine pollution, promoting electric alternatives to gasoline-powered motors. Rising coastal tourism and recreational boating activities further enhance market demand. The increasing adoption of electric propulsion aligns with global sustainability goals and supports the marine industry’s transition to cleaner, greener energy solutions.
- For instance, Pure Watercraft's Pure Outboard system delivers 25 kW continuous power using a direct-drive motor and a 66 kWh lithium-ion battery pack co-developed with General Motors. The system can achieve speeds up to 23 miles per hour with dual outboards, emits zero exhaust, and operates quietly.
Advancements in Battery and Motor Efficiency
Continuous improvements in lithium-ion batteries and brushless electric motors are enhancing performance, range, and power output. Higher energy density, fast charging, and lightweight designs enable longer operating times with reduced energy loss. Manufacturers are integrating intelligent power management and regenerative charging systems to improve efficiency. These advancements make electric outboard engines suitable for both recreational and commercial applications. As costs decline and charging technologies evolve, these innovations are propelling rapid market expansion across the marine sector.
- For instance, Torqeedo's Deep Blue 50R electric outboard features a 48.5 kW continuous (55 kW peak) motor with up to 54% overall efficiency.
Government Incentives and Regulatory Support
Supportive policies, subsidies, and environmental regulations are accelerating the adoption of electric propulsion systems in the maritime sector. Governments across Europe, North America, and Asia-Pacific are offering financial incentives for electric vessel purchases and infrastructure development. Restrictions on internal combustion engines in lakes and coastal waters are further boosting demand. Regulatory frameworks promoting carbon neutrality and sustainable water transport continue to attract both manufacturers and consumers toward electrification. This favorable policy landscape is expected to sustain long-term growth in the electric outboard engine market.
Key Trends & Opportunities
Integration of Smart and Connected Technologies
Digital connectivity and IoT integration are transforming electric outboard engine operations. Manufacturers are introducing smart control systems that monitor performance metrics such as speed, power consumption, and battery health in real time. Bluetooth and mobile app integration enable remote diagnostics and predictive maintenance, improving reliability. Smart features enhance user convenience and operational safety for both personal and commercial users. This trend toward intelligent propulsion systems presents major opportunities for companies investing in software-enabled marine technologies.
- For instance, Torqeedo's Deep Blue system integrates a CAN bus network and onboard computer that connects propulsion data directly to the Torqeedo Cloud. The system continuously monitors motor temperature, power draw, and GPS-based speed, transmitting this real-time data for remote diagnostics and fleet management.
Expansion of High-Power Electric Outboards
The introduction of high-power electric outboards, exceeding 100 kW, is reshaping marine propulsion capabilities. These systems cater to larger vessels such as ferries, patrol boats, and yachts, offering enhanced speed and performance comparable to combustion engines. Advances in motor design and water-cooling systems are enabling better thermal efficiency and power delivery. Manufacturers are targeting the premium boating segment, driven by rising consumer preference for performance and sustainability. The growing demand for high-torque, fast-charging solutions opens new opportunities in commercial and recreational marine sectors.
- For instance, Vision Marine Technologies E-Motion 180E outboard produces 135 kW (180 horsepower) of maximum power and a claimed 350 Nm torque. The propulsion system uses a standard 60 kWh lithium-ion battery pack with overnight charging capability via a 220V outlet.
Development of Hybrid and Solar-Powered Systems
Hybrid and solar-assisted propulsion systems are gaining attention as efficient alternatives for extended-range operations. Integration of solar panels and auxiliary hybrid drives allows vessels to operate longer with minimal emissions. These technologies are ideal for eco-tourism, coastal patrol, and small-scale commercial operations. Manufacturers are exploring hybrid designs that combine battery storage with renewable inputs to reduce dependency on grid charging. The rising focus on renewable-powered marine systems represents a key opportunity for sustainable innovation in the electric outboard engine market.
Key Challenges
High Initial Costs and Limited Range
Electric outboard engines currently face challenges related to high upfront costs and limited operational range compared to fuel-based systems. Expensive battery packs and electronic components contribute to higher purchase prices, restricting adoption among small-scale boat owners. Limited range and charging time also constrain long-duration use in commercial applications. While ongoing battery advancements are addressing these issues, affordability remains a barrier in emerging markets. Manufacturers are focusing on modular battery systems and scalable designs to improve accessibility and cost efficiency.
Underdeveloped Charging Infrastructure
The lack of widespread marine charging infrastructure hampers large-scale adoption of electric outboard engines. Many marinas, lakes, and coastal regions lack fast-charging or standardized charging ports, limiting usability for long-distance travel. Inconsistent power supply in remote areas further restricts operational flexibility. Although several regions are investing in marine EV charging networks, progress remains uneven. Expanding renewable-based and mobile charging solutions will be essential to overcoming infrastructure gaps and ensuring the sustained growth of electric marine propulsion systems globally.
Regional Analysis
North America
North America dominated the electric outboard engine market in 2024, holding a 34% share of the global market. The region’s growth is driven by strong adoption of sustainable marine propulsion systems and government incentives for electric boat usage. The U.S. leads demand with expanding recreational boating activities and emission reduction mandates across inland waterways. Key manufacturers are investing in high-power electric outboards suited for fishing, tourism, and commercial transport. Expanding charging infrastructure and the rising popularity of electric pontoon and leisure boats continue to strengthen North America’s position in this growing market.
Europe
Europe accounted for a 32% share of the global electric outboard engine market in 2024, supported by stringent emission standards and increasing marine electrification initiatives. Countries such as Norway, Germany, and the Netherlands are leading adopters, driven by government restrictions on combustion engines in lakes and coastal waters. The region’s strong focus on renewable energy and sustainable water transport promotes rapid electrification of recreational and commercial fleets. Investments in fast-charging ports and hybrid propulsion technologies further accelerate market growth. Europe’s early regulatory adoption continues to position it as a global leader in clean marine mobility.
Asia-Pacific
Asia-Pacific captured a 26% share of the electric outboard engine market in 2024, emerging as one of the fastest-growing regions. China, Japan, and South Korea lead production and adoption, supported by large-scale manufacturing and government incentives for low-emission marine operations. The increasing popularity of eco-friendly fishing boats and small ferries is boosting regional demand. Local companies are developing cost-effective electric propulsion systems for domestic and export markets. Rapid infrastructure development and growing coastal tourism are driving further adoption. With strong policy support and manufacturing capacity, Asia-Pacific remains a crucial hub for market expansion.
Latin America
Latin America held a 5% share of the global electric outboard engine market in 2024, driven by growing emphasis on sustainable water transportation. Brazil, Chile, and Mexico are leading markets with rising investments in eco-friendly marine tourism and public ferry electrification. Electric outboards are gaining attention for use in lakes, rivers, and protected ecosystems where noise and emissions are restricted. Limited charging infrastructure and high equipment costs currently constrain broader adoption. However, government initiatives promoting renewable energy integration and local partnerships with marine equipment manufacturers are expected to stimulate gradual regional growth.
Middle East & Africa
The Middle East and Africa accounted for a 3% share of the global electric outboard engine market in 2024, supported by rising investments in sustainable marine tourism and coastal infrastructure. The United Arab Emirates and Saudi Arabia are leading markets, adopting electric propulsion for leisure boating and marina developments. South Africa is also expanding adoption in inland and coastal waters through eco-tourism projects. Despite challenges such as high import costs and limited charging infrastructure, increasing awareness of clean marine technologies and renewable energy integration is expected to support long-term market expansion across the region.
Market Segmentations:
By Power
- Below 25 kW
- 25 – 50 kW
- 50 – 150 kW
By Speed (mph)
- Below 5 mph
- 5-10 mph
- 10-15 mph
- Above 15 mph
By Application
- Commercial
- Recreational
- Military
By Distribution channel
- Direct Sales
- Indirect Sales
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Electric Outboard Engine market features major players such as Torqeedo GmbH, Mitsubishi Electric Corporation, Pure Watercraft, Golden Motors, MINN KOTA, Schindler, Evoy, Parsun Power, Hitachi Ltd., and KONE. These companies compete through innovations in electric propulsion systems, battery efficiency, and motor performance to meet growing demand for sustainable marine transportation. Manufacturers are focusing on integrating lightweight materials, high-torque motors, and fast-charging battery systems to enhance vessel range and power output. Strategic collaborations with boat manufacturers and battery suppliers are expanding market presence and accelerating product development. Leading brands are also emphasizing digital monitoring, smart navigation, and modular power units to improve operational flexibility. As governments strengthen emission standards and promote electrification in marine sectors, competition is intensifying toward developing cost-efficient, high-performance electric outboard engines designed for both recreational and commercial applications.
Key Player Analysis
- Torqeedo GmbH
- Mitsubishi Electric Corporation
- Pure Watercraft
- Golden Motors
- MINN KOTA
- Schindler
- Evoy
- Parsun Power
- Hitachi Ltd.
- KONE
Recent Developments
- In April 2025, Torqeedo GmbH expanded its partnership with Yamaha, making its low-voltage electric outboards available in additional European regions including Scandinavia, France, and Poland.
- In 2025, Yamaha Outboards expanded its product portfolio by planning to offer select Torqeedo electric outboards through Yamaha outboard dealerships, enhancing reach of electric marine propulsion.
- In June 2024, Torqeedo sponsored Kiel Week regattas and showcased its new Travel XP electric motors on the Baltic Sea, enabling public test drives of its quiet, emission-free outboard units.
- In November 2023, Torqeedo GmbH unveiled the Travel XP (1.6 kW) version of its Travel line and introduced four modular motor + battery packages including Adventure, Essential, Range, and Power packages.
Report Coverage
The research report offers an in-depth analysis based on Power, Speed (mph), Application, Distribution channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The electric outboard engine market will grow rapidly with rising demand for eco-friendly marine transport.
- Manufacturers will focus on improving battery efficiency and extending operational range.
- Integration of digital controls and smart monitoring systems will enhance navigation and performance.
- Government incentives for zero-emission marine equipment will accelerate adoption across regions.
- Hybrid propulsion systems will gain traction in larger commercial and passenger boats.
- Advances in lightweight materials will improve engine portability and durability.
- Europe will remain a key market due to strict emission standards and electrification mandates.
- Asia-Pacific will witness the fastest growth driven by expanding recreational boating and tourism.
- Strategic collaborations between OEMs and battery suppliers will strengthen technological development.
- Continuous R&D in fast-charging and modular propulsion systems will shape the next generation of electric outboard engines.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Outboard Engine market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Outboard Engine market projected to grow between 2025 and 2032?
Which Electric Outboard Engine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Outboard Engine market?
Who are the leading companies in the Electric Outboard Engine market?
Which region commanded the largest share of the Electric Outboard Engine market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,774.5 million → 2032: USD 7,135.95 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Outboard Engine Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Outboard Engine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Outboard Engine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Outboard Engine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Outboard Engine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Outboard Engine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Outboard Engine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Outboard Engine Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,774.5 million → 2032: USD 7,135.95 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Outboard Engine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Outboard Engine Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Outboard Engine Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Outboard Engine Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

