
Market Overview
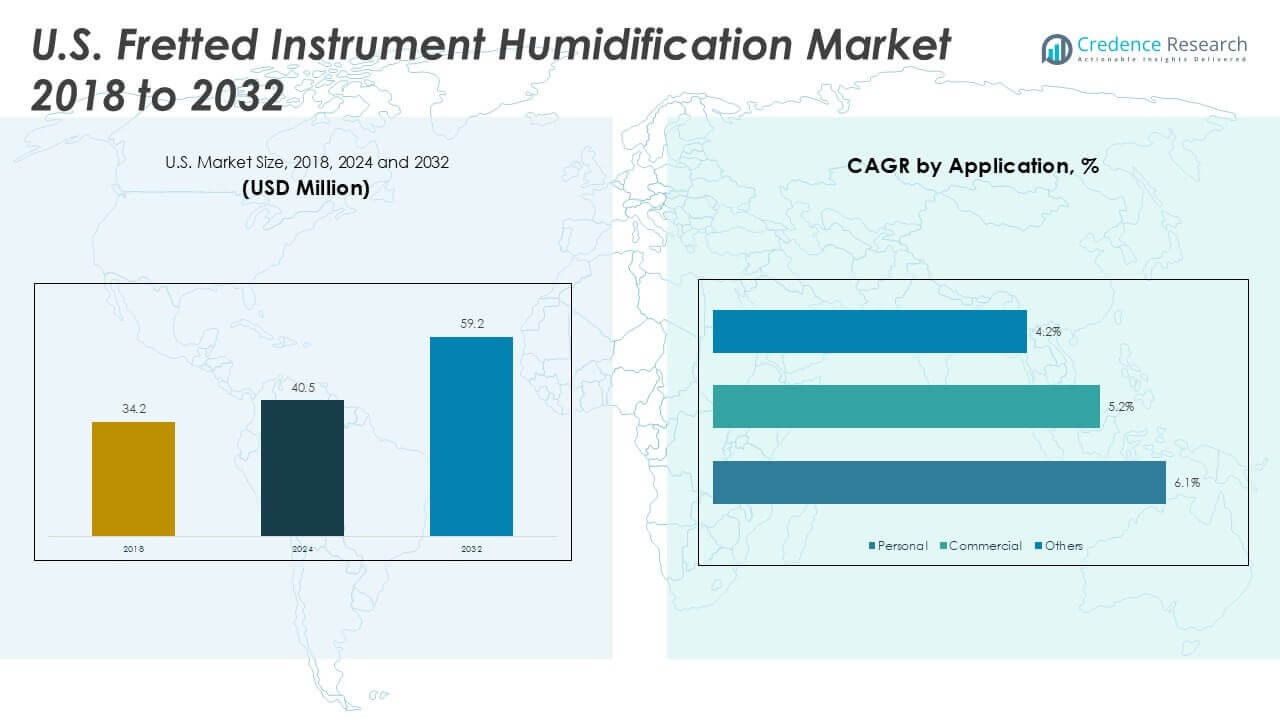
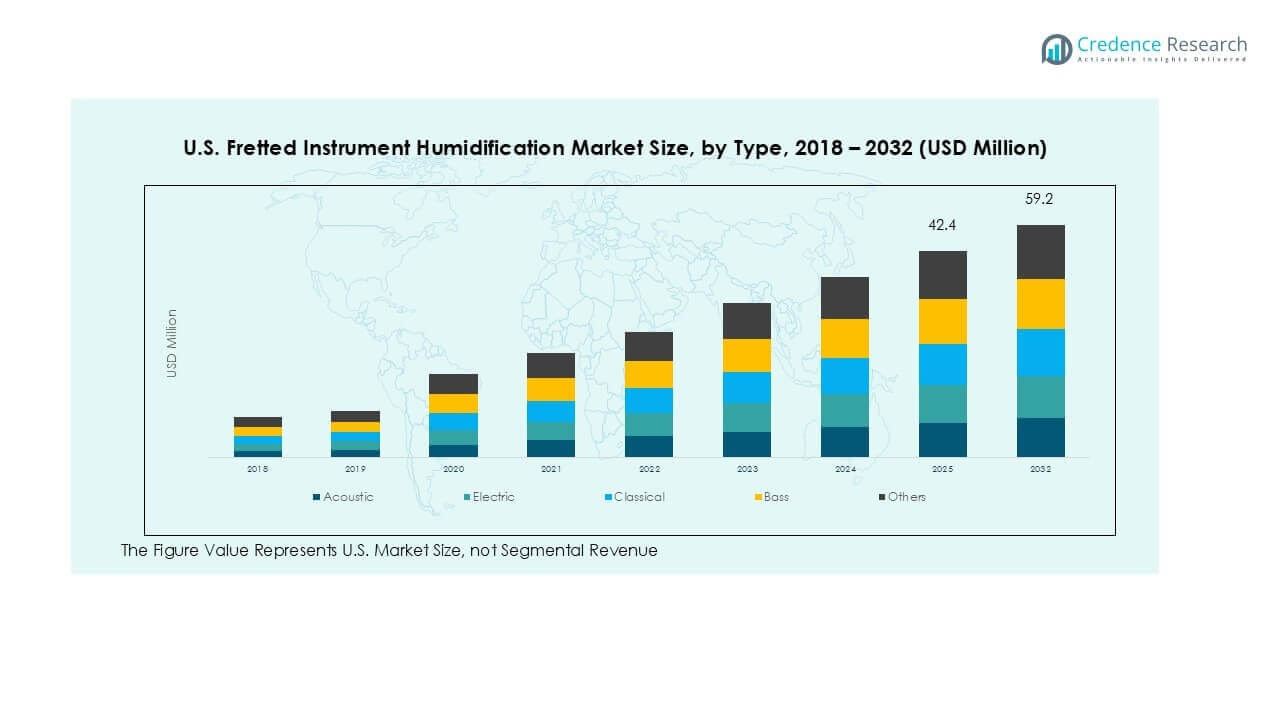
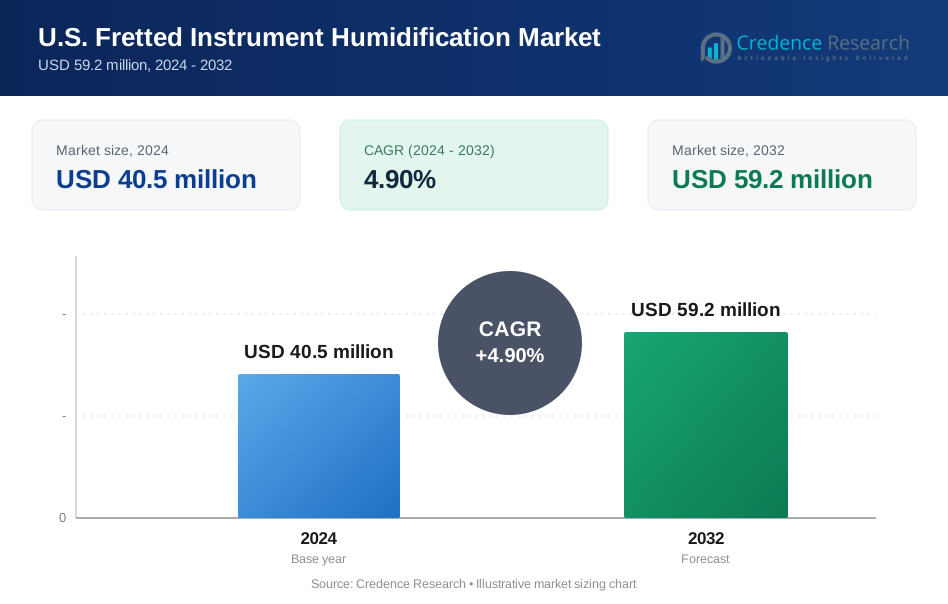
U.S. Fretted Instrument Humidification Market size was valued at USD 34.2 million in 2018, increased to USD 40.5 million in 2024, and is anticipated to reach USD 59.2 million by 2032, at a CAGR of 4.90% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| U.S. Fretted Instrument Humidification Market Size 2024 | USD 40.5 Million |
| U.S. Fretted Instrument Humidification Market, CAGR | 4.90% |
| U.S. Fretted Instrument Humidification Market Size 2032 | USD 59.2 Million |
The U.S. fretted instrument humidification market is led by key players such as Condair Group, D’Addario & Co., Humistat, Aprilaire, Boveda, and Music Nomad, who collectively account for a significant share through their diverse product offerings and nationwide distribution. These companies focus on in-case humidifiers, room-based systems, and smart monitoring solutions, targeting both professional musicians and institutional buyers. Regionally, the Northeast leads the market with nearly 30% share, driven by its cold winters and strong concentration of music schools and conservatories. The Midwest follows with about 25% share, supported by robust school music programs and community bands, while the South and West regions capture 24% and 21%, respectively, reflecting rising demand from touring musicians, retailers, and collectors seeking effective humidity control solutions.
 Market Insights
- The U.S. fretted instrument humidification market was valued at USD 40.5 million in 2024 and is projected to reach USD 59.2 million by 2032, growing at a CAGR of 4.90%.
- Growth is driven by rising sales of acoustic and classical instruments, increasing awareness of preventive maintenance, and expanding music education programs and studios that demand consistent humidity control for large instrument inventories.
- Key trends include adoption of smart, app-enabled humidifiers offering real-time humidity monitoring, subscription-based refill kits, and bundled sales with premium guitar purchases, ensuring consistent product use throughout the year.
- Leading players such as Condair Group, D’Addario & Co., Humistat, Aprilaire, Boveda, and Music Nomad compete through innovation, distribution partnerships, and direct-to-consumer strategies, with smaller brands focusing on cost-effective solutions.
- Regionally, Northeast leads with nearly 30% share, followed by Midwest at 25%, South at 24%, and West at 21%, while acoustic segment dominates by type, supported by high sensitivity to humidity fluctuations.
Market Segmentation Analysis:
By Type
Acoustic segment dominated the U.S. fretted instrument humidification market in 2024, holding the largest share driven by its extensive use among professional and hobbyist players. Acoustic guitars are more sensitive to humidity changes compared to electric instruments, requiring regular maintenance to prevent warping and cracking. Rising sales of premium acoustic guitars and the popularity of fingerstyle and unplugged music sessions have fueled demand for effective humidification solutions. Electric, classical, and bass segments follow, serving musicians seeking tone preservation, while “others” include niche instruments such as mandolins and banjos with smaller but steady adoption.
- For instance, in 2024, Martin Guitar continued its legacy of crafting acoustic instruments and released several new models for players of all levels.
By Application
Personal application led the market in 2024, supported by growing awareness among individual players about the impact of humidity on instrument longevity. Musicians increasingly invest in in-case humidifiers and room humidifiers to maintain consistent moisture levels, particularly in regions with seasonal dryness. Commercial applications, including music schools, recording studios, and retail stores, represent a growing segment as institutions adopt centralized humidity control to protect multiple instruments. The “others” category includes orchestras and touring groups, where portable humidification solutions ensure instruments remain performance-ready across varied climate conditions.
- For instance, Berklee College of Music, like other leading conservatories, has rigorous policies and climate-controlled facilities to protect the thousands of valuable stringed instruments used by its students and faculty. Maintaining a stable humidity level is a critical component of instrument preservation.
 Key Growth Drivers
Growing Demand for Acoustic Instruments
The rising popularity of acoustic guitars and classical instruments is a major driver for the U.S. fretted instrument humidification market. These instruments are highly sensitive to humidity fluctuations, which can cause cracks, fret sprout, and tonal imbalance. Increasing interest in genres such as country, folk, and indie music is boosting acoustic guitar sales, particularly among young players and professionals. This growth directly supports the demand for in-case and room humidifiers. Retailers and manufacturers are actively promoting humidification products as essential accessories, further increasing awareness and adoption across different customer groups.
- For instance, Fender Musical Instruments, a leading guitar manufacturer, continued to be a top-selling brand for acoustic guitars in 2024, maintaining strong market visibility on online marketplaces like Reverb. Humidification is an essential part of care for acoustic guitars, especially mid- and high-end solid-wood models, but manufacturers like Fender typically sell humidification kits separately as optional accessories.
Expansion of Music Schools and Studios
The growth of music education programs, conservatories, and recording studios is accelerating market expansion. These institutions often store multiple fretted instruments that require consistent humidity control to preserve sound quality and structural integrity. Centralized humidification systems and bulk in-case solutions are increasingly used in schools and studios to reduce long-term maintenance costs. Grants and private funding for music programs also encourage the purchase of new instruments, indirectly increasing the need for humidity management. This trend is particularly visible in urban centers with strong arts and culture infrastructure.
- For instance, in 2023, Yamaha concentrated on its "School Project" in emerging nations, including Malaysia and India. These initiatives focused on introducing instrumental music education into public school curricula, often by providing instruments like recorders and keyboards along with teacher training.
Rising Focus on Preventive Maintenance
Musicians are becoming more proactive about instrument care, leading to higher adoption of humidification products. Repair costs for warped necks, cracks, and damaged tonewoods can be significant, encouraging players to invest in preventive solutions. Online tutorials, social media influencers, and major guitar brands are educating users about ideal humidity levels. The availability of affordable digital hygrometers and portable humidifiers further supports this trend. Subscription-based humidifier kits and maintenance packages offered by music retailers are also boosting consistent product usage throughout the year.
Key Trends & Opportunities
Growth of Online Sales Channels
The rapid expansion of e-commerce and direct-to-consumer sales channels presents a significant opportunity for market players. Online music equipment retailers are bundling humidification kits with new instrument purchases, ensuring customers receive essential care products from the start. Subscription-based refill models are gaining popularity, allowing manufacturers to establish recurring revenue streams. Digital platforms also give brands the ability to provide educational content, such as videos and guides, directly to buyers, which increases awareness and long-term product loyalty. This channel expansion is particularly important for reaching players in rural or underserved regions where physical music stores are limited.
- For instance, Sweetwater sells humidification kits through its online platform, some of which are sold as part of bundled guitar purchases.
Integration of Smart Humidification Systems
Technology integration is a defining trend in the market, with smart humidification systems gaining significant traction. These devices feature app-based monitoring, allowing musicians to track humidity levels in real time and receive alerts when adjustments are needed. Some advanced systems offer automated moisture regulation, reducing manual intervention and ensuring optimal protection for valuable instruments. The integration of these devices with IoT-enabled home systems further appeals to tech-savvy users, providing a seamless solution for instrument care. Manufacturers are innovating with compact, sensor-driven designs that can fit inside cases or work for multiple instruments at once, addressing both convenience and precision.
Key Challenges
Limited Awareness Among Entry-Level Players
A major challenge is the lack of awareness about humidity control among entry-level players and casual buyers. Many beginners purchase budget instruments without receiving proper guidance on maintenance, which can lead to early damage and frustration. This segment often perceives humidification products as unnecessary or too costly, resulting in low adoption rates. Manufacturers must address this gap by offering affordable starter kits and collaborating with retailers to educate customers at the point of sale. Informational campaigns and value bundles can help convert first-time buyers into repeat customers while protecting instrument longevity.
Seasonality of Demand
The market faces a pronounced challenge due to seasonal demand fluctuations, with sales peaking in winter months when indoor air becomes significantly drier. This leads to uneven revenue cycles and complicates production planning for manufacturers. Smaller players with limited inventory capacity often struggle to meet peak-season demand, resulting in lost sales opportunities. Off-season demand generation through educational campaigns, bundled offers, and subscription-based services can help stabilize revenue streams. Larger manufacturers are also investing in predictive analytics and inventory optimization tools to better manage these cyclical variations and maintain consistent market presence year-round.
Regional Analysis
Northeast
Northeast held the largest share of the U.S. fretted instrument humidification market in 2024, accounting for nearly 30% of total demand. The region’s cold winters and indoor heating systems create low humidity levels, increasing the need for in-case and room humidifiers. High concentration of music schools, conservatories, and professional players in cities like New York and Boston drives adoption. Growth is supported by rising sales of premium acoustic instruments and awareness campaigns by retailers. The presence of specialized music stores offering bundled humidification solutions further strengthens regional sales and encourages regular maintenance practices among musicians.
Midwest
Midwest captured around 25% of the market share in 2024, driven by fluctuating seasonal humidity levels. The region experiences extremely dry winters and humid summers, making humidity control critical for preserving tonewoods in fretted instruments. Strong presence of community bands, school music programs, and local guitar makers drives demand for affordable humidification products. Rising participation in folk and country music events in states such as Michigan and Wisconsin also boosts adoption. Retail partnerships and online education on instrument care are encouraging more hobbyists and professionals to invest in proper humidification solutions year-round.
South
South accounted for nearly 24% of the market in 2024, supported by its large base of musicians and strong cultural association with blues, country, and gospel genres. Although the region has higher average humidity, air conditioning and changing indoor conditions make instruments prone to drying out, especially during summer. Growing disposable incomes and rising sales of acoustic and bass guitars have accelerated product demand. Music festivals and live performance venues in Texas, Tennessee, and Georgia also emphasize instrument care, prompting adoption of portable and case-based humidifiers among touring and performing artists.
West
West region represented about 21% of the U.S. market share in 2024, driven by its dry climate in states like California, Nevada, and Arizona. Low ambient humidity significantly increases the risk of cracks and warping in high-end acoustic guitars, prompting strong adoption of in-case humidifiers. Rising popularity of independent music scenes, home studios, and boutique guitar makers supports steady growth. Retailers and online platforms promote humidification kits alongside guitar purchases, raising awareness among new buyers. Adoption is further supported by environmentally controlled storage spaces offered by music schools and studios to maintain instrument quality.
Market Segmentations:
By Type
- Acoustic
- Electric
- Classical
- Bass
- Others
By Application
- Personal
- Commercial
- Others
By Geography
- Northeast
- Midwest
- South
- West
Competitive Landscape
The U.S. fretted instrument humidification market is moderately consolidated, with a mix of global players and niche specialists offering a range of solutions. Leading companies such as Condair Group, D’Addario & Co., Humistat, Aprilaire, Boveda, and Music Nomad dominate through extensive product portfolios and strong distribution networks. These players provide in-case humidifiers, room systems, smart hygrometers, and subscription-based maintenance kits targeting both individual musicians and institutions. Strategic partnerships with music retailers, online platforms, and educational institutions are helping companies expand their reach. Product innovation is a key focus, with many players introducing IoT-enabled devices offering real-time humidity monitoring and alerts. Competitive strategies include brand collaborations, direct-to-consumer sales models, and bundled offerings with premium guitar purchases. Smaller companies compete by providing affordable and portable solutions for hobbyists, while established brands focus on premium, technology-driven products to cater to professional musicians, collectors, and studios seeking reliable long-term protection.
Key Player Analysis
- Condair Group
- D’Addario & Co.
- Humistat
- Aprilaire
- Boveda
- Music Nomad
Recent Developments
- In July 2025, Condair launched the Condair RO-E reverse osmosis water purifier, designed specifically for use with humidifiers, which can be adapted for instrument humidification where precise mineral-free moisture is required. This release focuses on supporting humidity systems' hygiene, energy efficiency, and longer service cycles through improved water purity.
- In July 2024, the humidity control specialist Condair acquired Kuul, a US-based manufacturer of evaporative media, to enhance its evaporative cooling and humidification solutions.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth driven by rising acoustic and classical instrument sales.
- Adoption of smart, app-connected humidification devices will become more widespread among professionals.
- Subscription-based refill kits will gain traction, ensuring consistent maintenance and recurring revenue for manufacturers.
- Educational campaigns will increase awareness of humidity control among entry-level players and hobbyists.
- Music schools and conservatories will continue to invest in centralized humidification systems for instrument preservation.
- E-commerce platforms will expand market access, enabling bundled product sales with new instruments.
- Portable and travel-friendly humidifiers will see higher demand from touring musicians and collectors.
- Technological innovation will focus on compact, sensor-driven designs offering precise humidity monitoring.
- Regional demand will remain highest in the Northeast, with steady growth in Midwest and South.
- Competitive pressure will push companies to diversify portfolios and enhance direct-to-consumer sales strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for U.S. Fretted Instrument Humidification market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the U.S. Fretted Instrument Humidification market projected to grow between 2025 and 2032?
Which U.S. Fretted Instrument Humidification market segment held the largest share in 2024?
What are the primary factors fueling the growth of the U.S. Fretted Instrument Humidification market?
Who are the leading companies in the U.S. Fretted Instrument Humidification market?
Which region commanded the largest share of the U.S. Fretted Instrument Humidification market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 U.S. Fretted Instrument Humidification Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global U.S. Fretted Instrument Humidification Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 40.5 million → 2032: USD 59.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 U.S. Fretted Instrument Humidification Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. U.S. Fretted Instrument Humidification Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 U.S. Fretted Instrument Humidification Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 U.S. Fretted Instrument Humidification Market Drivers
- 3.3 U.S. Fretted Instrument Humidification Market Restraints & Challenges
- 3.4 U.S. Fretted Instrument Humidification Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 U.S. Fretted Instrument Humidification Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 U.S. Fretted Instrument Humidification Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, U.S. Fretted Instrument Humidification category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 U.S. Fretted Instrument Humidification Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. U.S. Fretted Instrument Humidification Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the U.S. Fretted Instrument Humidification market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 U.S. Fretted Instrument Humidification Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 U.S. Fretted Instrument Humidification Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 U.S. Fretted Instrument Humidification Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in U.S. Fretted Instrument Humidification (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New U.S. Fretted Instrument Humidification Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global U.S. Fretted Instrument Humidification Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America U.S. Fretted Instrument Humidification Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe U.S. Fretted Instrument Humidification Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific U.S. Fretted Instrument Humidification Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America U.S. Fretted Instrument Humidification Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East U.S. Fretted Instrument Humidification Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa U.S. Fretted Instrument Humidification Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. U.S. Fretted Instrument Humidification Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
