
Market Overview:
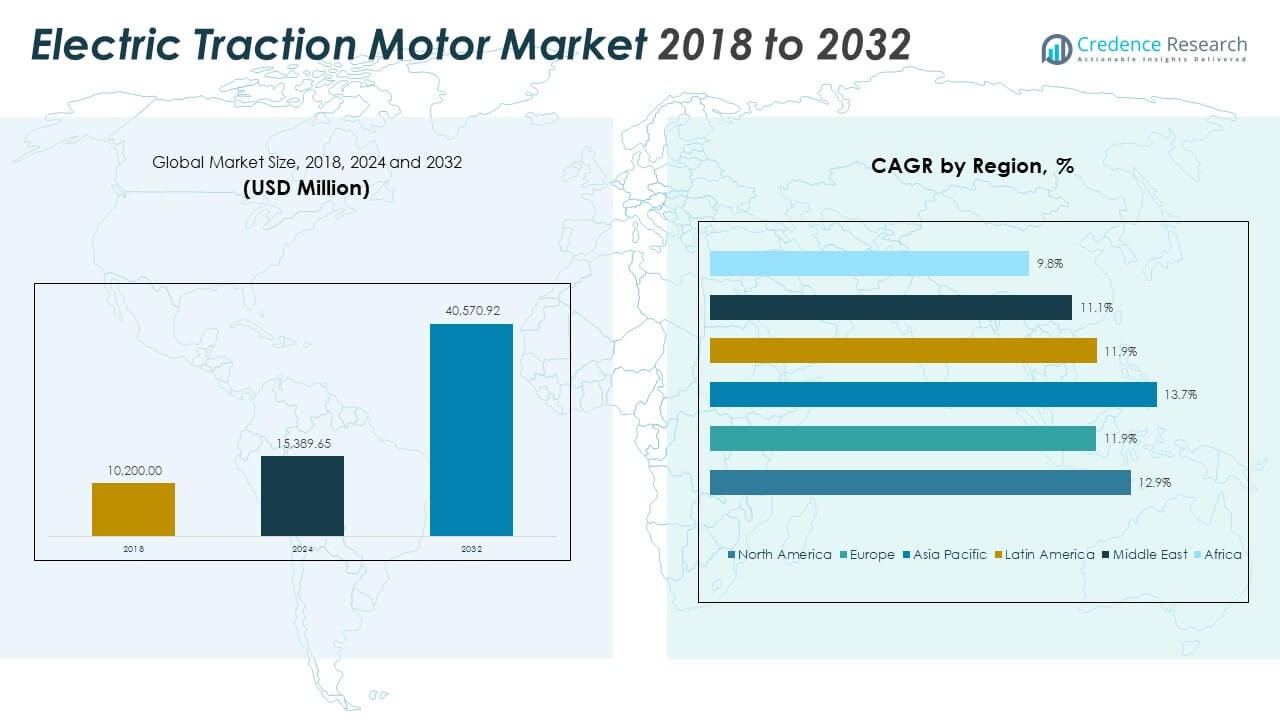
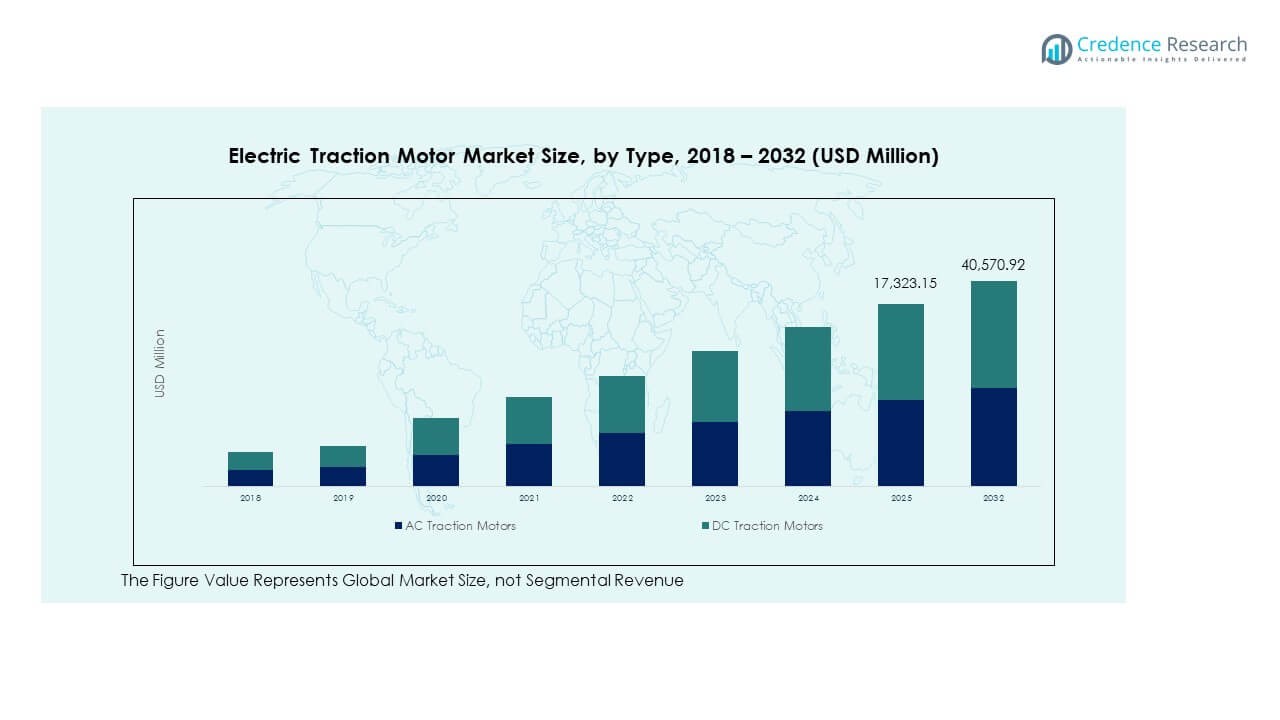
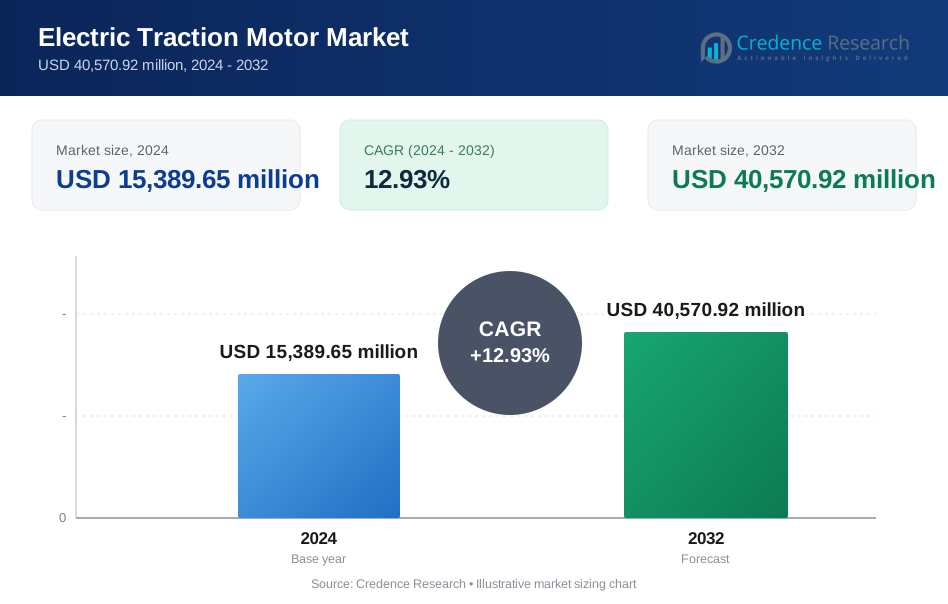
The Electric Traction Motor Market size was valued at USD 10,200.00 million in 2018 to USD 15,389.65 million in 2024 and is anticipated to reach USD 40,570.92 million by 2032, at a CAGR of 12.93% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Traction Motor Market Size 2024 | USD 15,389.65 Million |
| Electric Traction Motor Market, CAGR | 12.93% |
| Electric Traction Motor Market Size 2032 | USD 40,570.92 Million |
Rising electric vehicle production and supportive government policies accelerate industry growth. Automakers prioritize advanced traction systems to meet emission standards and enhance driving performance. Integration of digital control, regenerative braking, and efficient power conversion elevates operational reliability. Manufacturers invest heavily in R&D to develop compact, lightweight motors suited for varied platforms. Growing public transport electrification and adoption of hybrid systems further boost industry expansion. It continues to evolve as a core enabler of global electrification efforts.
Asia Pacific leads the Electric Traction Motor Market, driven by large-scale EV manufacturing and public transport electrification in China, Japan, and South Korea. Europe follows with strong regulatory frameworks promoting zero-emission mobility and railway modernization. North America demonstrates steady adoption backed by EV infrastructure development and industrial automation. Emerging regions such as Latin America, the Middle East, and Africa show growing potential through government-backed electrification and renewable integration projects. It reflects global transition toward sustainable and efficient mobility ecosystems.
Market Insights:
- The Electric Traction Motor Market was valued at USD 10,200.00 million in 2018, reached USD 15,389.65 million in 2024, and is projected to hit USD 40,570.92 million by 2032, growing at a CAGR of 12.93%.
- Asia Pacific dominates with 4% share, driven by large-scale EV production, metro network electrification, and robust manufacturing in China, Japan, and South Korea.
- North America holds 9% share, supported by strong EV adoption in the U.S. and advancements in charging infrastructure, while Europe follows with 17.7% share, led by clean transport policies and rail modernization.
- The fastest-growing region is Asia Pacific with a 7% CAGR, attributed to aggressive government incentives, cost-efficient production, and rapid industrial electrification.
- By type, AC traction motors account for around 68%, favored for efficiency and low maintenance, while DC traction motors hold 32%, mainly used in legacy rail and industrial applications.
Market Drivers
Rising Adoption of Electric and Hybrid Vehicles Across Global Markets
The Electric Traction Motor Market expands rapidly with strong growth in electric and hybrid vehicle manufacturing. Governments enforce stricter emission laws, encouraging automakers to switch to electric powertrains. Consumer demand for sustainable mobility options continues to strengthen across major economies. Companies develop motors with higher power density and energy efficiency to enhance performance. The integration of regenerative braking systems further increases vehicle range and efficiency. Automakers form strategic alliances with motor producers to ensure steady component supply. Battery cost reduction supports large-scale adoption across all segments. It remains a central enabler for next-generation mobility transformation.
- For instance, Tesla Model 3 systems recover braking energy to extend range by up to 10-20% in urban driving. Automakers form strategic alliances with motor producers to ensure steady component supply.
Advancements in Motor Design and Material Efficiency for Enhanced Performance
Ongoing technological developments focus on improving motor efficiency, torque output, and power-to-weight ratio. Engineers incorporate advanced materials such as silicon carbide and rare-earth magnets to enhance energy conversion. The Electric Traction Motor Market benefits from innovations in stator winding and rotor design. Compact architectures support lightweight vehicles and efficient cooling systems. Precision manufacturing techniques ensure reduced friction and energy loss during operation. Automotive OEMs prioritize low-noise and vibration-free performance for improved comfort. R&D investments push innovations that balance cost, durability, and environmental standards. It continues to shape engineering strategies across major motor developers.
- The Electric Traction Motor Market benefits from innovations in stator winding and rotor design, for instance, Tesla Model 3 rear motor delivers 193 kW power and 431 Nm torque at peak.
Government Incentives and Regulatory Push for Electrification Programs
Global governments implement policies promoting the shift toward cleaner transportation systems. Subsidies, tax rebates, and purchase incentives increase the affordability of electric mobility. The Electric Traction Motor Market gains from national emission-reduction plans and stricter fuel-efficiency norms. Public investment in charging networks supports long-term consumer confidence. Zero-emission mandates accelerate automaker compliance and production goals. Nations like China, Germany, and the U.S. invest in electrified public transport systems. These programs stimulate component suppliers and OEMs to scale production efficiently. It aligns industrial priorities with global sustainability goals.
Rising Demand for Efficient Public Transportation and Industrial Mobility
Urbanization and population density drive expansion in electric buses, trams, and locomotives. Transit authorities seek reliable traction solutions that lower lifecycle costs and maintenance needs. The Electric Traction Motor Market benefits from adoption in rail networks and mining vehicles. Energy recovery technologies improve system performance in metro and high-speed rail networks. Operators focus on cutting operating expenses through electric propulsion. Rapid electrification of logistics fleets further strengthens market penetration. Infrastructure modernization ensures consistent motor performance under heavy-duty applications. It establishes a critical role in building sustainable transport systems worldwide.
Market Trends
Integration of Digital Control Systems and Smart Monitoring Technologies
Manufacturers integrate digital sensors and AI-based diagnostics to improve operational reliability. Intelligent control units manage torque distribution and optimize current flow in real time. The Electric Traction Motor Market evolves toward connected systems that predict faults before failure. Predictive maintenance enhances efficiency and reduces downtime for electric vehicles. Firms employ cloud-linked platforms to track energy consumption and temperature profiles. Data analytics help engineers enhance performance through adaptive algorithms. Software-defined components become essential for next-generation EV architectures. It supports smarter, safer, and more efficient electric propulsion networks.
- For instance, Bosch develops AI-driven motor control and predictive maintenance systems that use real-time sensor data to enhance efficiency and minimize downtime in electric vehicles. These solutions improve reliability by enabling early fault detection and optimized energy management.
Shift Toward Rare-Earth-Free and Sustainable Motor Production Technologies
Concerns over material supply push firms to develop motors without rare-earth magnets. Research emphasizes recyclable materials and sustainable manufacturing practices. The Electric Traction Motor Market reflects this shift by promoting alternative magnetic alloys. Companies explore ferrite-based magnets that reduce dependency on critical minerals. Supply chain disruptions encourage local sourcing and innovation in magnet-free design. Environmental policies reinforce eco-friendly approaches across all production stages. Industrial collaborations target carbon-neutral manufacturing of electric drive systems. It accelerates progress toward a more resilient and green value chain.
Growing Focus on High-Voltage Systems and Compact Powertrain Integration
EV makers design platforms that support high-voltage motor architectures for superior power output. Advanced insulation and cooling methods manage increased heat during operation. The Electric Traction Motor Market embraces compact units that integrate with transmission systems. Engineers reduce wiring complexity while improving torque transfer. Innovations in inverter compatibility enhance energy distribution and acceleration response. OEMs deploy 800V systems in luxury and performance EVs for faster charging. The trend supports extended range and lighter vehicle weight. It sets new efficiency benchmarks for electric mobility platforms.
- For instance, Porsche’s Taycan uses an 800V electrical architecture that supports charging power up to 320 kW, enabling a 10–80% charge in around 18 minutes. This setup delivers faster charging performance than traditional 400V systems while improving overall energy efficiency.
Expansion of Manufacturing Hubs and Regional Supply Chain Optimization
Global automakers localize production to minimize logistics costs and ensure stable supply. Regional motor assembly facilities strengthen national EV production ecosystems. The Electric Traction Motor Market benefits from Asia-Pacific’s growing manufacturing capabilities. Europe and North America expand local partnerships to reduce import dependency. Investment in automation and digital twins enhances precision in motor fabrication. Supply diversification minimizes risks from raw material price fluctuations. Governments back infrastructure zones supporting component exports. It ensures long-term resilience and competitiveness for global suppliers.
Market Challenges Analysis
Fluctuating Raw Material Costs and Supply Chain Constraints
Unpredictable prices for copper, steel, and rare-earth materials impact production costs. Manufacturers struggle to maintain profit margins while meeting design standards. The Electric Traction Motor Market faces constraints in rare-earth magnet sourcing. Geopolitical instability further disrupts material availability and transportation networks. Delays in semiconductor supply affect motor control unit manufacturing schedules. OEMs adopt dual sourcing to manage long lead times and cost uncertainty. Suppliers invest in recycling processes to recover valuable metals from used components. It requires constant monitoring of trade policies to maintain consistent output.
Thermal Management, Design Complexity, and Efficiency Limitations
High-performance traction systems generate excessive heat during continuous operation. Inadequate thermal management reduces motor lifespan and efficiency. The Electric Traction Motor Market confronts challenges in balancing compactness with cooling efficiency. Engineers develop advanced liquid and air cooling systems for optimal durability. Overheating risks rise with increased torque density in compact designs. Manufacturers must also ensure electromagnetic compatibility with electronic systems. Research in better insulation and advanced winding materials remains ongoing. It demands constant innovation to overcome engineering and performance barriers.
Market Opportunities
Rising Electrification of Commercial Fleets and Public Transit Networks
Fleet operators adopt electric solutions to reduce fuel costs and emissions. Governments introduce mandates encouraging zero-emission logistics and passenger transport. The Electric Traction Motor Market gains traction in buses, trucks, and delivery vans. Charging infrastructure investments support large-scale fleet deployment. Collaborations between motor producers and fleet operators speed adoption. Energy storage and power electronics improvements further strengthen system reliability. Regional markets with urban air quality goals show higher fleet electrification. It opens consistent long-term contracts for component suppliers.
Technological Collaboration and Expansion into Emerging Economies
Motor manufacturers form partnerships with EV startups to expand innovation pipelines. Emerging economies invest in localized production and R&D facilities. The Electric Traction Motor Market benefits from rising industrialization and mobility reforms. Cost-efficient manufacturing in Asia, Africa, and Latin America attracts investors. International firms explore joint ventures for knowledge transfer and training programs. Adoption of Industry 4.0 practices improves productivity and precision in assembly. Nations offering clean transport incentives emerge as key destinations for expansion. It strengthens future growth prospects through inclusive technology adoption.
Market Segmentation Analysis:
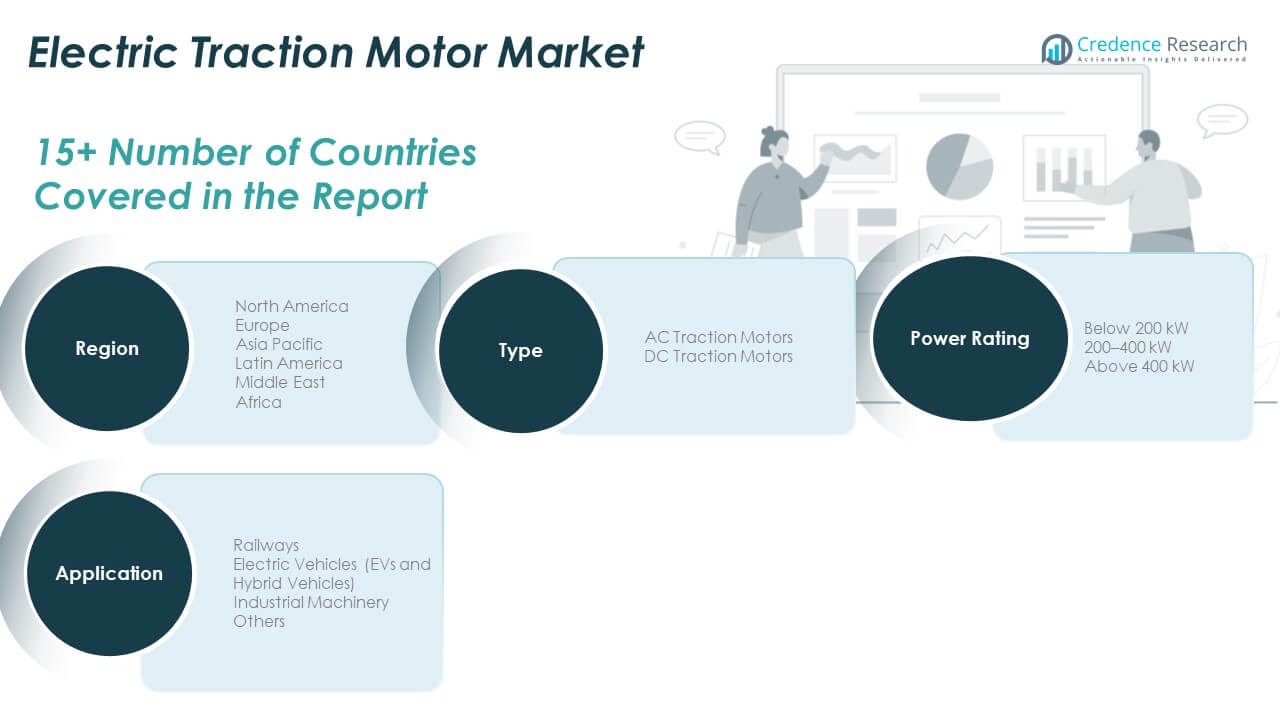
The Electric Traction Motor Market is categorized by type, application, and power rating,
By type, reflecting diverse industrial and transportation needs. AC traction motors dominate due to higher efficiency, lower maintenance, and compatibility with modern control systems. DC traction motors maintain relevance in legacy rail systems and heavy-duty vehicles requiring constant torque. Continuous innovation in inverter technology enhances AC motor performance and reliability across mobility platforms. It continues to support evolving transport systems that demand higher energy efficiency and durability in long-duty operations.
- For instance, Siemens MoComp traction motors deliver rated power from 50 to 190 kW at speeds of 1,580 to 2,500 rpm, with maximal operating speeds up to 5,250 rpm and rated torque of 210 to 730 Nm, supporting high-speed rail applications.
By application, electric vehicles lead with growing adoption across passenger and commercial fleets. Railways remain a critical segment, using traction systems for metro, tram, and high-speed networks. Industrial machinery applications expand in automation and material handling sectors requiring precise torque control. The “Others” category covers mining trucks, construction vehicles, and marine transport where electrification improves cost and emission efficiency. It strengthens its role in decarbonizing both passenger and industrial mobility systems.
By power rating, motors below 200 kW dominate smaller electric cars and light-duty equipment. The 200–400 kW segment supports medium and heavy commercial vehicles demanding high torque output. Above 400 kW motors gain traction in rail and large transport applications requiring sustained load performance. Manufacturers refine thermal management and design compact layouts to handle higher power density effectively. It aligns with the industry’s focus on balancing energy output, efficiency, and lifecycle sustainability across electric mobility infrastructure.
- For instance, Siemens SIMOTICS GP/SD/XP/DP motors are certified to IE3 premium efficiency standards, delivering up to 95% efficiency in higher power ranges around 37 kW and above. These motors cover frame sizes from 63 to 355 and power outputs up to 500 kW, ensuring reliable and energy-efficient performance across industrial applications.
Segmentation:
By Type
- AC Traction Motors
- DC Traction Motors
By Application
- Railways
- Electric Vehicles (EVs and Hybrid Vehicles)
- Industrial Machinery
- Others
By Power Rating
- Below 200 kW
- 200–400 kW
- Above 400 kW
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Electric Traction Motor Market size was valued at USD 2,590.80 million in 2018 to USD 3,841.16 million in 2024 and is anticipated to reach USD 10,106.29 million by 2032, at a CAGR of 12.9% during the forecast period. North America holds nearly 24.9% of the global market share driven by strong electric vehicle adoption and technological advancements. The U.S. leads with robust investments in EV production and charging infrastructure. Canada expands electrified transit systems to meet emission-reduction goals, while Mexico develops new assembly facilities for EV components. Manufacturers introduce high-performance traction motors for light-duty and commercial vehicles. Partnerships between automakers and motor suppliers accelerate production capacity. It strengthens its position as a hub for innovation and sustainable transport solutions.
Europe
The Europe Electric Traction Motor Market size was valued at USD 2,052.24 million in 2018 to USD 2,939.00 million in 2024 and is anticipated to reach USD 7,179.13 million by 2032, at a CAGR of 11.9% during the forecast period. Europe accounts for nearly 17.7% of the global market share, driven by strict emission norms and advanced automotive technologies. Germany, France, and the UK dominate with leading EV production and rail electrification projects. EU policies promoting carbon neutrality push manufacturers toward efficient traction solutions. High-speed rail networks in France and Spain integrate energy-efficient drive systems. European firms emphasize rare-earth-free and recyclable materials to reduce environmental impact. Governments continue expanding incentives for EV adoption. It reinforces leadership in sustainable industrial electrification.
Asia Pacific
The Asia Pacific Electric Traction Motor Market size was valued at USD 4,439.04 million in 2018 to USD 6,864.49 million in 2024 and is anticipated to reach USD 19,169.79 million by 2032, at a CAGR of 13.7% during the forecast period. Asia Pacific commands about 47.4% of the global market share, supported by rapid EV expansion and large-scale infrastructure projects. China leads global traction motor manufacturing and deployment across automotive and rail sectors. Japan and South Korea invest in high-efficiency motor technologies for hybrid and fuel-cell vehicles. India expands metro and electric bus projects under urban modernization programs. Regional suppliers scale up localized production to reduce import dependence. High demand for cost-effective, high-performance motors drives continuous innovation. It remains the fastest-growing regional contributor to global traction motor demand.
Latin America
The Latin America Electric Traction Motor Market size was valued at USD 632.40 million in 2018 to USD 944.77 million in 2024 and is anticipated to reach USD 2,307.27 million by 2032, at a CAGR of 11.9% during the forecast period. Latin America captures around 5.7% of the global share, with growth led by Brazil and Mexico. Government initiatives to promote EV adoption and improve railway systems strengthen market development. Manufacturers target urban mobility and industrial automation sectors for traction deployment. Regional investments in renewable energy enhance the sustainability of electric drives. Electric buses gain popularity in cities like São Paulo and Santiago. Production alliances with international firms boost local manufacturing capacity. It continues to evolve as an emerging hub for electric mobility in the Western Hemisphere.
Middle East
The Middle East Electric Traction Motor Market size was valued at USD 316.20 million in 2018 to USD 440.04 million in 2024 and is anticipated to reach USD 1,018.55 million by 2032, at a CAGR of 11.1% during the forecast period. The region holds roughly 2.5% of the global market share, driven by diversification efforts beyond oil-based industries. UAE and Saudi Arabia lead with smart mobility programs integrating electric public transport systems. Infrastructure projects incorporate energy-efficient rail and metro expansions. Partnerships with European and Asian suppliers improve traction motor technology transfer. Manufacturers focus on adapting systems to harsh climatic conditions. Rising renewable power generation supports grid-connected transport initiatives. It builds regional momentum toward clean transport infrastructure.
Africa
The Africa Electric Traction Motor Market size was valued at USD 169.32 million in 2018 to USD 360.18 million in 2024 and is anticipated to reach USD 789.89 million by 2032, at a CAGR of 9.8% during the forecast period. Africa contributes nearly 1.8% of the global market share, with South Africa dominating regional adoption. Electrification of mining and industrial vehicles drives early traction motor integration. Nations like Egypt and Kenya invest in urban rail systems and e-mobility programs. Limited infrastructure slows adoption, yet local assembly projects begin to emerge. Partnerships with global players promote technology transfer and workforce development. Rising demand for sustainable industrial solutions enhances market potential. It demonstrates gradual but steady progress toward modernized electric transportation ecosystems.
Key Player Analysis:
- ABB Ltd.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- General Electric (GE)
- Siemens AG
- CG Power and Industrial Solutions Ltd.
- CRRC Corporation Limited
- Robert Bosch GmbH
- NIDEC Corporation
- WEG S.A.
Competitive Analysis:
The Electric Traction Motor Market features strong competition among global and regional manufacturers focused on innovation, efficiency, and scalability. Leading players such as ABB, Siemens, Mitsubishi Electric, Toshiba, General Electric, and Nidec invest heavily in R&D to improve torque density, energy conversion, and reliability. Companies expand portfolios with high-voltage and magnet-free motor designs to reduce rare-earth dependency. Strategic mergers and partnerships strengthen production networks and supply stability. Emerging firms focus on localized manufacturing and customized propulsion systems for EV and rail applications. Competitive advantage depends on technology integration, cost optimization, and after-sales service quality. It continues to evolve through digitalization, sustainability commitments, and strategic collaboration across automotive and industrial sectors.
Recent Developments:
- In June 2025, ABB Ltd introduced the AMXE Marine Motor, a next-generation electric propulsion system designed to advance energy-efficient mobility and strengthen its traction motor portfolio across marine and heavy transport applications.
- In December 2024, ABB Ltd signed an agreement to acquire the power conversion business of Gamesa Electric from Siemens Gamesa in Spain, enhancing its expertise in high-power renewable and industrial electrification technologies supporting the electric traction motor market
Report Coverage:
The research report offers an in-depth analysis based on type, application, and power rating, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing electrification across transportation sectors will drive widespread adoption of high-performance traction motors.
- Continuous R&D investment will enhance motor efficiency, torque density, and lightweight design.
- Integration of AI-based diagnostics and smart control systems will improve operational reliability.
- Manufacturers will focus on magnet-free and rare-earth-alternative materials to ensure supply security.
- Regional production hubs in Asia Pacific and Europe will expand to support large-scale EV manufacturing.
- Public and private investments in EV charging and rail electrification will sustain long-term demand.
- Hybrid and hydrogen-powered vehicles will create new opportunities for advanced traction motor designs.
- Thermal management and compact motor integration will remain key design priorities for OEMs.
- Strategic collaborations among automakers, component suppliers, and energy firms will shape market consolidation.
- Sustainability goals will push the Electric Traction Motor Market toward recyclable, energy-efficient manufacturing standards.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Electric and Hybrid Vehicles
Stringent emission regulations and growing consumer demand for sustainable mobility are pushing automakers to adopt electric powertrains, driving demand for advanced traction motors. Strategic alliances between automakers and motor producers ensure steady supply and innovation in motor technology.
Government Incentives and Electrification Policies
Global governments are implementing subsidies, tax rebates, and zero-emission mandates, making electric vehicles and electrified public transport more affordable and attractive. These policies accelerate the adoption of electric traction motors across automotive and transit sectors.
Advancements in Motor Design and Material Efficiency
Continuous R&D investment is leading to more efficient, compact, and lightweight traction motors with higher power density and improved energy conversion. The use of advanced materials and innovative cooling and winding designs enhances performance and reliability.
Expansion of Public Transport and Industrial Electrification
Urbanization and the need for efficient, low-emission public transport are driving the electrification of buses, trams, and railways, increasing demand for traction motors. Industrial sectors are also adopting electric mobility solutions for cost and emission efficiency.
Integration of Digital Control and Smart Monitoring
The adoption of digital sensors, AI-based diagnostics, and predictive maintenance systems is improving operational reliability and efficiency of traction motors. These technologies enable real-time monitoring, fault prediction, and optimized energy management, supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electric Traction Motor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electric Traction Motor Market projected to grow between 2024 and 2032?
Which Electric Traction Motor Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electric Traction Motor Market?
Who are the leading companies in the Electric Traction Motor Market?
Which region commanded the largest share of the Electric Traction Motor Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 AC Traction Motors
- 1.2.2 DC Traction Motors
- 1.3 By Application
- 1.3.1 Railways
- 1.3.2 Electric Vehicles (EVs and Hybrid Vehicles)
- 1.3.3 Industrial Machinery
- 1.3.4 Others
- 1.4 By Power Rating
- 1.4.1 Below 200 kW
- 1.4.2 200–400 kW
- 1.4.3 Above 400 kW
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,389.65 million → 2032: USD 40,570.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Traction Motor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Traction Motor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Traction Motor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Traction Motor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Traction Motor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Traction Motor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Traction Motor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Traction Motor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,389.65 million → 2032: USD 40,570.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Traction Motor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 AC Traction Motors
- 12.3.7.2 DC Traction Motors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Railways
- 12.4.7.2 Electric Vehicles (EVs and Hybrid Vehicles)
- 12.4.7.3 Industrial Machinery
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Power Rating - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Below 200 kW
- 12.5.7.2 200–400 kW
- 12.5.7.3 Above 400 kW
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Traction Motor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electric Traction Motor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electric Traction Motor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electric Traction Motor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mitsubishi Electric Corporation
- 18.4 Toshiba Corporation
- 18.5 General Electric (GE)
- 18.6 Siemens AG
- 18.7 CG Power and Industrial Solutions Ltd.
- 18.8 CRRC Corporation Limited
- 18.9 Robert Bosch GmbH
- 18.10 NIDEC Corporation
- 18.11 WEG S.A.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

