
Market Overview
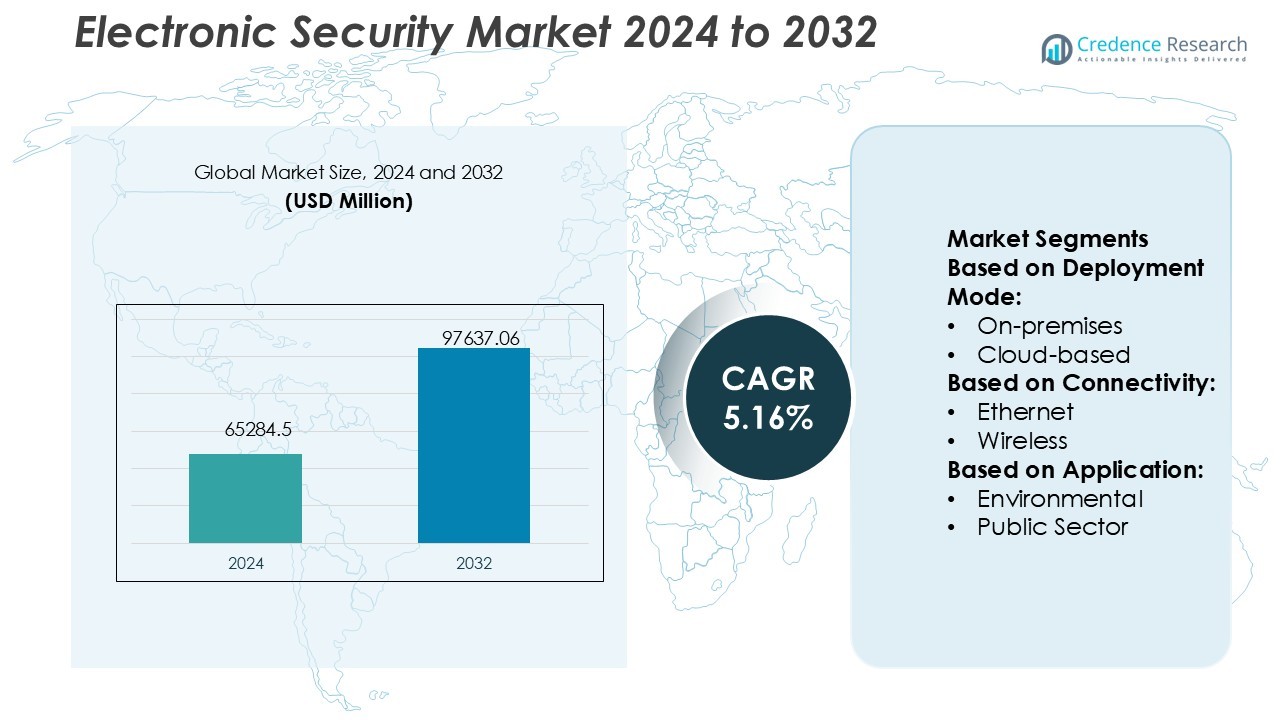
Electronic Security Market size was valued USD 65284.5 million in 2024 and is anticipated to reach USD 97637.06 million by 2032, at a CAGR of 5.16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Security Market Size 2024 | USD 65284.5 Million |
| Electronic Security Market, CAGR | 5.16% |
| Electronic Security Market Size 2032 | USD 97637.06 Million |
The Electronic Security Market is led by prominent players such as Honeywell International Inc., Johnson Controls, Bosch Security Systems, Hikvision Digital Technology Co., Ltd., Axis Communications AB, Dahua Technology Co., Ltd., Siemens AG, ASSA ABLOY AB, Schneider Electric SE, and ADT Inc. These companies dominate through continuous innovation, advanced product portfolios, and strong global distribution networks. Their focus on AI-based surveillance, cloud-enabled monitoring, and integrated access control systems enhances operational efficiency and safety across industries. North America leads the Electronic Security Market with a 35% market share in 2024, driven by robust technological adoption, regulatory compliance, and growing investments in smart infrastructure and critical facility protection across the United States and Canada.
Market Insights
- The Electronic Security Market was valued at USD 65,284.5 million in 2024 and is projected to reach USD 97,637.06 million by 2032, registering a CAGR of 5.16%.
- Market growth is driven by the increasing need for advanced surveillance, access control, and alarm systems to enhance safety across sectors.
- A key trend includes the integration of AI and cloud technologies that enable real-time monitoring, predictive analytics, and remote management of security systems.
- Leading players such as Honeywell International Inc., Johnson Controls, Bosch Security Systems, and Hikvision Digital Technology Co., Ltd. maintain dominance through innovation and strong global networks.
- North America held the largest share of 35% in 2024, supported by early technology adoption and stringent safety regulations, while the commercial segment led with high adoption in offices, data centers, and critical infrastructure.
Market Segmentation Analysis:
By Deployment Mode
The on-premises segment dominates the Electronic Security Market with a 62% share in 2024. This dominance is driven by organizations prioritizing full control over security infrastructure, data privacy, and compliance with regulatory frameworks. On-premises systems offer better customization and integration with existing IT networks, which is vital for sectors such as government, defense, and banking. Despite the growing adoption of cloud-based solutions, the high reliability and data sovereignty advantages of on-premises deployment continue to make it the preferred choice for mission-critical operations.
- For instance, Epic’s new Comet system has been trained on more than 100 billion de-identified patient medical events drawn from its Cosmos data platform to simulate patient trajectories and forecast outcomes such as length of stay or readmission.
By Connectivity
Ethernet connectivity holds the largest share of 48% in the Electronic Security Market, attributed to its high data transmission speed, stability, and scalability for large-scale surveillance and access control systems. It supports real-time video streaming and centralized monitoring, which are essential for enterprises and government institutions. Ethernet-based systems also enable integration with advanced IP-based cameras and sensors, enhancing situational awareness. The growing demand for smart infrastructure and intelligent building management further strengthens Ethernet’s dominance across commercial and industrial security installations.
- For instance, Athenahealth’s athenaOne platform was migrated to the TEFCA (Trusted Exchange Framework and Common Agreement) network at scale, covering over 160,000 provider organizations, enabling seamless data exchange across hospitals, payers, public health registries, and practices.
By Application
The public sector segment leads the Electronic Security Market with a 34% market share in 2024. This leadership is fueled by rising investments in smart city initiatives, critical infrastructure protection, and government facility security. Advanced surveillance, intrusion detection, and biometric authentication systems are increasingly deployed to enhance public safety and operational efficiency. Additionally, regulatory mandates for digital surveillance and the adoption of centralized command centers across municipalities drive continued demand for electronic security solutions in the public sector.
Key Growth Drivers
Rising Security Concerns and Crime Prevention Initiatives
The increasing incidents of theft, cyberattacks, and terrorism have heightened the need for advanced security systems. Governments and private organizations are investing heavily in surveillance, access control, and alarm systems to safeguard assets and personnel. The integration of analytics and AI-driven monitoring enhances response capabilities and reduces false alarms. This strong focus on safety and crime prevention continues to drive demand across commercial, industrial, and residential sectors globally.
- For instance, Greenway’s Electronic Case Reporting (eCR) automation can drop manual case reporting time from 10 minutes per case to zero by triggering automatic public health report transmissions.
Expansion of Smart Infrastructure and IoT Integration
Rapid urbanization and smart city projects are fueling the adoption of connected electronic security systems. IoT-enabled cameras, sensors, and alarms provide real-time data, enabling predictive threat detection and automated responses. These systems offer better scalability and remote monitoring capabilities, supporting public safety and traffic management. Governments worldwide are incorporating IoT-based security infrastructure to enhance situational awareness and urban resilience, driving significant growth for electronic security solutions.
- For instance, McKesson Medical-Surgical offers over 285,000 national brand medical and surgical products, as well as its own private-label products, through its distribution network, enabling providers to source supplies at scale and variety.
Stringent Government Regulations and Compliance Requirements
Regulatory mandates for security compliance across critical infrastructure, transportation, and data centers are boosting market growth. Governments in developed and developing regions enforce surveillance, data protection, and access control standards to safeguard sensitive areas. This regulatory pressure encourages organizations to adopt certified, advanced security technologies. The increasing focus on digital governance and public safety programs further supports widespread deployment of electronic security systems in both public and private sectors.
Key Trends & Opportunities
Artificial Intelligence and Machine Learning in Security Analytics
AI and machine learning are transforming electronic security by enabling intelligent video analytics and automated threat recognition. Smart surveillance systems can identify unusual patterns, track movements, and issue real-time alerts with higher accuracy. These technologies reduce human intervention and improve incident management efficiency. The growing use of AI-powered platforms in video monitoring, biometric verification, and intrusion detection creates significant opportunities for innovation and cost-effective security operations.
- For instance, CareCloud recently established a Healthcare AI Center of Excellence to build proprietary models in areas such as anomaly detection, clinical insight, and automation. The center launched with an initial team of over 50 AI professionals and is projected to scale to 500 AI professionals by the end of 2025.
Growing Adoption of Cloud-Based and Wireless Security Systems
Cloud-based and wireless systems are gaining traction due to their flexibility, cost efficiency, and ease of remote access. These systems eliminate the need for complex cabling and enable centralized control across multiple sites. Cloud integration also facilitates real-time analytics and data storage for large organizations. As enterprises transition toward digital transformation, the demand for scalable, cloud-enabled security platforms continues to rise, offering new growth opportunities for manufacturers and service providers.
- For instance, the MEDITECH Expanse 2.2 version supports the US Core FHIR R4 API for patient health data exchange, enabling interoperable data flows across systems over web/cloud protocols.
Key Challenges
High Implementation and Maintenance Costs
The high upfront investment required for advanced electronic security systems remains a major barrier for small and medium enterprises. Installation, integration, and continuous maintenance of surveillance networks, sensors, and access systems increase total ownership costs. Furthermore, upgrading to AI- and IoT-enabled solutions adds to financial strain. These expenses often delay adoption in cost-sensitive markets, limiting the overall growth potential despite rising security needs.
Cybersecurity and Data Privacy Risks
As electronic security systems become increasingly connected, they face heightened risks of hacking, data breaches, and unauthorized access. Compromised security networks can expose sensitive surveillance footage and personal data. Organizations must implement strong encryption, network security protocols, and regular vulnerability assessments. However, ensuring end-to-end cybersecurity across large, interconnected systems poses challenges, especially for sectors managing critical national infrastructure and confidential information.
Regional Analysis
North America
North America dominates the Electronic Security Market with a 35% share in 2024, supported by strong technological adoption and high security awareness. The United States leads the region due to extensive deployment of surveillance, access control, and cybersecurity systems across commercial and government sectors. Growing investments in smart city projects and critical infrastructure protection further boost demand. Canada also contributes significantly, driven by stringent building safety regulations and smart building integration. The presence of leading companies such as Honeywell, Johnson Controls, and Cisco strengthens North America’s position as a global innovation hub for electronic security.
Europe
Europe holds a 28% share of the Electronic Security Market, driven by strict data privacy laws and regulatory frameworks such as GDPR. Countries like Germany, the U.K., and France emphasize security modernization in industrial facilities and transportation hubs. The European Union’s focus on public safety and sustainable urban development encourages the adoption of intelligent surveillance and biometric systems. Rising terrorism threats and increased government spending on defense infrastructure continue to stimulate demand. Technological partnerships and R&D initiatives within the region further enhance Europe’s competitiveness in smart and energy-efficient security solutions.
Asia Pacific
Asia Pacific accounts for a 25% market share, emerging as the fastest-growing region in the Electronic Security Market. Strong economic expansion, rapid urbanization, and government-led smart city programs in China, India, Japan, and South Korea are key drivers. The rising need for perimeter security and intelligent monitoring in residential and commercial spaces accelerates adoption. Local manufacturers and tech startups are integrating AI and IoT into affordable solutions, expanding access to mid-tier markets. With growing investments in public infrastructure and increasing security awareness, Asia Pacific is expected to witness sustained double-digit growth through the forecast period.
Latin America
Latin America represents an 8% share of the Electronic Security Market, supported by growing investments in urban surveillance and critical infrastructure security. Brazil and Mexico are leading adopters due to rising crime rates and increased government focus on public safety initiatives. The expansion of commercial facilities and transportation systems also boosts demand for advanced access control and monitoring solutions. However, economic instability and budget constraints limit large-scale implementations in some nations. Despite these challenges, the region’s gradual digital transformation presents opportunities for cost-effective, cloud-based, and wireless security systems.
Middle East & Africa
The Middle East & Africa region holds a 4% share of the Electronic Security Market, driven by large-scale infrastructure and smart city developments. The United Arab Emirates and Saudi Arabia are key markets, investing heavily in integrated surveillance and biometric systems for airports, government buildings, and mega-projects. Africa is witnessing gradual adoption through investments in public safety and critical infrastructure modernization. Increasing geopolitical tensions and efforts to protect energy assets are fueling regional demand. As governments prioritize national security and digital transformation, the adoption of electronic security systems is expected to accelerate steadily.
Market Segmentations:
By Deployment Mode:
- On-premises
- Cloud-based
By Connectivity:
- Ethernet
- Wireless
By Application:
- Environmental
- Public Sector
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The key players in the Electronic Security Market include CureMD Healthcare, Epic Systems Corporation, Modernizing Medicine, Athenahealth, Inc., Greenway Health, LLC, AdvancedMD, Inc., McKesson Medical-Surgical Inc., eClinicalWorks, CareCloud, Inc., and Medical Information Technology, Inc. The Electronic Security Market is highly competitive, characterized by rapid technological advancements and continuous innovation. Companies focus on developing integrated surveillance, access control, and intrusion detection systems that leverage AI, IoT, and cloud computing to enhance performance and scalability. The market is driven by rising demand for intelligent monitoring, cybersecurity resilience, and energy-efficient systems across commercial, residential, and government sectors. Firms are expanding through strategic alliances, mergers, and R&D investments to strengthen product portfolios and global reach. Competitive differentiation increasingly depends on real-time data analytics, system interoperability, and cost-effective security solutions tailored to diverse end-user requirements.
Key Player Analysis
- CureMD Healthcare
- Epic Systems Corporation
- Modernizing Medicine
- Athenahealth, Inc.
- Greenway Health, LLC
- AdvancedMD, Inc.
- McKesson Medical-Surgical Inc.
- eClinicalWorks
- CareCloud, Inc.
- Medical Information Technology, Inc.
Recent Developments
- In August 2025, the Trump Administration introduced a new initiative allowing Americans to share their medical records across various tech-managed apps, despite concerns about potential data security risks.
- In July 2025, the Delhi government introduced an expanded Health Information Management System (HIMS) to facilitate online appointment booking for patients, a significant move towards digital healthcare.
- In October 2024, Oracle launched a brand-new electronic health record, its most significant health-care product update, where the latest EHR is equipped with cloud and artificial intelligence capabilities that will make it easier to navigate and set up.
- In June 2024, Docplix, a health-tech firm in New Delhi, India, secured INR 1.2 crore in a Bridge Round spearheaded by Inflection Point Ventures. The company plans to channel the funds into product development, AI integration, and broadening its market presence. This strategy includes upgrading the EHR system with cutting-edge AI features to bolster decision-making and patient care and extending innovative healthcare solutions to larger clinics and hospitals.
Report Coverage
The research report offers an in-depth analysis based on Deployment Mode, Connectivity, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by increasing demand for smart surveillance systems.
- AI and machine learning integration will enhance predictive threat detection and automated responses.
- Cloud-based security solutions will gain strong traction for remote monitoring and scalability.
- IoT-enabled devices will improve real-time data collection and networked security management.
- Governments will continue enforcing strict compliance standards for public and private security infrastructure.
- The adoption of biometric authentication will expand across corporate and residential sectors.
- Cybersecurity integration will become essential to protect connected security systems from digital threats.
- Investments in smart city and infrastructure modernization projects will boost market expansion.
- Wireless and energy-efficient systems will gain popularity for ease of installation and low maintenance.
- Partnerships and technological collaborations will drive innovation and global market penetration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Security Concerns and Crime Prevention Initiatives
Increasing incidents of theft, cyberattacks, and terrorism are prompting governments and organizations to invest in advanced surveillance, access control, and alarm systems, driving the adoption of electronic security solutions across sectors.
Expansion of Smart Infrastructure and IoT Integration
Rapid urbanization and the proliferation of smart city projects are fueling demand for connected electronic security systems, with IoT-enabled cameras and sensors enabling real-time monitoring, predictive threat detection, and automated responses.
Stringent Government Regulations and Compliance Requirements
Regulatory mandates for security compliance in critical infrastructure, transportation, and data centers are compelling organizations to adopt certified, advanced electronic security technologies to meet safety and data protection standards.
Integration of Artificial Intelligence and Machine Learning
AI and machine learning are transforming security analytics by enabling intelligent video monitoring, automated threat recognition, and predictive analytics, which improve incident response and reduce false alarms.
Growing Adoption of Cloud-Based and Wireless Security Systems
The shift toward cloud-based and wireless security platforms is driven by their scalability, cost efficiency, and ease of remote access, supporting centralized control and real-time analytics for organizations with distributed operations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electronic Security Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electronic Security Market projected to grow between 2025 and 2032?
Which Electronic Security Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electronic Security Market?
Who are the leading companies in the Electronic Security Market?
Which region commanded the largest share of the Electronic Security Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Public Sector
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.2.4 Residential
- 1.2.5 Environmental
- 1.3 By Connectivity
- 1.3.1 Ethernet
- 1.3.2 Wireless
- 1.4 By Deployment Mode
- 1.4.1 On-premises
- 1.4.2 Cloud-based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 65,284.5 million → 2032: USD 97,637.06 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Security Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Security Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Security Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Security Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Security Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Security Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Security Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Security Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 65,284.5 million → 2032: USD 97,637.06 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Security Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Public Sector
- 12.3.6.2 Commercial
- 12.3.6.3 Industrial
- 12.3.6.4 Residential
- 12.3.6.5 Environmental
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Connectivity - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Ethernet
- 12.4.6.2 Wireless
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 On-premises
- 12.5.6.2 Cloud-based
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Security End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electronic Security Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electronic Security Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electronic Security Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Honeywell International Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Johnson Controls
- 18.4 Bosch Security Systems
- 18.5 Hikvision Digital Technology Co., Ltd.
- 18.6 Axis Communications AB
- 18.7 Dahua Technology Co., Ltd.
- 18.8 Siemens AG
- 18.9 ASSA ABLOY AB
- 18.10 Schneider Electric SE
- 18.11 ADT Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

