
Market Overview
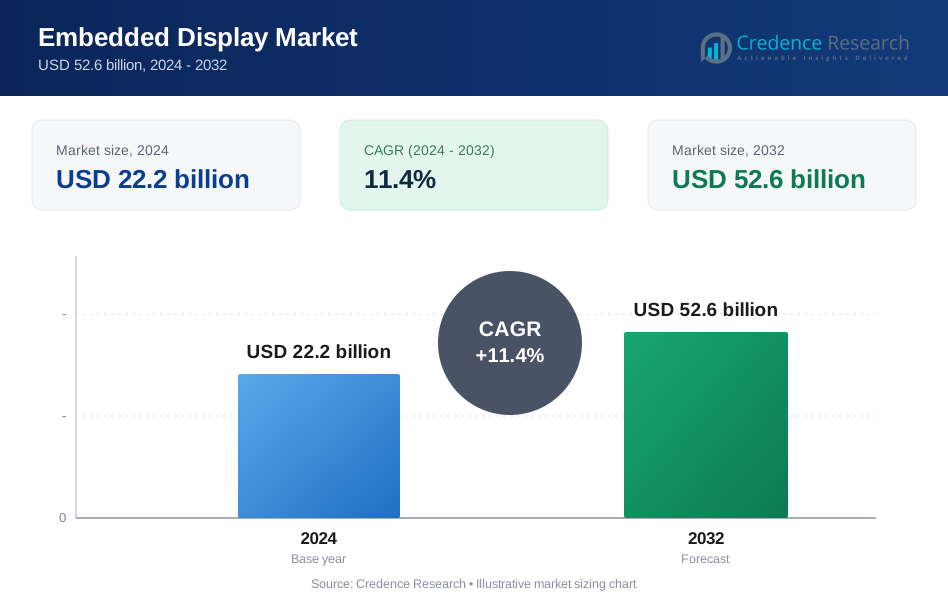
The Embedded Display Market size was valued at USD 22.2 billion in 2024 and is projected to reach USD 52.6 billion by 2032, expanding at a CAGR of 11.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Embedded Display Market Size 2024 | USD 22.2 Billion |
| Embedded Display Market, CAGR | 11.4% |
| Embedded Display Market Size 2032 | USD 52.6 Billion |
The Embedded Display Market expands steadily with rising demand across consumer electronics, automotive, healthcare, and industrial applications. Growth is driven by increasing adoption of smart devices, connected vehicles, and automation systems that require advanced display solutions.
The Embedded Display Market demonstrates strong geographical presence, with Asia-Pacific leading growth through large-scale manufacturing of consumer electronics, automotive displays, and industrial systems in China, Japan, South Korea, and India. The region benefits from rapid digitalization, strong demand for smart devices, and government-backed industrial expansion. North America shows steady demand supported by advanced healthcare, automotive, and defense applications, with the United States driving adoption of OLED and microLED technologies. Europe emphasizes sustainable innovation and regulatory compliance, with Germany, France, and the United Kingdom focusing on automotive infotainment, industrial automation, and medical equipment. Latin America and the Middle East & Africa reflect emerging opportunities through industrialization, rising healthcare adoption, and smart city investments. It benefits from both developed and developing economies driving adoption across diverse applications. Key players such as Intel Corporation, Microsoft Corporation, Avnet, Inc., and AndersDX strengthen their positions through product innovation, technology partnerships, and expansion into high-growth markets.
Market Insights
- Embedded Display Market size was valued at USD 22.2 billion in 2024 and is projected to reach USD 52.6 billion by 2032, expanding at a CAGR of 11.4%.
- Key drivers include rising adoption of smart devices, connected vehicles, and industrial automation systems demanding advanced display solutions.
- Market trends highlight strong growth in OLED and microLED technologies, touch-enabled interfaces, and integration with IoT, AI, and AR platforms.
- Competitive landscape features players such as Intel Corporation, Microsoft Corporation, Avnet, Inc., and AndersDX, focusing on innovation, ecosystem partnerships, and regional expansion.
- Restraints include high production costs, rapid technological shifts, and supply chain challenges that create barriers for smaller manufacturers.
- Asia-Pacific leads consumption with large-scale consumer electronics and automotive production, while North America emphasizes innovation in healthcare, automotive, and defense applications.
- Europe shows steady growth through regulatory-driven adoption of sustainable display technologies, while Latin America and Middle East & Africa provide emerging opportunities via industrialization, smart city projects, and rising healthcare demand.

Market Drivers
Growing Adoption Across Consumer Electronics
The Embedded Display Market grows with rising demand in smartphones, tablets, wearables, and home devices. Consumers expect high-resolution, low-power displays that deliver superior visual experiences. It drives manufacturers to integrate embedded display solutions that balance performance and efficiency. Expanding IoT ecosystems further increase reliance on compact displays for smart appliances. Rising disposable incomes in emerging economies accelerate sales of consumer electronics. This trend ensures consistent demand for embedded displays across global markets.
- For instance, Apple's iPhone 13 Pro features a 6.1-inch Super Retina XDR OLED display with ProMotion technology, a resolution of 2532 × 1170 pixels, and a pixel density of 460 ppi. The display also supports a variable refresh rate of up to 120Hz.
Expansion of Automotive Applications
The automotive sector creates strong demand in the Embedded Display Market. Modern vehicles integrate displays in infotainment systems, instrument clusters, and advanced driver-assistance systems. It supports real-time navigation, safety monitoring, and driver interaction with reduced distraction. Growth of electric and connected vehicles amplifies the need for multi-functional embedded displays. Premium models adopt OLED and TFT-LCD technologies to enhance user experience. Automakers invest in larger, intuitive display systems, driving steady adoption.
- For instance, Tesla equipped the Model S with a 17-inch embedded touchscreen display capable of 2200 × 1300 resolution, delivering over 10 teraflops of processing power for in-car gaming and infotainment in 2021, setting a benchmark for automotive display integration.
Rising Demand in Industrial and Healthcare Equipment
Industrial automation and healthcare devices represent another critical driver for the Embedded Display Market. Manufacturing plants rely on display panels in control systems, robotics, and monitoring equipment. It ensures precise data visualization and operational efficiency in complex environments. Healthcare applications such as diagnostic machines, patient monitoring, and handheld devices use embedded displays for accuracy and usability. Growth of telemedicine and connected healthcare expands integration in medical equipment. This industrial and healthcare reliance reinforces the long-term relevance of embedded display solutions.
Technological Advancements and Smart Integration
Innovation in display technologies accelerates progress in the Embedded Display Market. Advanced features such as touch capability, energy efficiency, and high brightness improve product appeal. It supports growth in outdoor, portable, and mission-critical devices. Miniaturization of components enables thinner and lighter products with improved durability. Integration with AI, AR, and IoT expands the role of displays in connected ecosystems. Continuous research and development ensure embedded displays meet evolving consumer and industrial requirements. This focus on technology strengthens competitiveness and broadens applications.
Market Trends
Shift Toward High-Resolution and Energy-Efficient Displays
The Embedded Display Market shows a strong trend toward high-resolution and energy-efficient technologies. Consumers and industries demand displays with sharper visuals, low power consumption, and longer durability. It drives the adoption of OLED, microLED, and advanced TFT-LCD technologies in portable and fixed devices. Automotive and healthcare sectors emphasize clarity and energy savings in mission-critical applications. Compact devices such as wearables and IoT-enabled tools highlight this shift toward efficient, high-quality displays. This trend ensures embedded displays remain at the core of modern device design.
- For instance, Samsung’s microLED technology, particularly a 2025 prototype wearable display, delivers a peak brightness of up to 4,000 nits. This technology is theoretically capable of maintaining a lifespan of over 100,000 hours, combining efficiency with durability for next-generation embedded and ultra-luxury applications.
Integration of Touch and Smart Interfaces
Interactive functionality continues to shape the Embedded Display Market. Touch-enabled screens and gesture-based controls gain widespread adoption in consumer electronics, industrial systems, and vehicles. It supports intuitive user experiences that enhance productivity and safety. Smart interfaces combine embedded displays with AI and IoT systems, enabling real-time analytics and advanced control. Industrial operators benefit from displays integrated into automation and robotics platforms. This focus on interactivity strengthens the role of embedded displays across both consumer and enterprise applications.
- For instance, the 85-inch Microsoft Surface Hub 2S features a multi-touch display that supports up to 20 simultaneous touch points. The pen included with the device, the Surface Hub 2 Pen, works with the display, and compatible pens like the Surface Slim Pen 2 offer 4,096 levels of pressure sensitivity, showcasing the scale of interactive and intelligent embedded display integration.
Growth of AR, VR, and Connected Ecosystems
Augmented reality and virtual reality create new opportunities in the Embedded Display Market. Displays designed for AR and VR devices require compact size, high refresh rates, and immersive visuals. It pushes manufacturers to innovate for better integration into headsets and smart glasses. Connected ecosystems such as smart homes and digital workplaces also depend on embedded displays to interface with users. Rising adoption of cloud platforms and IoT devices accelerates this trend. The synergy between immersive technologies and embedded displays supports rapid market expansion.
Miniaturization and Customization for Niche Applications
Miniaturization and product customization define another trend in the Embedded Display Market. Manufacturers design compact displays tailored for specialized uses in defense, aerospace, and medical devices. It enables high performance in environments where space and reliability are critical. Flexible form factors, ruggedized designs, and customizable interfaces enhance adoption across industries. Demand for displays in wearable devices and portable diagnostic equipment further supports this trend. Continuous advancements in materials and design ensure embedded displays adapt to diverse operational needs.
Market Challenges Analysis
High Production Costs and Supply Chain Volatility
The Embedded Display Market faces challenges due to high production costs and complex supply chain dependencies. Advanced technologies such as OLED and microLED require expensive manufacturing processes that increase product pricing. It creates barriers for smaller companies and limits affordability in cost-sensitive markets. Supply chain disruptions, including shortages of semiconductors and display panels, further complicate production schedules. Rising raw material and transportation costs also pressure profit margins. These issues affect timely delivery, impacting both consumer electronics and industrial applications worldwide.
Regulatory Compliance and Technological Complexity
Compliance with regional standards and increasing complexity of technology present ongoing challenges for the Embedded Display Market. Displays integrated into automotive, medical, and defense equipment must meet strict safety and performance regulations. It raises development costs and slows product launches for manufacturers. Rapid technological shifts in interfaces, connectivity, and energy efficiency add pressure to maintain competitiveness. Constant need for customization across industries requires heavy R&D investments. Smaller vendors struggle to keep pace with global players that dominate resources and expertise. These factors collectively restrain smooth market growth despite rising demand.
Market Opportunities
Expansion in Automotive, Healthcare, and Industrial Applications
The Embedded Display Market presents strong opportunities in automotive, healthcare, and industrial sectors. Automakers are increasingly integrating advanced display panels into infotainment systems, digital dashboards, and driver-assistance solutions. It enables safer, more interactive, and user-friendly vehicle operations. Healthcare providers adopt embedded displays in diagnostic devices, surgical equipment, and patient monitoring systems, ensuring accuracy and reliability. Industrial automation relies on displays for control systems and robotics, expanding demand in factories and logistics hubs. Growing emphasis on safety, efficiency, and convenience in these sectors reinforces long-term opportunities for embedded display adoption.
Advancement of Smart Technologies and IoT Ecosystems
Rapid digitalization and the spread of IoT ecosystems create new avenues for the Embedded Display Market. Smart homes, wearables, and connected devices depend on compact, energy-efficient displays for user interaction. It benefits from rising demand for high-resolution, touch-enabled panels in consumer electronics. Integration with AI and AR expands opportunities in immersive environments, supporting growth in education, retail, and entertainment. Rising investment in 5G and cloud connectivity further accelerates embedded display adoption across industries. These opportunities ensure embedded displays remain central to global digital transformation initiatives.
Market Segmentation Analysis:
By Type
The Embedded Display Market is segmented into fixed devices and portable devices. Fixed devices dominate demand with their integration in industrial control systems, home appliances, and automotive dashboards. It provides consistent visibility and reliability in applications requiring constant operation. Portable devices form a fast-growing category, supported by rising use in smartphones, tablets, wearables, and medical equipment. Demand for compact, lightweight, and energy-efficient displays in portable electronics continues to rise globally. This balance between fixed and portable segments ensures strong adoption across consumer and industrial domains.
By Technology
The Embedded Display Market by technology includes LED, LCD, OLED, and others. LCD technology holds a significant share due to its wide adoption in automotive and industrial devices, offering clarity and cost efficiency. It remains dominant where durability and affordability are critical. OLED is rapidly gaining traction, delivering high-resolution, energy efficiency, and flexibility for advanced consumer electronics and automotive displays. LED technology finds strong usage in medical and industrial systems where brightness and longevity are essential. Other technologies, including microLED and e-paper, emerge as niche solutions in wearables and specialized applications. This technological mix supports diverse end-use requirements across industries.
- For instance, LG Display shipped 6.4 million large OLED panels for consumer TV applications. The large OLED TV panels it produced in 2022 were available in a range of sizes, and not all supported 3840 x 2160 resolution.
By Application
The Embedded Display Market by application spans automobile displays, home appliances, medical devices, fitness devices and wearables, industrial, and automation and control systems. Automobile displays form a major segment, supported by rising integration of digital dashboards, infotainment, and driver-assistance systems. It benefits from growing demand in electric and connected vehicles. Home appliances incorporate embedded displays to enhance smart features in washing machines, refrigerators, and ovens. Medical devices rely on embedded displays for accurate diagnostics and patient monitoring. Fitness devices and wearables expand rapidly with rising health awareness and adoption of smartwatches. Industrial applications and automation systems strengthen demand for rugged, reliable displays that support operational efficiency. This wide application base highlights embedded displays as a critical component of modern technology ecosystems.
- For instance, Tesla’s Model S features a 17-inch central touchscreen with a resolution of 2200 × 1300 pixels and a dedicated 12.3-inch instrument cluster at 1920 × 1200 pixels, providing high-definition control and instrumentation
Segments:
Based on Type
- Fixed devices
- Portable devices
Based on Technology
- LED
- LCD
- OLED
- Others
Based on Application
- Automobile Displays
- Home Appliances
- Medical Devices
- Fitness Devices and Wearables
- Industrial
- Automation and Control Systems
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for a 28% share of the Embedded Display Market in 2024, supported by strong demand across consumer electronics, automotive, and healthcare sectors. The United States dominates with rapid adoption of advanced displays in connected vehicles, industrial automation systems, and medical devices. It benefits from a well-developed semiconductor industry and high investment in research and development. Canada contributes with growing healthcare infrastructure and rising adoption of smart home appliances integrated with embedded display technologies. The region also leads in early adoption of OLED and microLED innovations, reflecting strong consumer interest in premium electronics. North America’s emphasis on innovation, sustainability, and integration of smart technologies positions it as a vital contributor to global market growth.
Europe
Europe holds a 23% share of the Embedded Display Market, shaped by its strong automotive, healthcare, and industrial bases. Germany, France, and the United Kingdom are key contributors, driven by demand for automotive infotainment systems, digital dashboards, and advanced medical devices. It benefits from strict environmental and safety regulations that encourage innovation in energy-efficient and eco-friendly display technologies. Nordic countries adopt embedded displays in smart homes and industrial automation to meet sustainability goals. Eastern Europe also demonstrates growth with expanding manufacturing bases and rising demand for consumer electronics. The region’s emphasis on compliance and innovation secures its steady contribution to the global market.
Asia-Pacific
Asia-Pacific dominates with a 34% share of the Embedded Display Market, making it the largest regional consumer. China leads with large-scale manufacturing of consumer electronics, automotive displays, and industrial equipment, supported by advanced supply chains. It benefits from government initiatives promoting digitalization and smart technologies. India shows strong growth through rising adoption of smartphones, wearables, and smart appliances among its expanding middle class. Japan and South Korea contribute through innovation in OLED and microLED technologies, supplying both domestic and global markets. Southeast Asian countries including Vietnam, Indonesia, and Thailand add demand from manufacturing, automation, and consumer goods sectors. Asia-Pacific’s rapid industrialization and large population base secure its position as the market leader.
Latin America
Latin America represents a 7% share of the Embedded Display Market, with demand centered around Brazil and Mexico. Brazil leads with adoption in automotive systems, consumer appliances, and medical equipment. Mexico contributes through strong manufacturing activities and increasing adoption of digital displays in industrial and consumer devices. It benefits from rising disposable incomes and gradual growth in urbanization that drives demand for connected technologies. Countries such as Argentina, Chile, and Colombia also support regional demand through growing healthcare and industrial sectors. Limited local manufacturing remains a challenge, but global suppliers expand their presence through partnerships and regional distribution channels.
Middle East & Africa
The Middle East & Africa hold an 8% share of the Embedded Display Market, driven by rising investments in industrial, healthcare, and consumer technologies. Saudi Arabia and the United Arab Emirates dominate with smart city initiatives and adoption of embedded displays in home appliances, vehicles, and healthcare devices. It benefits from strong industrial expansion and government-backed digital transformation programs. Africa shows gradual adoption, with South Africa leading demand in healthcare equipment, industrial automation, and consumer electronics. Nigeria and Egypt also demonstrate rising adoption with growing middle-class populations. The region’s focus on modernization and diversification of economies ensures expanding opportunities for embedded display solutions.
Key Player Analysis
- AndersDX
- Multitouch Ltd.
- Avnet, Inc.
- ENEA AB
- Esterel Technologies SA
- Intel Corporation
- Altia Inc.
- Planar Systems, Inc.
- Green Hills Software Inc.
- Microsoft Corporation
Competitive Analysis
The competitive landscape of the Embedded Display Market includes AndersDX, Multitouch Ltd., Avnet, Inc., ENEA AB, Esterel Technologies SA, Intel Corporation, Altia Inc., Planar Systems, Inc., Green Hills Software Inc., and Microsoft Corporation. These companies compete by offering innovative display technologies, strong integration capabilities, and broad application coverage across consumer electronics, automotive, healthcare, and industrial sectors. It is shaped by rapid adoption of OLED, microLED, and touch-enabled solutions that meet rising demand for energy efficiency and high-resolution performance. Leading players focus on developing customizable and lightweight displays tailored for wearables, medical devices, and automotive infotainment systems. Strategic partnerships with IoT, AI, and AR technology providers enhance product integration into smart ecosystems. Global players invest heavily in R&D to improve durability, reduce power consumption, and support advanced features such as gesture control and voice interaction. Regional expansion, cloud-based solutions, and compliance with strict safety standards further strengthen competitive positioning. The Embedded Display Market remains highly dynamic, with top players balancing innovation, sustainability, and cost efficiency to secure long-term growth opportunities across diverse industries.
Recent Developments
- In June 2025, Planar Systems, Inc. announced a partnership with Megapixel to develop an ultra-fine pixel pitch LED video wall line.
- In December 2024, Planar Systems, Inc. launched the next-generation CarbonLight CLI Series of indoor LED video wall displays. The updated line features enhanced cabinet design and brightness up to 1,500 nits, plus a new 500 × 1000 mm cabinet for faster setup and teardown.
- In November 2024, Planar Systems, Inc. introduced the Simplicity P Series LCD displays, certified for 24/7 operation and available in sizes from 43 to 86 inches. The touch-enabled models support up to 20 simultaneous touch points and work with fine-tip styluses.
- In May 2024, Planar Systems, Inc. achieved a first-of-its-kind cybersecurity certification (ETSI EN 303 645) for its UltraRes W Series and Simplicity M Series 4K LCD display families.
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for embedded displays will rise with growth in smart consumer electronics.
- Automotive integration will expand with digital dashboards and advanced driver assistance systems.
- Healthcare adoption will increase with wider use in diagnostic and patient monitoring devices.
- Industrial automation will drive demand for rugged and energy-efficient display solutions.
- OLED and microLED technologies will gain traction for high-resolution and low-power applications.
- Wearables and fitness devices will strengthen adoption through compact and customizable displays.
- IoT and AI ecosystems will create new opportunities for smart and connected displays.
- Sustainability goals will push manufacturers toward eco-friendly and energy-saving technologies.
- Asia-Pacific will continue leading demand with large-scale manufacturing and rising digital adoption.
- Strategic collaborations and R&D investment will define competitive positioning in global markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Adoption Across Consumer Electronics
The proliferation of smartphones, tablets, wearables, and smart home devices is driving demand for high-resolution, energy-efficient embedded displays, as consumers expect superior visual experiences and seamless device integration.
Expansion of Automotive Applications
Modern vehicles increasingly rely on embedded displays for infotainment, digital dashboards, and advanced driver-assistance systems, with the shift toward electric and connected vehicles further amplifying the need for sophisticated display solutions.
Rising Demand in Industrial and Healthcare Equipment
Industrial automation and healthcare sectors require embedded displays for control systems, monitoring equipment, and diagnostic devices, ensuring precise data visualization and operational efficiency in mission-critical environments.
Technological Advancements and Smart Integration
Continuous innovation in display technologies, such as OLED, microLED, and touch interfaces, along with integration with IoT, AI, and AR platforms, is expanding the range of applications and enhancing the functionality of embedded displays.
Miniaturization and Customization for Niche Applications
The trend toward smaller, customizable displays is enabling adoption in specialized areas like wearables, medical devices, and aerospace, where space constraints and reliability are critical, supporting broader market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Embedded Display, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Embedded Display Market projected to grow between 2025 and 2032?
Which Embedded Display Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Embedded Display Market?
Who are the leading companies in the Embedded Display Market?
Which region commanded the largest share of the Embedded Display Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Fixed devices
- 1.2.2 Portable devices
- 1.3 By Technology
- 1.3.1 LED
- 1.3.2 LCD
- 1.3.3 OLED
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Automobile Displays
- 1.4.2 Home Appliances
- 1.4.3 Medical Devices
- 1.4.4 Fitness Devices and Wearables
- 1.4.5 Industrial
- 1.4.6 Automation and Control Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 22.2 billion → 2032: USD 52.6 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Embedded Display Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Embedded Display Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Embedded Display Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Embedded Display Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Embedded Display Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Embedded Display Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Embedded Display Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Embedded Display Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 22.2 billion → 2032: USD 52.6 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Embedded Display Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed devices
- 12.3.7.2 Portable devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 LED
- 12.4.7.2 LCD
- 12.4.7.3 OLED
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automobile Displays
- 12.5.7.2 Home Appliances
- 12.5.7.3 Medical Devices
- 12.5.7.4 Fitness Devices and Wearables
- 12.5.7.5 Industrial
- 12.5.7.6 Automation and Control Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Embedded Display End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Embedded Display Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Embedded Display Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Embedded Display Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intel Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 Avnet, Inc.
- 18.5 AndersDX
- 18.6 Planar Systems, Inc.
- 18.7 Altia Inc.
- 18.8 Green Hills Software Inc.
- 18.9 Multitouch Ltd.
- 18.10 ENEA AB
- 18.11 Esterel Technologies SA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

