
Encapsulant Materials for PV Modules Market Overview
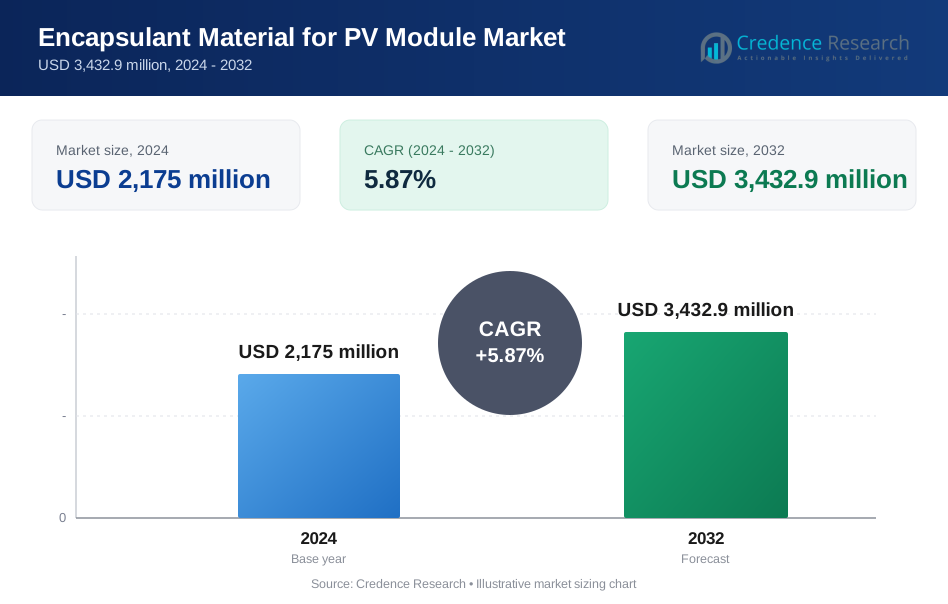
The Encapsulant Materials for PV Modules Market size was valued at USD 2,175 million in 2024 and is anticipated to reach USD 3,432.9 million by 2032, at a CAGR of 5.87% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Encapsulant Material for PV Module Market Size 2024 | USD 2,175 Million |
| Encapsulant Material for PV Module Market, CAGR | 5.87% |
| Encapsulant Material for PV Module Market Size 2032 | USD 3,432.9 Million |
Key players in the encapsulant materials for PV modules market include Dow, DuPont, Wacker Chemie, 3M, Mitsui Chemicals, and Hanwha Solutions, each holding significant influence through global supply networks and solar-specialized product lines. Dow and DuPont lead with advanced POE and EVA formulations tailored for high-efficiency modules, while Wacker Chemie and Mitsui Chemicals offer high-purity silicone and polyolefin encapsulants. 3M and Hanwha Solutions maintain strong positions in adhesive and sheet-based technologies. Asia Pacific dominates the market with a 55% share in 2024, driven by large-scale PV module manufacturing hubs in China, South Korea, and Japan. The region benefits from strong domestic demand, export capabilities, and material cost advantages, making it central to both supply and consumption dynamics.

Encapsulant Materials for PV Modules Market Insights
- The encapsulant materials for PV modules market was valued at USD 2,175 million in 2024 and is projected to reach USD 3,432.9 million by 2032, growing at a CAGR of 5.87%.
- Growth is driven by rising solar PV installations worldwide, with bifacial and high-efficiency modules boosting demand for advanced encapsulants like POE.
- A key trend is the shift toward recyclable thermoplastics and UV-stable materials, as manufacturers seek sustainable, long-life module components.
- Top players include Dow, DuPont, Wacker Chemie, and 3M, competing through innovation in optical clarity, thermal stability, and moisture resistance.
- Asia Pacific holds the highest regional share at 55%, followed by North America and Europe with 18% and 16%, respectively; EVA leads the material segment with over 65% share, while films/sheets dominate the product form segment with over 80% share; cost pressures and raw material price volatility remain key restraints.
Encapsulant Materials for PV Modules Market Segmentation Analysis:
By Material Type
Ethylene-Vinyl Acetate (EVA) leads the encapsulant materials market with over 65% share in 2024. Its dominance comes from cost-effectiveness, long-standing industry acceptance, and favorable optical transmission. EVA is widely used in crystalline silicon PV modules due to its ease of processing and established supply chain. However, Polyolefin Elastomer (POE) is gaining momentum, particularly in bifacial modules, for better moisture resistance and low PID (Potential Induced Degradation). Materials like silicone and thermoplastic polyurethane (TPU) serve niche high-durability applications, while ionomers and PVB are emerging in specialty or thin-film technologies.
- For example, DuPont's ionomer-based encapsulant material (PV5400 series) has been adopted in thin-film and BIPV applications requiring high UV resistance.
By Product Form
Films/Sheets dominate with over 80% market share, driven by standardized manufacturing processes and compatibility with automated lamination lines. These are the preferred choice in high-volume production of crystalline PV modules. Liquid encapsulants are used in flexible or custom PV panel formats, often in research or specialty building-integrated photovoltaics (BIPV). Coatings and sprays are limited to specific thin-film applications or prototyping environments, where even thickness and full-surface coverage are required. Film-based encapsulants continue to gain preference due to cost control and consistent module quality in utility-scale deployments.
- For instance, Jolywood adopted film encapsulants across all of its N-type bifacial modules, exceeding 3 GW of annual output in 2023.
By Curing/Processing Method
Peroxide cross-linked systems hold the highest share, accounting for over 60% of market volume, due to their compatibility with EVA and long-term durability in field conditions. Thermoplastic (non-crosslinked) materials, especially POE, are growing due to faster lamination cycles and recyclability. UV-curable systems remain a niche, mainly used in lightweight and flexible modules where thermal curing is unsuitable. Addition-cure silicones are reserved for premium applications needing extreme weather or UV resistance. The rise of POE and thermoplastic blends is encouraging greater adoption of alternative curing processes with shorter cycle times.
Encapsulant Materials for PV Modules Market Key Growth Drivers
Surge in Global Solar PV Installations
The rapid rise in solar PV deployment is a major driver for encapsulant materials demand. Countries are accelerating solar adoption to meet climate goals, with large-scale installations dominating new capacity additions. Encapsulant materials ensure long-term durability and optical performance of PV modules, making them essential in expanding solar infrastructure. Crystalline silicon modules, which dominate global PV shipments, rely heavily on EVA and POE encapsulants. Government incentives, falling module costs, and national energy transition plans in China, the U.S., and India are driving capacity expansion. These factors directly boost encapsulant volume demand. The utility-scale segment, in particular, generates repeat bulk orders for standardized encapsulants, strengthening demand consistency. In rooftop and residential markets, improved aesthetics and moisture resistance further influence material selection, supporting premium encapsulant types like POE and ionomers.
- For instance, India installed over 10-13 GW of new solar capacity in 2023, with over 75% using crystalline silicon modules.
Shift Toward High-Efficiency and Bifacial Modules
The industry shift toward bifacial and high-efficiency modules is pushing the need for advanced encapsulants. Bifacial modules capture sunlight from both sides, requiring higher optical clarity and low degradation encapsulants. POE is increasingly favored for its excellent electrical insulation, low water vapor transmission rate, and resistance to PID, all critical for bifacial applications. As manufacturers integrate PERC, TOPCon, and HJT technologies, demand grows for materials that can sustain harsh processing and environmental stress. These modules often use glass-glass structures, requiring encapsulants with better adhesion and longevity. Such technical needs are pushing the market beyond traditional EVA. POE’s thermal stability also allows better compatibility with high-efficiency cell designs, making it the preferred choice in next-gen modules. This trend creates consistent demand for performance-grade materials and encourages R&D investment across encapsulant suppliers.
- For instance, in 2023, Canadian Solar expanded its high-power module offerings by scaling mass production of its TOPCon and BiHiKu7 bifacial series, which increasingly utilize POE (polyolefin elastomer) or EPE encapsulants to ensure superior reliability and PID resistance.
Growing Focus on Module Longevity and Reliability
Encapsulant materials directly influence the lifespan and reliability of solar modules, making them a central focus in module design. As solar developers target 25–30 year operational life, the performance of encapsulants under heat, humidity, and UV exposure becomes critical. Degradation or delamination in encapsulants can reduce energy yield and accelerate module failure. Manufacturers are increasingly specifying encapsulants with better durability and resistance to yellowing, moisture ingress, and electrical stress. Long-term field performance is now a competitive differentiator, especially in utility-scale projects where warranty claims can be costly. As a result, players in the encapsulant market are investing in advanced testing, quality control, and proprietary formulations. This demand for durable encapsulation solutions encourages material innovation, especially in thermoplastics, silicones, and hybrid blends, supporting sustained market growth.
Encapsulant Materials for PV Modules Market Key Trends & Opportunities
Rise of Thermoplastic Encapsulants and Recyclability Goals
Sustainability pressures are driving interest in recyclable and reprocessable encapsulant solutions. Thermoplastic encapsulants, especially non-crosslinked POE and TPU, allow module disassembly and material recovery at end of life. This aligns with circular economy goals and emerging PV recycling mandates, particularly in the EU. Unlike peroxide cross-linked EVA, which requires energy-intensive recovery, thermoplastics support easier separation without compromising performance. Manufacturers are exploring closed-loop recycling systems where thermoplastics can be reused in new module production or other applications. This trend opens new product opportunities and strengthens value propositions for module brands promoting sustainability. It also reduces waste management costs and aligns with green financing expectations. As sustainability certifications become more relevant in procurement decisions, demand for thermoplastic and recyclable encapsulants is likely to grow, especially among premium and utility-scale developers.
- For instance, Borealis launched its Bornewables™ POE series in 2023 for PV encapsulants, emphasizing recyclability and non-crosslinked formulation for end-of-life recovery.
Product Differentiation Through Encapsulant Innovation
Encapsulant suppliers are leveraging material innovation to differentiate products amid rising competition. Advanced encapsulants now offer anti-UV, anti-PID, and anti-salt mist properties, tailored for different environments. Manufacturers are formulating blends that enhance optical transmission, extend life span, and improve lamination throughput. Co-extruded multilayer sheets are emerging, combining different polymers to achieve hybrid performance. Some encapsulants also integrate self-cleaning or anti-reflective properties to raise module efficiency. These innovations support module brands in targeting niche applications like agrivoltaics, floating PV, and high-humidity installations. Innovation also enables faster production cycles, reducing time and energy costs per module. As manufacturers pursue higher energy yields per square meter, demand rises for encapsulants that contribute to these goals. This trend opens space for specialty players to enter with differentiated offerings focused on performance rather than price.
Encapsulant Materials for PV Modules Market Key Challenges
Volatility in Raw Material Prices and Supply Chains
Encapsulant materials rely on polymer resins and specialty chemicals, many of which are sensitive to upstream price volatility. Supply disruptions, such as those seen during COVID-19 or geopolitical tensions, can raise costs and affect delivery timelines. EVA and POE resins are derived from petrochemicals, exposing the market to fluctuations in crude oil prices. Global logistics issues, including port congestion and container shortages, further complicate procurement for encapsulant manufacturers. These cost swings challenge margin stability and can force end-users to delay or renegotiate module orders. Smaller encapsulant players without backward integration or diversified sourcing face competitive disadvantages. This makes raw material security and supplier diversification critical priorities for encapsulant producers in sustaining operational continuity and pricing stability.
Compatibility and Standardization Across New Module Technologies
The fast pace of innovation in PV module technology creates compatibility challenges for encapsulant materials. New cell architectures such as HJT and TOPCon often require specific encapsulant formulations with high thermal and chemical stability. However, lack of universal standards leads to trial-and-error testing, delaying project timelines and increasing qualification costs. Differences in curing behavior, adhesion, and thermal expansion can cause interface issues in multilayer module stacks. Custom formulations raise production complexity and limit scalability. Encapsulant manufacturers must balance innovation with process compatibility across various lamination and curing systems. Achieving long-term field validation for new materials remains time-intensive. Without established standards or certification pathways, market entry becomes difficult for novel encapsulant solutions. This challenge restricts widespread adoption of newer, high-performance materials in mainstream PV manufacturing.
Encapsulant Materials for PV Modules Market Regional Analysis
Asia Pacific
Asia Pacific leads the encapsulant materials for PV modules market with over 55% share in 2024. China dominates regional demand due to its extensive PV module manufacturing base and domestic solar installations. Countries like India, Japan, and South Korea contribute to regional growth through government-backed solar programs and export-focused module production. The presence of key encapsulant producers and raw material suppliers ensures stable supply chains. High-volume manufacturing and cost-sensitive buyers keep EVA as the preferred material. However, POE adoption is increasing among premium module manufacturers targeting international markets with advanced bifacial and glass-glass modules.
North America
North America accounts for nearly 18% of the global market, supported by strong solar adoption in the U.S. and Canada. Utility-scale projects drive encapsulant demand, especially for durable materials that meet long-term warranty expectations. POE and thermoplastic blends are gaining share due to higher performance in extreme climates. Domestic module production, though smaller than Asia, is expanding through policy incentives like the Inflation Reduction Act. The trend toward local manufacturing is expected to reduce supply chain risks and encourage advanced encapsulant integration. Bifacial modules are widely deployed in utility projects, boosting demand for premium encapsulants.
Europe
Europe holds approximately 16% market share, driven by stringent quality standards and rising solar deployment across Germany, Spain, France, and Italy. The region prioritizes module recyclability and long-term performance, pushing demand for thermoplastics and non-EVA encapsulants. EU regulations on extended producer responsibility influence material selection in favor of recyclable and low-emission polymers. The growth in building-integrated photovoltaics (BIPV) and floating solar also supports niche encapsulant applications. European module manufacturers adopt innovative encapsulant materials that align with environmental certifications and long-term energy yield. Import reliance remains high, but local innovation is gaining traction in high-performance material segments.
Latin America
Latin America represents around 6% of the global market, with Brazil, Chile, and Mexico leading solar capacity additions. Utility-scale solar installations form the bulk of encapsulant demand, with EVA dominating due to affordability and established supply chains. Local encapsulant production remains limited, making the region dependent on imports from Asia and North America. Government renewable targets and grid expansion projects support stable demand for PV modules, indirectly driving encapsulant volume. While adoption of POE is limited, it is slowly gaining ground in projects requiring higher energy yield and long-term reliability in high-UV environments.
Middle East & Africa
The Middle East & Africa region accounts for about 5% of the market, with strong momentum in countries like the UAE, Saudi Arabia, Egypt, and South Africa. Large-scale desert-based solar projects drive encapsulant demand, requiring materials that resist high temperatures and UV exposure. EVA remains the dominant choice due to availability and cost benefits. However, POE and silicone encapsulants are gaining adoption in high-spec modules for utility-grade deployments. Regional manufacturing remains nascent, with most encapsulants sourced internationally. The growth in national solar programs and energy diversification plans supports long-term market expansion in this region.
Encapsulant Materials for PV Modules Market Segmentations:
By Material Type
- Ethylene-Vinyl Acetate (EVA)
- Polyolefin Elastomer (POE)
- Polyvinyl Butyral (PVB)
- Silicone
- Thermoplastic Polyurethane (TPU)
- Ionomer
- Other Specialty Polymers and Blends
By Product Form
- Films/Sheets
- Liquid Encapsulants
- Coatings/Sprays
By Curing/Processing Method
- Peroxide cross-linked
- Thermoplastic (non-crosslinked)
- UV-curable systems
- Addition-cure Silicones
By Application
- Crystalline Silicon
- Bifacial Modules
- Thin-Film Modules
- Perovskite and Tandem Modules
- Building-Integrated PV (BIPV)
- Flexible/Portable PV Modules
By End-use Deployment
- Residential Rooftop
- Commercial and Industrial Rooftop
- Utility-scale Ground Mount
- Off-grid and Specialty Applications
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The encapsulant materials for PV modules market features a moderately consolidated competitive landscape, with global chemical giants and specialized polymer manufacturers actively expanding their solar-specific portfolios. Leading players such as Dow, DuPont, Mitsui Chemicals, and Wacker Chemie dominate through strong brand presence, proprietary formulations, and global production capabilities. Companies like 3M, SABIC, Covestro, and Eastman Chemical are investing in high-performance encapsulants tailored for bifacial and glass-glass modules. Strategic moves include product innovation, backward integration, and regional manufacturing expansion to secure supply chains and reduce lead times. Firms like Hanwha Solutions and Hangzhou First are gaining traction in Asia through cost-competitive EVA sheets and POE alternatives. Encapsulant innovation focuses on improving UV stability, moisture resistance, and recyclability. The competition intensifies as module makers prioritize long-term reliability and field performance. Market participants are increasingly entering partnerships with module OEMs and research institutes to develop next-gen encapsulation solutions aligned with evolving photovoltaic technologies.
Key Player Analysis
- Eastman Chemical
- Wacker Chemie
- Mitsubishi Chemical
- 3M
- Asahi Kasei
- Covestro
- Dow
- Evonik
- Teijin Limited
- DuPont
- Sumitomo Chemical
- SABIC
- Henkel
- Huntsman
- Toray Industries
Recent Developments
- In July 2025, Alishan unveiled a new generation of encapsulant technologies, including Alishan Low Acid EVA, Alishan EPE-NT, and Alishan EPE-DC. These products are specifically engineered to meet the evolving needs of next-generation solar cells like TOPCon and HJT (Heterojunction Technology), which are known for their durability and greater accessibility.
- In May 2025, Jindal Poly Films Limited (JPL) announced its acquisition of Enerlite Solar Films India, aiming to strengthen its presence in the solar components market. Following the transaction, Enerlite will become a wholly owned subsidiary of JPL. Currently, JPL holds a 33.05% stake in the company. The acquisition is being conducted at arm's length and is expected to be completed within six months, pending regulatory approvals.
- In February 2025, RenewSys, a manufacturer of PV modules, encapsulants, and backsheets, introduced an advanced EVA encapsulant. This technological breakthrough was designed to address a longstanding issue that concerned the lifespan of solar modules.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Product Form, Curing/Processing Method, Application, End-use Deployment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for advanced encapsulants will grow as bifacial and high-efficiency modules continue to expand globally.
- The market will benefit from the global shift to solar energy, driving stable multi-year procurement cycles.
- Thermoplastic materials will see increased use due to recyclability and faster lamination cycle compatibility.
- Leading players will invest in product innovation to meet stricter module reliability and warranty standards.
- EVA will remain dominant by volume, but POE and hybrid materials will gain share in high-performance applications.
- Asia Pacific will retain its lead, holding over 55% share, backed by China's massive PV manufacturing capacity.
- Europe will see growth in premium encapsulants driven by recyclability goals and strict regulatory frameworks.
- North America will gain traction from rising domestic module manufacturing supported by policy incentives.
- Raw material price fluctuations and supply chain risks will continue to challenge cost stability.
- Material compatibility issues with evolving module designs will require ongoing customization and validation efforts.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Global Solar PV Installations
The rapid expansion of solar PV capacity worldwide, driven by government incentives and falling module costs, is directly increasing demand for encapsulant materials that ensure module durability and performance.
Shift Toward High-Efficiency and Bifacial Modules
The adoption of bifacial and high-efficiency PV modules requires advanced encapsulants like POE, which offer superior moisture resistance and electrical insulation, fueling market growth for next-generation materials.
Growing Focus on Module Longevity and Reliability
As solar projects target operational lifespans of 25–30 years, the need for encapsulants with enhanced resistance to UV, heat, and humidity is rising, making material innovation and quality control central to market expansion.
Rise of Thermoplastic Encapsulants and Recyclability Goals
Sustainability initiatives and recycling mandates are driving demand for thermoplastic encapsulants, which enable easier module disassembly and material recovery, aligning with circular economy objectives and regulatory requirements.
Expansion of Utility-Scale and Export-Oriented PV Manufacturing in Asia Pacific
Asia Pacific's dominance in PV module production, supported by cost advantages and robust supply chains, is generating consistent, large-scale demand for encapsulant materials, especially in China, South Korea, and Japan.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Encapsulant materials for PV modules market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Encapsulant materials for PV modules market projected to grow between 2024 and 2032?
Which Encapsulant materials for PV modules market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Encapsulant materials for PV modules market?
Who are the leading companies in the Encapsulant materials for PV modules market?
Which region commanded the largest share of the Encapsulant materials for PV modules market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Crystalline Silicon
- 1.2.2 Bifacial Modules
- 1.2.3 Thin-Film Modules
- 1.2.4 Perovskite and Tandem Modules
- 1.2.5 Building-Integrated PV (BIPV)
- 1.3 By Product Form
- 1.3.1 Films/Sheets
- 1.3.2 Liquid Encapsulants
- 1.3.3 Coatings/Sprays
- 1.4 By Material Type
- 1.4.1 Ethylene-Vinyl Acetate (EVA)
- 1.4.2 Polyolefin Elastomer (POE)
- 1.4.3 Polyvinyl Butyral (PVB)
- 1.4.4 Silicone
- 1.4.5 Thermoplastic Polyurethane (TPU)
- 1.4.6 Ionomer
- 1.5 By Curing/Processing Method
- 1.5.1 Peroxide cross-linked
- 1.5.2 Thermoplastic (non-crosslinked)
- 1.5.3 UV-curable systems
- 1.5.4 Addition-cure Silicones
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,175 million → 2032: USD 3,432.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Encapsulant Material for PV Module Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Encapsulant Material for PV Module Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Encapsulant Material for PV Module Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Encapsulant Material for PV Module Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Encapsulant Material for PV Module Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Encapsulant Material for PV Module Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Encapsulant Material for PV Module Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Encapsulant Material for PV Module Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,175 million → 2032: USD 3,432.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Encapsulant Material for PV Module Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Crystalline Silicon
- 12.3.7.2 Bifacial Modules
- 12.3.7.3 Thin-Film Modules
- 12.3.7.4 Perovskite and Tandem Modules
- 12.3.7.5 Building-Integrated PV (BIPV)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Form - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Films/Sheets
- 12.4.7.2 Liquid Encapsulants
- 12.4.7.3 Coatings/Sprays
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ethylene-Vinyl Acetate (EVA)
- 12.5.7.2 Polyolefin Elastomer (POE)
- 12.5.7.3 Polyvinyl Butyral (PVB)
- 12.5.7.4 Silicone
- 12.5.7.5 Thermoplastic Polyurethane (TPU)
- 12.5.7.6 Ionomer
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Curing/Processing Method - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Peroxide cross-linked
- 12.6.7.2 Thermoplastic (non-crosslinked)
- 12.6.7.3 UV-curable systems
- 12.6.7.4 Addition-cure Silicones
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Encapsulant Material for PV Module End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Encapsulant Material for PV Module Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Encapsulant Material for PV Module Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Encapsulant Material for PV Module Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Dow
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DuPont
- 18.4 Wacker Chemie
- 18.5 3M
- 18.6 Mitsui Chemicals
- 18.7 Hanwha Solutions
- 18.8 Eastman Chemical
- 18.9 Covestro
- 18.10 SABIC
- 18.11 Hangzhou First
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

