
Market Overview:
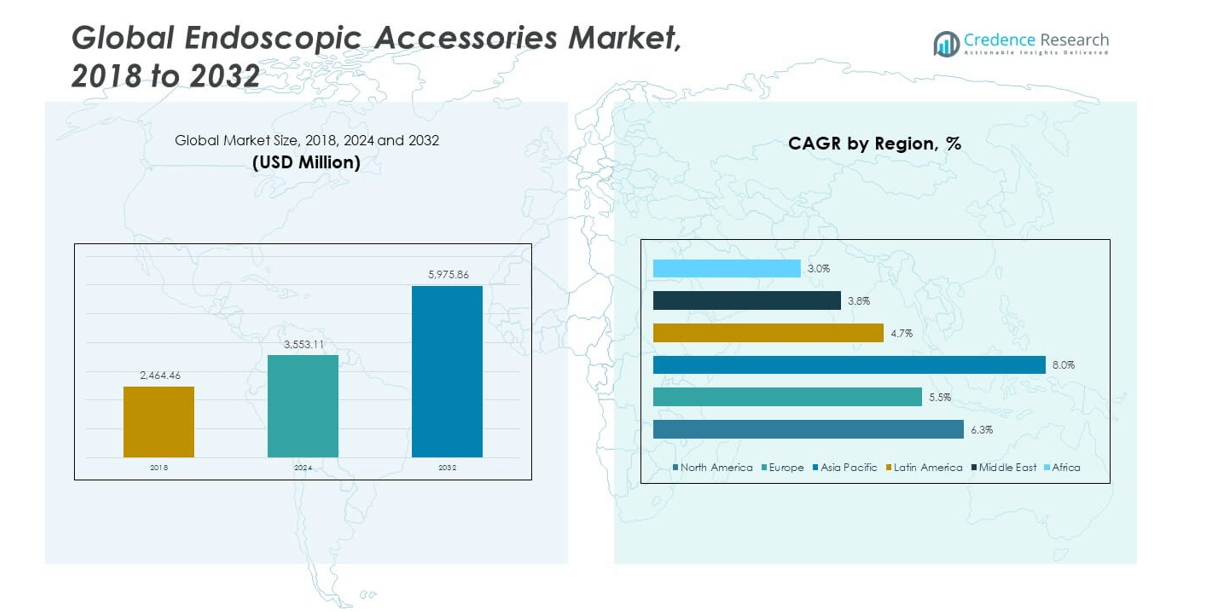
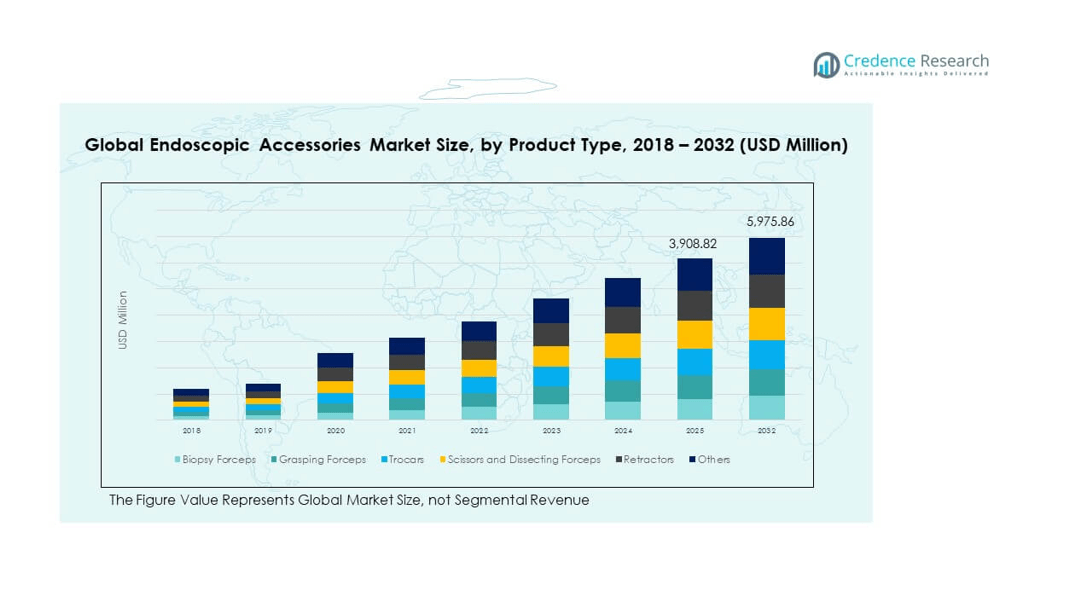
The Global Endoscopic Accessories Market size was valued at USD 2,464.46 million in 2018 to USD 3,553.11 million in 2024 and is anticipated to reach USD 5,975.86 million by 2032, at a CAGR of 6.25% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Endoscopic Accessories Market Size 2024 | USD 3,553.11 million |
| Endoscopic Accessories Market, CAGR | 6.25% |
| Endoscopic Accessories Market Size 2032 | USD 5,975.86 million |
The market growth is driven by rising adoption of minimally invasive surgeries and increasing prevalence of gastrointestinal, urological, and gynecological disorders. Hospitals and ambulatory surgical centers invest in advanced endoscopic instruments to improve procedural precision and patient safety. Technological advancements, including high-definition imaging and ergonomic designs, enhance surgical efficiency. It supports diverse applications and strengthens operational outcomes, encouraging wider adoption among healthcare providers.
North America leads the market due to advanced healthcare infrastructure and high procedural volumes. Europe follows with established healthcare systems and favorable reimbursement policies. Asia Pacific demonstrates rapid growth driven by expanding hospital networks and increasing awareness of minimally invasive procedures. Latin America, Middle East, and Africa show gradual adoption as healthcare infrastructure improves. Emerging markets focus on accessibility, while leading regions emphasize innovation and precision, shaping the global market landscape.
Market Insights
- The Global Endoscopic Accessories Market was valued at USD 2,464.46 million in 2018, reached USD 3,553.11 million in 2024, and is projected to attain USD 5,975.86 million by 2032, growing at a CAGR of 6.25% during the forecast period.
- North America held the largest share of 3% due to advanced healthcare infrastructure, while Europe accounted for 23.3% driven by strong hospital adoption, and Asia Pacific captured 17.1% supported by rapid healthcare expansion.
- Asia Pacific is the fastest-growing region with a CAGR of 8.0%, propelled by increasing demand for minimally invasive procedures and rising government healthcare investments.
- By product type, biopsy forceps led the segment in 2024, driven by their extensive use in diagnostic and therapeutic endoscopic procedures.
- By end user, hospitals dominated the segment due to their large procedural volumes, advanced facilities, and growing adoption of specialized endoscopic instruments.
Market Drivers
Rising Adoption Of Minimally Invasive Procedures In Healthcare Facilities
The Global Endoscopic Accessories Market experiences strong growth due to increasing demand for minimally invasive procedures. Hospitals and clinics prefer endoscopic techniques because they reduce patient recovery time and procedural complications. Surgeons adopt advanced accessories to improve precision and efficiency during operations. It supports early diagnosis of gastrointestinal, respiratory, and urological disorders. Growing patient awareness encourages the selection of safer, less invasive procedures. Healthcare providers invest in training for endoscopic equipment usage. Technological improvements in instruments, such as disposable scopes and high-definition imaging, boost market acceptance. Rising geriatric populations further increase procedural demand.
- For instance, Olympus introduced its EVIS X1™ endoscopy system featuring Texture and Color Enhancement Imaging (TXI™), Red Dichromatic Imaging (RDI™), and Brightness Adjustment Imaging (BAI-MAC™) technologies, designed to enhance lesion, polyp, and vascular visibility during gastrointestinal procedures.
Technological Innovations Enhancing Endoscopic Device Performance And Patient Safety
Innovation in endoscopic accessories drives market expansion significantly. The Global Endoscopic Accessories Market benefits from improvements in high-definition visualization, flexible scopes, and multifunctional tools. It allows surgeons to perform complex procedures with higher accuracy. Enhanced sterilization and disposable accessories improve patient safety and reduce cross-contamination risks. Integration with digital imaging platforms supports real-time data analysis. Medical institutions prioritize equipment that increases procedural efficiency. Manufacturers focus on ergonomic designs to improve surgeon comfort. Advanced instruments lower complication rates and enhance recovery. Regulatory approvals for new technologies reinforce confidence in adoption.
Increasing Prevalence Of Chronic And Gastrointestinal Disorders Globally
Rising cases of gastrointestinal, respiratory, and urological disorders boost the Global Endoscopic Accessories Market demand. Endoscopic procedures support early detection and treatment of chronic illnesses. It enables healthcare providers to monitor disease progression with minimally invasive methods. Growing patient numbers require efficient, accurate diagnostic tools. Surgeons rely on advanced accessories to reduce procedure time and improve outcomes. Hospitals expand endoscopic service offerings to meet patient needs. Health awareness campaigns encourage screening and timely interventions. Market demand rises from both developed and emerging regions. Continuous research enhances product capabilities for complex procedures.
- For example, Fujifilm’s ELUXEO platform is a validated endoscopic system used in gastrointestinal procedures. Its Linked Color Imaging (LCI®) and Blue Light Imaging (BLI®) technologies are documented in peer-reviewed studies to enhance detection of adenomas and early gastric cancer, supporting adoption of advanced endoscopic accessories in clinical practice.
Expanding Healthcare Infrastructure And Investment In Emerging Economies
Infrastructure growth in hospitals and specialty clinics drives Global Endoscopic Accessories Market expansion. Governments and private organizations increase funding for advanced medical equipment. It allows wider availability of endoscopic procedures across regions. Hospitals prioritize acquiring high-quality, efficient accessories. Training programs support healthcare professionals in adopting new technologies. Emerging economies show rising demand due to expanding urban healthcare centers. Improved accessibility encourages patient utilization of endoscopic services. Manufacturers target these regions to strengthen market penetration. Continuous development in healthcare infrastructure sustains long-term growth.
Market Trends
Integration Of Smart Technologies And Digital Solutions In Endoscopic Procedures
The Global Endoscopic Accessories Market experiences a shift toward smart device integration. Instruments now connect to digital platforms for real-time monitoring and data tracking. It allows surgeons to customize procedures and monitor patient vitals simultaneously. Telemedicine applications incorporate endoscopic imaging for remote consultations. Hospitals adopt software solutions to enhance workflow efficiency. Machine learning algorithms support diagnostic accuracy. Data-driven analytics help improve procedural outcomes. Manufacturers continue developing connected and intelligent accessories. This trend enhances operational efficiency and overall patient care quality.
- For example, Olympus’s OLYSENSE™ CAD/AI portfolio represents advanced endoscopic accessories integrated with AI for gastrointestinal procedures. Its tools for polyp detection, Barrett’s esophagus dysplasia identification, and ulcerative colitis scoring enhance diagnostic accuracy, standardize care, and promote adoption of high-tech endoscopic systems, directly influencing market growth.
Development Of Disposable Endoscopic Accessories To Reduce Infection Risks
Disposable accessories gain popularity across the Global Endoscopic Accessories Market. Single-use scopes, forceps, and catheters reduce contamination and infection risk. It supports compliance with strict sterilization protocols in hospitals. Surgeons prefer disposable tools for high-risk or complex procedures. Manufacturing focus shifts toward cost-effective, high-quality disposable products. Hospitals achieve operational efficiency and patient safety simultaneously. Patients experience fewer post-procedure complications. Rising regulatory emphasis on hygiene drives adoption. This trend strengthens confidence in endoscopic interventions globally.
- For example, Boston Scientific’s EXALT™ Model D duodenoscope is a documented single-use endoscopic accessory designed for ERCP procedures. Its disposable design addresses infection risks linked to reusable duodenoscopes, aligning with FDA safety recommendations and supporting safer minimally invasive gastrointestinal interventions.
Miniaturization And Enhanced Design Of Endoscopic Instruments For Precision Procedures
Design innovations in the Global Endoscopic Accessories Market allow better procedural precision. Instruments become smaller, lighter, and more ergonomic. It enables access to complex anatomical regions with minimal trauma. Surgeons achieve improved visualization and maneuverability during procedures. Advanced optics enhance real-time imaging accuracy. Device customization improves compatibility with various endoscopic systems. Manufacturers emphasize lightweight and durable materials for ease of use. High-performance designs attract hospitals seeking state-of-the-art equipment. Miniaturized tools expand application in specialized surgical procedures.
Rising Adoption Of Advanced Imaging Technologies In Endoscopic Surgeries
Advanced imaging drives the Global Endoscopic Accessories Market toward higher precision. High-definition cameras, 3D imaging, and narrow-band imaging improve diagnostic accuracy. It allows physicians to detect subtle lesions and abnormalities during procedures. Hospitals implement advanced imaging to enhance patient outcomes. Endoscopic accessories integrate seamlessly with imaging platforms. Surgeons gain better control over visualization and procedure planning. Continuous upgrades improve efficiency and reduce complication rates. Imaging advancements encourage adoption in both urban and emerging healthcare centers. Patients benefit from faster diagnosis and improved recovery.
Market Challenges Analysis
High Costs And Complex Regulatory Requirements Affecting Market Growth
The Global Endoscopic Accessories Market faces challenges from high equipment costs. Hospitals and clinics often struggle with budget constraints. It limits access in smaller or rural healthcare facilities. Regulatory approvals require extensive clinical trials and documentation. Manufacturers spend significant time meeting international safety standards. Complex compliance procedures delay product launches. Procurement decisions involve cost-benefit analysis for expensive tools. This slows market penetration in developing regions. Price-sensitive healthcare systems may favor conventional alternatives.
Limited Awareness And Skilled Professionals Restricting Endoscopic Adoption
Awareness gaps among healthcare providers impact the Global Endoscopic Accessories Market. Many surgeons require specialized training for advanced tools. It affects adoption rates in emerging and rural regions. Limited knowledge about procedural benefits discourages investment in new accessories. Hospitals may lack adequate staff to operate sophisticated equipment. Patient awareness remains low for minimally invasive alternatives. Manufacturers invest in training programs to bridge knowledge gaps. Technical skill shortages restrict full utilization of market potential. Slow adoption in certain regions constrains overall market expansion.
Market Opportunities
Expansion Into Emerging Economies With Growing Healthcare Infrastructure
The Global Endoscopic Accessories Market gains opportunities in emerging regions. Hospitals and specialty clinics expand infrastructure and acquire modern equipment. It allows manufacturers to introduce advanced accessories to new markets. Rising urban populations increase demand for minimally invasive procedures. Governments support healthcare modernization through investments and incentives. Partnerships with local distributors improve market penetration. Increasing chronic disease prevalence drives procedural volume. Market players can focus on affordable, high-quality instruments. Opportunities grow with expanding healthcare access and awareness.
Innovations In Endoscopic Device Technology Creating New Market Segments
Innovation in the Global Endoscopic Accessories Market generates opportunities for differentiated products. Companies develop advanced imaging, flexible instruments, and single-use tools. It allows surgeons to perform complex procedures efficiently and safely. Hospitals seek devices that enhance procedural accuracy and patient outcomes. Integration with digital platforms expands operational efficiency. Research and development in materials and design create new product lines. Enhanced functionality attracts adoption in both mature and emerging markets. Continuous technological breakthroughs support long-term growth prospects.
Market Segmentation Analysis:
The Global Endoscopic Accessories Market demonstrates diverse growth across product types, applications, and end users.
By product type, biopsy forceps and grasping forceps dominate demand due to their frequent use in gastrointestinal and laparoscopic procedures. Trocars and scissors with dissecting forceps maintain steady adoption in specialized surgeries. Retractors and other instruments complement procedural efficiency and surgeon precision. It supports a broad range of minimally invasive interventions while enhancing patient safety and reducing procedural complications.
- For instance, Boston Scientific’s Radial Jaw 4 biopsy forceps are documented in official product materials as single-use instruments designed to obtain larger and more consistent tissue specimens through improved jaw design, enhancing diagnostic accuracy during endoscopic procedures.
By application, gastrointestinal surgery holds the largest share, driven by rising prevalence of digestive disorders and routine screenings. Laparoscopic surgery follows, benefiting from increasing adoption of minimally invasive techniques. Urological and gynecological surgeries show consistent growth due to procedural advancements and improved surgical outcomes. Other applications, including thoracic and ENT procedures, contribute to market expansion.
By end user, hospitals lead demand due to high procedural volume and investment in advanced equipment. Ambulatory surgery centers (ASCs) adopt endoscopic accessories for cost-efficient outpatient procedures. Clinics and specialty care centers gradually increase utilization, driven by growing patient awareness and accessibility to minimally invasive interventions. It reinforces market penetration across both urban and semi-urban regions, supporting long-term growth.
- For instance, according to data from the Society of American Gastrointestinal and Endoscopic Surgeons (SAGES) and the World Journal of Surgery, hospitals adopting minimally invasive surgery (MIS) techniques have reported shorter recovery times and reduced postoperative complications compared to conventional open surgery, confirming the global shift toward MIS-based operating departments.
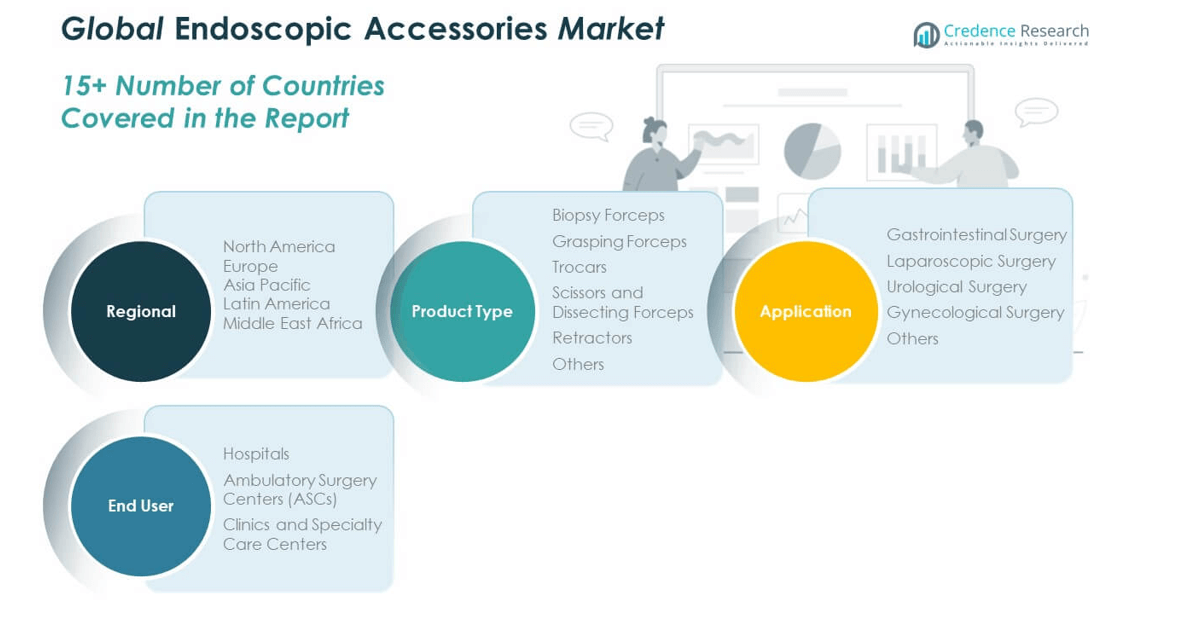
Segmentation:
By Product Type
- Biopsy Forceps
- Grasping Forceps
- Trocars
- Scissors and Dissecting Forceps
- Retractors
- Others
By Application
- Gastrointestinal Surgery
- Laparoscopic Surgery
- Urological Surgery
- Gynecological Surgery
- Others
By End User
- Hospitals
- Ambulatory Surgery Centers (ASCs)
- Clinics and Specialty Care Centers
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Global Endoscopic Accessories Market size was valued at USD 1,090.14 million in 2018 and grew to USD 1,555.59 million in 2024. It is anticipated to reach USD 2,623.46 million by 2032, at a CAGR of 6.3% during the forecast period. North America holds a market share of approximately 29% in 2024. It leads due to advanced healthcare infrastructure, widespread adoption of minimally invasive procedures, and high investment in medical technologies. Hospitals and specialty clinics prioritize acquiring high-quality endoscopic accessories. Surgeons rely on advanced tools for precision and efficiency. Regulatory support and reimbursement policies encourage procedural adoption. Continuous innovation by key manufacturers strengthens the region’s market dominance.
Europe
The Europe Global Endoscopic Accessories Market size was valued at USD 700.48 million in 2018 and reached USD 973.58 million in 2024. It is projected to reach USD 1,541.81 million by 2032, at a CAGR of 5.5%. Europe accounts for a market share of around 18% in 2024. It benefits from established healthcare systems, favorable reimbursement frameworks, and high patient awareness. Hospitals and ambulatory surgical centers adopt advanced endoscopic technologies. The region emphasizes precision in gastrointestinal and laparoscopic procedures. Manufacturers focus on compliance with stringent safety standards. Continuous upgrades in imaging and instrument design support market growth.
Asia Pacific
The Asia Pacific Global Endoscopic Accessories Market size was valued at USD 455.11 million in 2018 and reached USD 713.48 million in 2024. It is expected to reach USD 1,365.16 million by 2032, at a CAGR of 8.0%. Asia Pacific represents approximately 13% of the global market in 2024. Rapid urbanization, rising healthcare expenditure, and expanding hospital networks drive growth. It supports increasing demand for minimally invasive surgeries. Countries like China, Japan, and India lead adoption. Growing awareness of gastrointestinal and urological disorders further boosts the market. Manufacturers target affordable, high-quality devices for emerging markets. The region demonstrates strong potential for long-term expansion.
Latin America
The Latin America Global Endoscopic Accessories Market size was valued at USD 118.60 million in 2018 and grew to USD 168.90 million in 2024. It is projected to reach USD 252.04 million by 2032, at a CAGR of 4.7%. Latin America holds approximately 3% of the global market share. It benefits from improving healthcare infrastructure and increased procedural awareness. Hospitals in Brazil and Argentina adopt advanced endoscopic tools. Clinics and ambulatory centers gradually expand usage. Rising prevalence of chronic gastrointestinal and urological disorders supports demand. Investment in modern equipment improves procedural efficiency. Manufacturers focus on targeted regional growth strategies.
Middle East
The Middle East Global Endoscopic Accessories Market size was valued at USD 64.65 million in 2018 and reached USD 84.66 million in 2024. It is expected to reach USD 118.49 million by 2032, at a CAGR of 3.8%. The region accounts for roughly 1.5% of the global market in 2024. It grows due to increased government investment in healthcare infrastructure. Hospitals and specialty clinics adopt advanced instruments for minimally invasive procedures. Surgeons prioritize efficiency and patient safety in procedural choices. Key countries include GCC nations, Israel, and Turkey. Regulatory support encourages technology adoption. Focus on modern equipment drives market expansion.
Africa
The Africa Global Endoscopic Accessories Market size was valued at USD 35.47 million in 2018 and reached USD 56.90 million in 2024. It is projected to reach USD 74.90 million by 2032, at a CAGR of 3.0%. Africa represents around 1% of the global market share. Market growth is driven by improving medical infrastructure and increasing awareness of minimally invasive procedures. Hospitals in South Africa and Egypt lead adoption. Clinics and specialty centers gradually introduce endoscopic instruments. Training programs for surgeons enhance procedural capabilities. Manufacturers explore partnerships to expand market presence. Steady growth reflects untapped regional opportunities.
Key Player Analysis:
- Medtronic plc
- Johnson & Johnson (Ethicon)
- Olympus Corporation
- Stryker Corporation
- Braun Melsungen AG
- Boston Scientific Corporation
- CONMED Corporation
- Cook Medical, Inc.
- Richard Wolf GmbH
- KARL STORZ SE & Co. KG
Competitive Analysis:
The Global Endoscopic Accessories Market features a highly competitive landscape with key players focusing on innovation, strategic partnerships, and regional expansion. Companies such as Medtronic plc, Johnson & Johnson (Ethicon), Olympus Corporation, and Stryker Corporation lead market share through advanced product portfolios and technological upgrades. It experiences continuous new product launches targeting precision, safety, and minimally invasive procedures. Mergers and acquisitions strengthen market positions and expand geographical reach. Firms invest in research and development to improve instrument functionality and efficiency. Price strategies and service support play a critical role in securing hospital and clinic contracts. Smaller players adopt niche specialization to capture emerging opportunities. Regulatory compliance and high-quality standards remain essential for market participation. The competitive dynamics drive continuous innovation, improving procedural outcomes and enhancing adoption across global healthcare systems.
Recent Developments:
- In July 2025, Olympus announced a strategic partnership with Revival Healthcare Capital to co-found Swan EndoSurgical, a robotics company developing a novel endoluminal system for more precise and less invasive gastrointestinal treatments. The combined initial investment exceeds $65 million, with total funding to reach up to $458 million if milestones are met.
- In June 2025, Ethicon, part of Johnson & Johnson, launched an advanced stapling system and revealed plans to harness this technology for the OTTAVA™ Robotic Surgical System. This launch demonstrates Ethicon’s growing footprint in robotic-assisted surgery and innovative surgical accessories.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of minimally invasive surgeries will continue to drive market expansion.
- Technological advancements in high-definition imaging and disposable instruments will enhance procedural efficiency.
- Growing prevalence of gastrointestinal, urological, and gynecological disorders will increase device demand.
- Expansion of healthcare infrastructure in emerging economies will open new market opportunities.
- Integration of smart and connected devices will enable real-time procedural monitoring.
- Hospitals and ambulatory surgical centers will remain primary end users driving consistent adoption.
- Continuous product innovation will strengthen market competitiveness and operational performance.
- Regulatory approvals and compliance will support safe adoption of advanced accessories.
- Increasing awareness among patients and healthcare providers will boost procedural utilization.
- Strategic partnerships, mergers, and regional expansion by manufacturers will sustain long-term growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Endoscopic Accessories Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Endoscopic Accessories Market projected to grow between 2024 and 2032?
Which Global Endoscopic Accessories Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Endoscopic Accessories Market?
Who are the leading companies in the Global Endoscopic Accessories Market?
Which region commanded the largest share of the Global Endoscopic Accessories Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,553.11 million → 2032: USD 5,975.86 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Endoscopic Accessories Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Endoscopic Accessories Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Endoscopic Accessories Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Endoscopic Accessories Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Endoscopic Accessories Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Endoscopic Accessories Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Endoscopic Accessories Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Endoscopic Accessories Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,553.11 million → 2032: USD 5,975.86 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Endoscopic Accessories Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Endoscopic Accessories Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Endoscopic Accessories Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Endoscopic Accessories Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

