
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Clinical Trial Management System (CTMS) Market Size 2024 | USD 326.07 million |
| Europe Clinical Trial Management System (CTMS) Market, CAGR | 10.42% |
| Europe Clinical Trial Management System (CTMS) Market Size 2032 | USD 795.93 million |
Market Overview
The Europe Clinical Trial Management System (CTMS) Market is projected to grow from USD 326.07 million in 2024 to an estimated USD 795.93 million by 2032, with a compound annual growth rate (CAGR) of 10.42% from 2025 to 2032. This growth is attributed to the increasing demand for advanced clinical trial management solutions in the pharmaceutical and biotechnology sectors, as organizations look to streamline operations and improve efficiency in their clinical trial processes.
Several factors are driving the market, including the increasing adoption of cloud-based CTMS platforms, which offer enhanced flexibility, scalability, and cost-efficiency. The growing trend towards data integration and automation within clinical trials is also accelerating market growth. Additionally, the rising need for regulatory compliance, along with the expansion of clinical trials across multiple regions, is further boosting the demand for CTMS solutions.
Geographically, Europe remains a key region in the CTMS market, with significant contributions from countries such as Germany, the UK, and France. The presence of well-established pharmaceutical companies, research institutions, and regulatory bodies fosters a robust clinical trial environment. Key players in the market include Veeva Systems, Medidata Solutions, Parexel International Corporation, Oracle Corporation, and IBM Corporation, which are leading the development and adoption of advanced CTMS technologies across the region.
Market Insights
- The Europe Clinical Trial Management System (CTMS) market is projected to grow from USD 326.07 million in 2024 to USD 795.93 million by 2032, with a CAGR of 10.42% from 2025 to 2032.
- The global CTMS market is projected to grow from USD 1,230.00 million in 2024 to USD 3,197.78 million by 2032, with a CAGR of 11.20%. The demand for efficient and streamlined management of clinical trials drives this growth.
- Key drivers include the increasing adoption of cloud-based CTMS platforms, the growing need for regulatory compliance, and the expansion of clinical trials across multiple regions, particularly in the pharmaceutical and biotechnology sectors.
- High implementation and maintenance costs, along with challenges related to data integration and interoperability across different clinical systems, are significant barriers to market growth.
- The demand for cloud-based CTMS solutions is rising due to their scalability, cost-efficiency, and ability to improve real-time data access and collaboration across global trial networks.
- The increasing complexity of regulatory requirements, such as GDPR, is driving the demand for CTMS platforms that ensure compliance and data security in clinical trial management.
- Western Europe remains the dominant region in the CTMS market, with significant contributions from Germany, the UK, and France, supported by well-established pharmaceutical companies and research institutions.
- Eastern Europe is emerging as a cost-effective hub for clinical trials, driving the adoption of CTMS solutions in the region due to lower operational costs and a growing clinical research infrastructure.
Market Drivers
Increased Regulatory Scrutiny and Need for Compliance
In Europe, the healthcare and pharmaceutical sectors face stringent regulatory standards, and adherence to these regulations is critical for the success of clinical trials. The European Medicines Agency (EMA) and other regulatory bodies impose strict guidelines on the conduct of clinical trials, necessitating the use of systems that can ensure compliance with all local and international regulations. CTMS solutions help organizations track and maintain compliance with these complex regulatory requirements, including those related to data security, trial monitoring, patient safety, and reporting. With the implementation of the EU Clinical Trials Regulation (CTR) in recent years, which aims to make clinical trials more transparent and efficient, the demand for CTMS systems that help companies stay compliant has risen significantly. Additionally, as data privacy concerns continue to be a major focus in the European Union, CTMS solutions with built-in GDPR compliance are increasingly in demand to safeguard sensitive patient information. The growing need for compliance and accurate reporting has positioned CTMS as an essential tool for clinical trial management in Europe.
Technological Advancements and Integration with Other Technologies
Technological advancements are playing a crucial role in driving the growth of the Clinical Trial Management System market in Europe. Integration with other technologies, such as artificial intelligence (AI), machine learning (ML), big data analytics, and blockchain, is enhancing the functionality of CTMS platforms. AI and ML can automate data analysis, detect anomalies, predict trial outcomes, and improve decision-making, reducing the time and cost of trials. The integration of big data analytics enables organizations to analyze large volumes of trial data, allowing for better insights into patient outcomes, drug efficacy, and overall trial performance. Blockchain technology, on the other hand, is being explored for its potential to ensure data integrity, transparency, and security in clinical trials. The ability to integrate CTMS with electronic health records (EHR), electronic medical records (EMR), and other clinical data management systems is also contributing to the growth of the market, as it ensures that all data is connected and accessible across platforms. These technological advancements help improve the overall efficiency of clinical trials, reduce errors, and enhance the quality of data collected, thereby driving the adoption of CTMS solutions across Europe.
Rising Adoption of Cloud-Based CTMS Solutions
The increasing shift towards cloud-based Clinical Trial Management Systems (CTMS) is one of the most significant drivers of the European market. Cloud technology provides numerous advantages over traditional on-premise solutions, such as enhanced flexibility, scalability, and cost-efficiency. Organizations in the pharmaceutical and biotechnology sectors are increasingly adopting cloud-based CTMS solutions to streamline clinical trial processes, improve data management, and reduce operational costs. For instance, 75% of European pharmaceutical companies have transitioned to cloud-based CTMS platforms to enhance collaboration and data accessibility. These cloud platforms offer easy access to real-time data, facilitating better collaboration across different stakeholders, including sponsors, CROs (Contract Research Organizations), and clinical sites. With data security and privacy concerns being paramount, cloud-based systems in Europe are designed to comply with GDPR (General Data Protection Regulation), making them attractive to companies operating within the region. Furthermore, the ability to integrate cloud-based CTMS solutions with other enterprise software, such as electronic data capture (EDC) systems and laboratory information management systems (LIMS), allows for seamless workflows and more efficient trial management.
Increase in Number and Complexity of Clinical Trials
The growing number and increasing complexity of clinical trials are also major drivers propelling the CTMS market in Europe. As the healthcare landscape evolves, there is an increasing demand for new and improved drugs, therapies, and medical devices, which drives the need for more clinical trials. These trials are becoming more complex, with multi-center studies, larger sample sizes, and the inclusion of a wider variety of patient populations. For instance, the average number of sites per clinical trial in Europe has increased by 30% over the past five years, reflecting the growing complexity of trial designs. Managing these large and complex clinical trials requires sophisticated systems that can track various elements such as patient enrollment, adverse event reporting, regulatory compliance, and study progress. Clinical Trial Management Systems are designed to automate and optimize these processes, helping sponsors and CROs ensure trials are conducted on time, within budget, and in compliance with regulatory standards. This demand for efficiency, compliance, and scalability has fueled the growth of CTMS adoption in Europe, as more companies seek to handle the complexity of modern clinical trials effectively.
Market Trends
Focus on Patient-Centric Approaches
Patient-centricity is an emerging trend in the Clinical Trial Management System market in Europe. As clinical trials become more complex, ensuring that the patient experience is optimized has become a priority. This shift involves creating systems that make clinical trials more accessible, comfortable, and engaging for patients, which in turn can improve recruitment, retention, and compliance rates. CTMS solutions are being developed with features that support patient engagement through mobile applications, virtual monitoring, and real-time communication with clinical teams. By leveraging digital tools, CTMS platforms help keep patients informed, track their progress, and collect feedback, enhancing their overall experience. Furthermore, the implementation of remote monitoring and decentralized trials is reducing patient burdens by allowing participants to take part from the comfort of their homes. These patient-focused approaches not only improve the success rate of clinical trials but also help in meeting the growing demand for more personalized and efficient healthcare solutions in Europe.
Regulatory Compliance and Data Security
Regulatory compliance remains a key focus in the European Clinical Trial Management System market, especially with the stringent data protection regulations enforced by the European Union (EU). GDPR has significantly impacted how clinical trial data is managed, requiring CTMS platforms to comply with strict standards for data privacy and security. As clinical trials often involve sensitive patient data, ensuring the integrity and confidentiality of that data is crucial. CTMS providers are investing heavily in security features such as encryption, secure data storage, and user access controls to meet compliance requirements. Additionally, the European Medicines Agency (EMA) has implemented new regulations to streamline clinical trial approval processes, creating a need for CTMS systems that can handle the complexities of these regulations. As a result, regulatory compliance and data security are now integrated into the core functionalities of CTMS solutions, and these platforms are evolving to meet the growing demands for compliance in the European healthcare and pharmaceutical industries.
Shift Towards Cloud-Based CTMS Solutions
Cloud-based Clinical Trial Management Systems (CTMS) have become increasingly popular in the European market due to their numerous advantages, including flexibility, scalability, and cost-efficiency. For instance, Parexel International Corporation has conducted over 250 fully virtual or hybrid decentralized clinical trials (DCTs), leveraging cloud-based CTMS platforms to facilitate seamless data integration and collaboration among global teams. These platforms also comply with stringent data security regulations like GDPR in the European Union, ensuring a secure environment for patient data storage. Additionally, cloud-based systems enhance the speed and efficiency of clinical trials by allowing real-time data access, monitoring, and decision-making, which ultimately accelerates the entire clinical trial process. The demand for cloud solutions is driven by the growing need for remote monitoring and the ability to handle large amounts of clinical data generated from trials.
Integration with Artificial Intelligence and Data Analytics
The integration of Artificial Intelligence (AI) and data analytics into Clinical Trial Management Systems is a growing trend in Europe. For instance, AI-powered predictive analytics tools are being used to identify potential patient recruitment challenges and optimize clinical trial designs, significantly reducing trial delays. Additionally, these technologies automate routine administrative tasks, such as data entry and management, saving time and reducing human error. AI-driven solutions also enhance patient recruitment by identifying suitable candidates from vast databases, improving trial enrollment timelines. Data analytics tools further allow organizations to derive actionable insights from trial data, improving decision-making and trial outcomes. This integration is streamlining clinical trial processes and enhancing the efficiency of clinical research organizations across Europe.
Market Challenges
High Implementation and Maintenance Costs
The Europe Clinical Trial Management System (CTMS) market faces significant challenges due to high initial implementation and ongoing maintenance costs. For instance, the adoption of CTMS platforms involves substantial investments in software purchase, customization, and training. Companies often need to allocate resources for integrating these systems with existing infrastructure, which can be both time-consuming and costly. Additionally, as clinical trials become more complex, frequent updates and additional modules are required to comply with evolving regulations and technologies. For example, organizations may need to implement advanced features such as electronic data capture (EDC) integration or real-time monitoring tools, which further increase the financial burden. The need for highly skilled personnel to manage and maintain these systems adds another layer of expense, as companies must invest in training or hiring specialized IT staff. Despite the long-term benefits of improved trial efficiency and compliance, the upfront financial commitment remains a significant hurdle, particularly for small and mid-sized organizations. Addressing these challenges requires strategic planning and innovative approaches to reduce costs while maintaining the effectiveness of CTMS solutions.
Data Integration and Interoperability Issues
Another key challenge in the European CTMS market is the issue of data integration and interoperability across various clinical trial management platforms. Clinical trials generate a large volume of data from multiple sources, including electronic data capture (EDC) systems, laboratory information management systems (LIMS), and patient management systems. Ensuring that this data is seamlessly integrated and accessible across all systems can be complex and time-consuming. Many CTMS platforms are not inherently designed to integrate smoothly with other software applications, leading to data silos and inefficiencies. This lack of interoperability can hinder real-time data exchange, slowing down decision-making processes and delaying trial progress. Additionally, regulatory requirements in Europe, such as the General Data Protection Regulation (GDPR), add an extra layer of complexity, as organizations must ensure that all systems comply with stringent data privacy and security regulations. The challenge of achieving seamless data integration and ensuring consistent data quality across various platforms continues to be a significant hurdle for clinical research organizations, pharmaceutical companies, and other stakeholders involved in clinical trials in Europe.
Market Opportunities
Growth in Decentralized and Virtual Clinical Trials
The European Clinical Trial Management System (CTMS) market presents significant opportunities with the growing trend towards decentralized and virtual clinical trials. These types of trials, which leverage digital technologies for remote patient monitoring, virtual visits, and data collection, are becoming increasingly popular in Europe, particularly due to the COVID-19 pandemic. As these trials reduce patient travel and site visits, they offer a more patient-centric approach and can accelerate recruitment and retention rates. CTMS providers have the opportunity to develop solutions that specifically cater to the needs of virtual trials, offering features like integrated telemedicine capabilities, remote patient monitoring, and real-time data analytics. This trend is expected to drive demand for CTMS platforms that can handle decentralized trial workflows, ensuring that clinical trial data remains accurate, secure, and compliant with regulatory standards. As more pharmaceutical companies and contract research organizations (CROs) adopt decentralized trial models, the need for advanced CTMS solutions that can support these trials will continue to rise.
Expansion of Regulatory Compliance Features
As regulatory requirements in Europe, such as the EU Clinical Trials Regulation (CTR) and the General Data Protection Regulation (GDPR), continue to evolve, there is a growing opportunity for CTMS providers to enhance their platforms with advanced compliance features. These systems must ensure adherence to local and international regulations concerning patient data privacy, trial reporting, and safety monitoring. CTMS platforms that incorporate automated compliance tools, such as real-time tracking of regulatory submissions and audits, are well-positioned to meet the increasing demands for regulatory scrutiny in clinical trials. Additionally, with the expansion of personalized medicine and the need for more complex data collection, CTMS providers have the opportunity to offer customized solutions that ensure compliance across diverse trial models, further cementing their value in the European market.
Market Segmentation Analysis
By Deployment
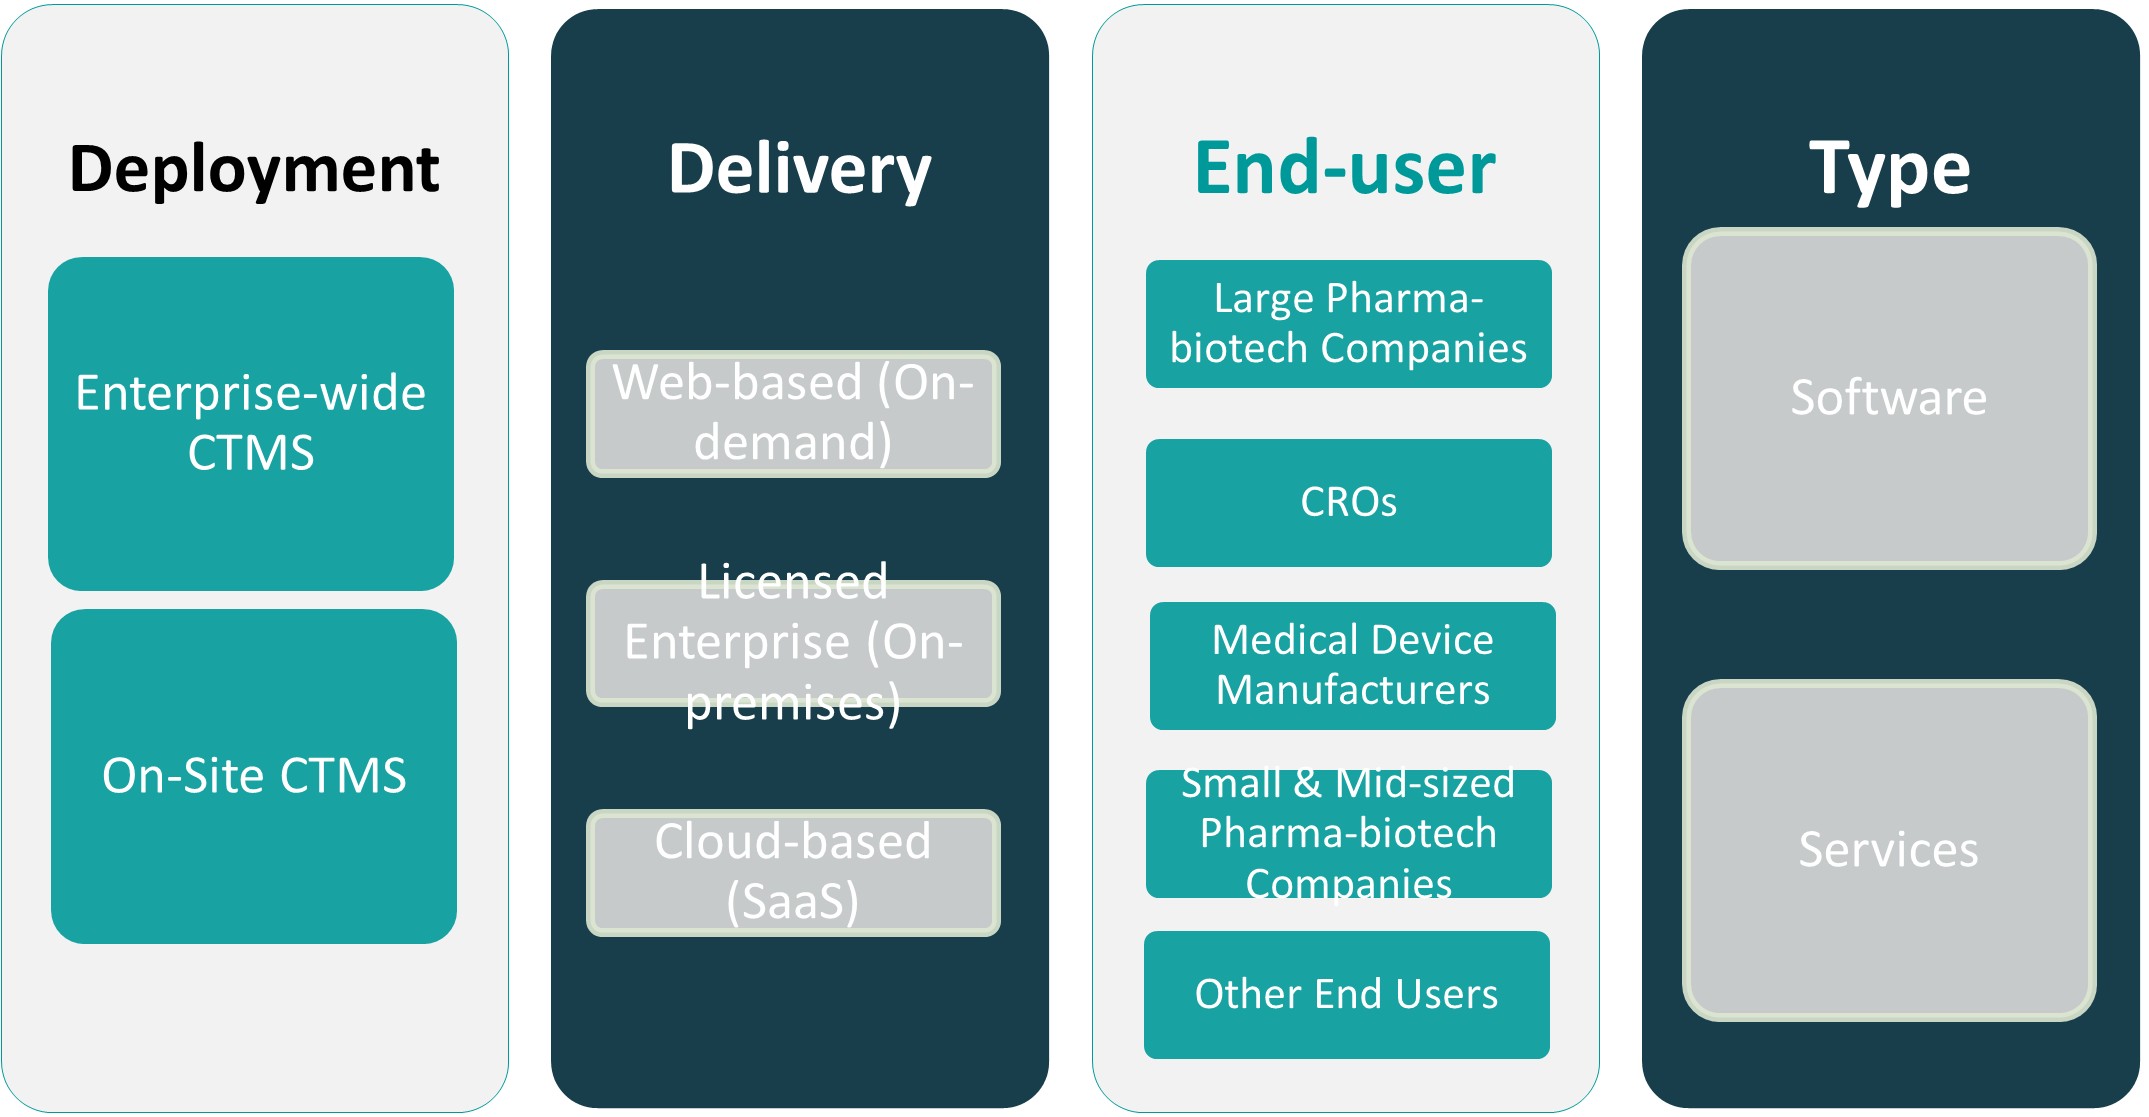
The market is categorized into enterprise-wide CTMS and on-site CTMS. Enterprise-wide CTMS solutions are gaining prominence due to their ability to offer centralized control over multiple clinical trial processes across various locations. They enable organizations to standardize workflows, improve data consistency, and maintain regulatory compliance across global operations. On-site CTMS, although more limited in scope, remains relevant for smaller organizations or trials conducted within localized research facilities.
By Delivery
The market is segmented into web-based (on-demand), licensed enterprise (on-premises), and cloud-based (SaaS) solutions. Cloud-based CTMS (Software-as-a-Service) is emerging as the fastest-growing segment, owing to its cost-effectiveness, ease of deployment, remote access capabilities, and scalability. Web-based CTMS offers flexible accessibility and rapid implementation, making it ideal for CROs and small to mid-sized companies. Licensed enterprise solutions, while offering enhanced control and security, are gradually being phased out in favor of more agile and cost-efficient cloud models.
Segments
Based on Deployment
- Enterprise-wide CTMS
- On-Site CTMS
Based on Delivery
- Web-based (On-demand)
- Licensed Enterprise (On-premises)
- Cloud-based (SaaS)
Based on End User
- Large Pharma-biotech Companies
- CROs
- Medical Device Manufacturers
- Small & Mid-sized Pharma-biotech Companies
- Other End Users
Based on Type
- Software
- Services
Based on Region
- Western Europe
- Eastern Europe
- Northern Europe
- Southern Europe
Regional Analysis
Western Europe (70%)
Western Europe holds the largest market share, accounting for approximately 70% of the total market. This region is home to well-established pharmaceutical companies, clinical research organizations (CROs), and academic institutions, driving high demand for CTMS solutions. Key countries such as Germany, the UK, France, and Switzerland play a pivotal role in market expansion, largely due to their robust pharmaceutical and biotechnology sectors. The presence of global pharmaceutical giants in these countries creates a substantial need for advanced CTMS platforms to manage complex, multi-center clinical trials. Furthermore, the strong regulatory frameworks, such as the European Medicines Agency (EMA) guidelines and the EU Clinical Trials Regulation, stimulate demand for CTMS systems that ensure compliance with regional and international standards. The rising adoption of cloud-based and SaaS CTMS solutions in this region is also contributing to its dominant position in the market.
Eastern Europe (15%)
Eastern Europe is emerging as a rapidly growing region for the CTMS market, with a market share of approximately 15%. Countries such as Poland, Russia, and the Czech Republic are becoming popular hubs for clinical trials due to lower operational costs and an expanding pool of clinical research talent. The region benefits from an increasingly favorable regulatory environment and government incentives that promote the growth of the healthcare and pharmaceutical sectors. As more pharmaceutical companies and contract research organizations (CROs) turn to Eastern Europe for cost-effective trial management solutions, the demand for CTMS systems is expected to rise. The adoption of cloud-based solutions is particularly notable in this region, as it provides scalability and flexibility for smaller and mid-sized companies.
Key players
- Forte Research Systems
- ICON plc
- Merge Healthcare Incorporated
- Bio-Optronics
- DSG Inc.
- ArisEurope
- ERT Clinical Bioclinica
- Oracle Corporation
- Medidata Solutions
- DATATRAK International, Inc.
Competitive Analysi
The Europe Clinical Trial Management System (CTMS) market is highly competitive, with key players such as Forte Research Systems, ICON plc, and Medidata Solutions leading the charge in offering comprehensive, user-friendly platforms. Companies like Oracle and Merge Healthcare bring established technological expertise, focusing on scalability and seamless integration with existing IT systems. The market is also seeing a surge in cloud-based solutions offered by Bio-Optronics and DATATRAK, catering to the growing demand for flexibility and cost-efficiency. ERT Clinical Bioclinica and DSG Inc. differentiate themselves by emphasizing patient-centric solutions, integrating remote monitoring features into their platforms. Smaller players like ArisEurope are capitalizing on niche markets, providing specialized CTMS solutions tailored to specific clinical research needs. The competitive landscape is characterized by continuous innovation, with key players expanding their product portfolios and refining their offerings to meet the evolving demands of the clinical trial industry in Europe.
Recent Developments
- In May 2024, ICON released its ICON Cares 2023 Report, highlighting initiatives to increase patient access to clinical trials and drive innovation through technology and partnerships.
- In July 2024, Merative released new versions of Merge Imaging Suite components, enhancing usability, deployment, and maintenance.
- In February 2025, Oracle was recognized as a 'Leader' in the Everest Group Life Sciences CTMS Products PEAK Matrix Assessment 2024.
- In February 2025, Medidata secured the SCOPE Best of Show Award for Clinical Data Studio.
- In 2024, ArisGlobal reported significant customer growth, including 11 new top-tier pharma LifeSphere customers and a 40% year-over-year increase in new customers in the Asia Pacific region.
Market Concentration and Characteristic
The Europe Clinical Trial Management System (CTMS) market is moderately concentrated, with a mix of established global players and specialized providers catering to distinct market needs. Major companies like Oracle, Medidata Solutions, and ICON plc hold significant market share, leveraging their extensive product portfolios, technological expertise, and global reach. These players dominate the market with comprehensive solutions that address large-scale, complex clinical trials. However, smaller and niche players, such as Forte Research Systems, Bio-Optronics, and DATATRAK, are gaining traction by offering tailored solutions that meet specific regional or industry requirements, such as cloud-based or patient-centric platforms. The market is characterized by a high level of innovation, with a focus on integrating advanced technologies like AI, machine learning, and cloud solutions to enhance trial efficiency, compliance, and patient engagement. As regulatory frameworks evolve, particularly with GDPR in Europe, CTMS providers are also emphasizing data security and compliance as key differentiators.
Report Coverage
The research report offers an in-depth analysis based on Deployment, Delivery, End User, Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud-based CTMS solutions are expected to dominate, driven by their cost-efficiency, scalability, and flexibility. Organizations will increasingly move towards cloud systems for better remote access and real-time data management.
- AI will play a crucial role in automating data analysis, patient recruitment, and risk-based monitoring, improving the efficiency of clinical trials. The integration of AI into CTMS platforms will help streamline decision-making and optimize trial outcomes.
- The shift towards decentralized clinical trials will accelerate, as remote patient monitoring and virtual visits gain popularity. CTMS platforms will evolve to support these decentralized trial models, enhancing patient engagement and retention.
- As regulatory frameworks like GDPR continue to evolve, CTMS platforms will focus on ensuring compliance and enhancing data security. Providers will integrate advanced features to safeguard patient information and meet evolving regulatory standards.
- Small and mid-sized pharmaceutical companies will increasingly adopt CTMS solutions to streamline trial processes. Cloud-based and on-demand systems will provide these organizations with cost-effective solutions to manage complex trials.
- The growing emphasis on personalized medicine will drive the demand for specialized CTMS solutions. These systems will help manage the complexities of individualized patient trials, improving both efficiency and outcomes.
- Collaborations between CTMS providers and pharmaceutical companies or CROs will increase. Mergers and acquisitions in the CTMS market will allow providers to expand their technological capabilities and market reach.
- The integration of big data analytics will enable CTMS platforms to handle vast amounts of trial data. Advanced analytics will provide deeper insights into patient outcomes, drug efficacy, and overall trial performance.
- Eastern Europe will emerge as a key growth region for CTMS solutions, driven by cost-effective clinical trials and expanding healthcare infrastructures. Companies will increasingly look to this region for outsourced trial management services.
- CTMS solutions will become more patient-centric, with features such as mobile apps and remote monitoring. This shift will aim to improve the patient experience, leading to higher participation rates and better adherence to trial protocols.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Regulatory Scrutiny and Compliance Needs
Stringent regulations from bodies like the EMA and the implementation of the EU Clinical Trials Regulation (CTR) are driving demand for CTMS platforms that ensure compliance, data security, and transparent reporting, making these systems essential for successful clinical trial management in Europe.
Rising Adoption of Cloud-Based CTMS Solutions
The shift towards cloud-based CTMS platforms is accelerating due to their scalability, cost-efficiency, and ability to facilitate real-time data access and collaboration, which is particularly attractive to both large and small organizations managing complex, multi-site trials.
Technological Advancements and Integration
Integration of CTMS with AI, machine learning, big data analytics, and blockchain is enhancing trial efficiency, automating data analysis, and improving decision-making, which encourages broader adoption of advanced CTMS solutions across the region.
Growth in Decentralized and Virtual Clinical Trials
The increasing prevalence of decentralized and virtual clinical trials, especially post-pandemic, is boosting demand for CTMS platforms that support remote monitoring, virtual visits, and real-time data collection, enabling more patient-centric and efficient trial models.
Expansion of Clinical Trials and Complexity
The growing number and complexity of clinical trials, including multi-center and larger-scale studies, require sophisticated CTMS solutions to manage patient enrollment, regulatory compliance, and data integration, driving market growth as organizations seek to streamline operations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Europe CTMS Market in 2023 and 2032?
What factors are driving the growth of the Europe CTMS Market?
What role do cloud-based CTMS solutions play in the market growth?
Who are the key players in the Europe CTMS Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Delivery
- 1.2.1 Web-based (On-demand)
- 1.2.2 Licensed Enterprise (On-premises)
- 1.2.3 Cloud-based (SaaS)
- 1.3 By End User
- 1.3.1 Large Pharma-biotech Companies
- 1.3.2 CROs
- 1.3.3 Medical Device Manufacturers
- 1.3.4 Small & Mid-sized Pharma-biotech Companies
- 1.3.5 Other End Users
- 1.4 By Deployment
- 1.4.1 Enterprise-wide CTMS
- 1.4.2 On-Site CTMS
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 326.07 million → 2032: USD 795.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Clinical Trial Management System (CTMS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Clinical Trial Management System (CTMS) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Clinical Trial Management System (CTMS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Clinical Trial Management System (CTMS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Clinical Trial Management System (CTMS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Clinical Trial Management System (CTMS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Clinical Trial Management System (CTMS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Clinical Trial Management System (CTMS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 326.07 million → 2032: USD 795.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Clinical Trial Management System (CTMS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Delivery - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Web-based (On-demand)
- 12.3.7.2 Licensed Enterprise (On-premises)
- 12.3.7.3 Cloud-based (SaaS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Large Pharma-biotech Companies
- 12.4.7.2 CROs
- 12.4.7.3 Medical Device Manufacturers
- 12.4.7.4 Small & Mid-sized Pharma-biotech Companies
- 12.4.7.5 Other End Users
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Deployment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Enterprise-wide CTMS
- 12.5.7.2 On-Site CTMS
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Clinical Trial Management System (CTMS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Clinical Trial Management System (CTMS) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Clinical Trial Management System (CTMS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Clinical Trial Management System (CTMS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Veeva Systems
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medidata Solutions
- 18.4 Oracle Corporation
- 18.5 ICON plc
- 18.6 Forte Research Systems
- 18.7 Bio-Optronics
- 18.8 DATATRAK International, Inc.
- 18.9 Merge Healthcare Incorporated
- 18.10 DSG Inc.
- 18.11 ArisEurope
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

