
Market Overview
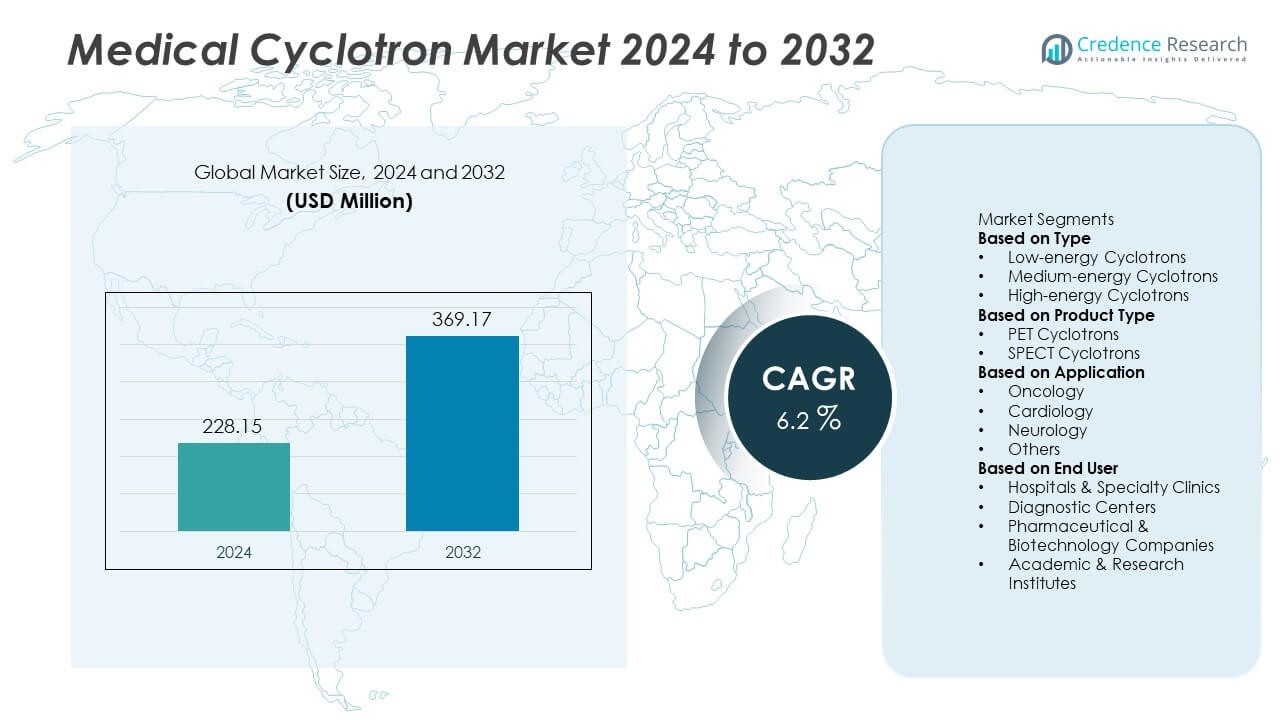
The Medical Cyclotron market was valued at USD 228.15 million in 2024. It is projected to reach USD 369.17 million by 2032, registering a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Cyclotron Market Size 2024 | USD 228.15 Million |
| Medical Cyclotron Market, CAGR | 6.2% |
| Medical Cyclotron Market Size 2032 | USD 369.17 Million |
The Medical Cyclotron market is shaped by key companies such as IBA Radiopharma Solutions, Siemens Healthineers, GE HealthCare, Sumitomo Heavy Industries, Advanced Cyclotron Systems, Best Cyclotron Systems, PMB-Alcen, TRIUMF Innovations, Ion Beam Applications, and Varian Medical Systems, all competing through technology improvements, compact system designs, and enhanced isotope production capabilities. North America leads the market with a 38% share, driven by strong nuclear medicine infrastructure, radiopharmaceutical production networks, and high PET-CT imaging usage. Europe follows with a 32% share, supported by established radiopharmacy hubs and rising theranostic adoption, while Asia-Pacific holds a 22% share and shows the fastest growth due to expanding cancer diagnostics and government investment in nuclear medicine.
Market Insights
- The Medical Cyclotron market was valued at USD 228.15 million in 2024 and is projected to reach USD 369.17 million by 2032, registering a CAGR of 6.2% during the forecast period.
- Growing demand for PET and SPECT imaging in oncology drives adoption, with oncology applications holding a 62% share as hospitals and radiopharmacies expand radiotracer production for cancer diagnostics and treatment monitoring.
- Technological advancements such as compact, self-shielded cyclotrons and automated isotope handling support higher efficiency and broaden installation across hospital-based radiopharmacies and decentralized radiopharmaceutical manufacturing models.
- Competitive landscape remains strong with leading players focusing on advanced target systems, higher yield efficiency, and partnerships for theranostics expansion, while high capital costs and the need for specialized infrastructure continue to restrain adoption among mid-sized healthcare facilities.
- North America leads with a 38% share, followed by Europe at 32% and Asia-Pacific at 22%, supported by investments in nuclear medicine and radiopharmaceutical production, while low-energy cyclotrons dominate by type with a 46% share.
Market Segmentation Analysis:
By Type:
Low-energy cyclotrons hold a leading 46% share of the Medical Cyclotron market. These systems are widely preferred due to lower operational costs, compact design, and suitability for producing key PET radioisotopes for routine imaging. Medium-energy cyclotrons follow with rising adoption in research facilities and advanced radiopharmaceutical production. High-energy cyclotrons account for a smaller share due to higher installation and maintenance requirements. The dominance of low-energy units is driven by growing demand for PET diagnostics, increasing cancer screening procedures, and rapid expansion of nuclear medicine centers in both developed and emerging healthcare markets.
- For instance, IBA’s Cyclone KIUBE system supports dual-beam extraction and delivers proton energy up to 18MeV, enabling production of Fluorine-18 at a capacity of 7000mCi per batch.
By Product Type:
PET cyclotrons dominate the market with a 71% share, supported by increasing use of PET imaging for oncology, neurology, and cardiology diagnostics. Their ability to produce short-lived isotopes such as Fluorine-18 drives extensive usage across hospital radiopharmacies and commercial isotope suppliers. SPECT cyclotrons maintain demand in specific cardiology and organ-function imaging, yet PET systems outperform in imaging accuracy and clinical adoption. Growth in PET radiopharmaceutical pipelines, emphasis on early disease detection, and rising installations of PET-CT and PET-MRI scanners continue to strengthen the dominance of PET cyclotrons across global nuclear medicine applications.
- For instance, GE HealthCare's PETtrace 890 supports 160 µA (microampere) beam current, enabling reliable Fluorine-18 production for continuous radiotracer supply across high-volume imaging centers.
By Application:
Oncology represents the dominant segment with a 62% share of the Medical Cyclotron market. The strong demand is linked to the increasing clinical reliance on PET-based cancer detection, treatment monitoring, and therapy planning. Cardiology and neurology imaging also expand steadily as precision diagnostics gain adoption in chronic disease management. Growing cancer incidence, the shift toward personalized treatment, and expanding radiotracer development pipelines accelerate cyclotron installations in hospital-based radiopharmacies. The segment’s growth further strengthens as healthcare systems invest in advanced radiopharmaceutical production to improve diagnostic accuracy and reduce dependence on imported isotopes.
Key Growth Driver:
Rising Demand for PET and SPECT Diagnostic Procedures
Growing use of PET and SPECT imaging in oncology, cardiology, and neurology supports strong Medical Cyclotron market expansion. Cyclotrons enable reliable production of short-lived isotopes such as Fluorine-18 and Carbon-11, which play a key role in early disease detection and treatment planning. Rising cancer prevalence, improved access to nuclear medicine, and favorable reimbursement policies further strengthen adoption. Hospitals and diagnostic networks continue investing in advanced radiopharmaceutical capabilities to improve diagnostic accuracy. This increasing reliance on molecular imaging drives new cyclotron installations across developed and emerging healthcare markets.
- For instance, Siemens Healthineers, through its PETNET network, operates over 50 radiopharmacies worldwide, ensuring daily distribution of Fluorine-18 radiotracers to hospital imaging departments.
Expansion of Radiopharmaceutical Manufacturing Facilities
Growing radiopharmaceutical development and commercial isotope supply needs encourage cyclotron deployment among private radiopharmacies and hospital-based production units. Companies are expanding centralized and decentralized manufacturing models to ensure stable availability of short half-life isotopes. Government funding for nuclear medicine infrastructure and supportive regulatory frameworks enhance market expansion. Clinical research on next-generation PET tracers broadens usage beyond oncology, increasing adoption in cardiology and neurology. As clinical trials intensify, producers require scalable isotope production systems, positioning cyclotrons as essential components of radiopharmaceutical development and distribution networks.
- For instance, Advanced Cyclotron Systems Inc. (ACSI) supports decentralized manufacturing through its TR-19 and TR-24 cyclotrons, which provide 19 to 24MeV energy for multi-isotope production, enabling supply for Fluorine-18, Nitrogen-13, Carbon-11, and Zirconium-89 clinical research programs.
Technological Advancements and Compact Cyclotron Designs
Advances in cyclotron engineering enhance performance, automation, and radiation safety, enabling reduced shielding and faster installation timelines. Compact, self-shielded cyclotrons support integration within hospitals and regional imaging centers without extensive construction requirements. Improved production control, higher isotope yield, and simplified maintenance strengthen operational efficiency. These advancements lower lifecycle costs and increase accessibility for mid-sized care providers. As nuclear medicine volumes grow, technologically advanced cyclotrons remain essential for continuous isotope supply and streamlined radiopharmaceutical workflows.
Key Trend & Opportunity:
Growing Adoption of Theranostics and Targeted Radiotherapy
Theranostics is reshaping clinical nuclear medicine by combining diagnostic imaging and targeted radionuclide therapy for personalized cancer treatment. Cyclotrons enable production of therapeutic and diagnostic isotopes used in prostate, thyroid, and neuroendocrine tumor management. Increasing adoption of PSMA-targeted and other molecular radiopharmaceuticals creates demand for flexible, hospital-linked isotope production. Partnerships between treatment centers, research institutes, and pharmaceutical companies support broader commercialization. This integration of imaging and therapy represents a major growth opportunity for cyclotron manufacturers and radiopharmacy solution providers.
- For instance, Telix Pharmaceuticals utilizes cyclotron-produced Gallium-68 tracers for PSMA theranostic programs, supporting clinical studies involving hundreds of enrolled patients across oncology sites.
Decentralized and Hospital-Based Isotope Production
Decentralized production models allow hospitals and regional radiopharmacies to generate isotopes on-site, reducing reliance on external suppliers and improving availability for time-critical PET imaging. This approach reduces transport risks, regulatory complexity, and isotope decay during transit. Growth in regional distribution hubs and mobile radiotracer services supports wider adoption. Emerging markets prioritize localized isotope access to strengthen diagnostic capacity. Decentralized cyclotron installations create promising opportunities for manufacturers, service providers, and integrated radiopharmacy operators.
- For instance, Eckert & Ziegler operates regional radiopharmacies equipped with Gallium-68 generators, which are a low-cost, easily transportable alternative to cyclotrons for producing Ga-68 on-site, to meet diagnostic requirements for neuroendocrine tumors.
Key Challenge:
High Capital Costs and Complex Infrastructure Requirements
Significant capital investment remains a major barrier, especially for smaller hospitals and diagnostic centers. Cyclotron deployment requires specialized radiation shielding, advanced ventilation, secure isotope handling systems, and trained personnel, increasing total cost of ownership. Lower imaging volumes and limited nuclear medicine budgets restrict adoption in cost-sensitive regions. Vendors must provide compact, cost-efficient systems, leasing models, and managed radiopharmacy services to mitigate purchasing constraints. These financial challenges slow market penetration and limit adoption among mid-scale healthcare operators.
Regulatory Compliance and Radioactive Material Handling
Strict regulatory oversight governs licensing, isotope production, radiation protection, and waste management, adding operational complexity. Healthcare facilities must maintain rigorous safety standards, documentation, and reporting, requiring specialized staff including nuclear pharmacists and radiation safety officers. Workforce shortages delay new cyclotron approvals and limit expansion in several countries. Non-compliance risks disrupt isotope supply and can impact patient care. Harmonized regulatory guidelines, workforce training programs, and digital compliance systems are essential to support safe and scalable cyclotron adoption.
Regional Analysis
North America
North America holds a leading 38% share of the Medical Cyclotron market, driven by strong nuclear medicine infrastructure and high PET-CT adoption rates. The United States leads installations due to expanding radiopharmaceutical production, favorable reimbursement policies, and strong investment in oncology diagnostics. Canada supports growth with increasing cyclotron deployment in hospital radiopharmacies to reduce reliance on imported isotopes. Academic research, clinical trials on novel tracers, and rising cancer screening programs continue to expand regional demand. Strong collaboration between imaging centers and pharmaceutical developers reinforces North America’s position in advancing molecular imaging and theranostic applications.
Europe
Europe accounts for a 32% share of the Medical Cyclotron market, supported by established radiopharmacy networks and strong regulatory backing for nuclear medicine. Germany, France, Italy, and the United Kingdom lead due to robust PET imaging usage and public healthcare investment. Cyclotron deployment increases as hospitals move toward localized isotope production for oncology and neurology diagnostics. EU emphasis on theranostics and targeted radiotherapy further boosts demand for clinical isotope manufacturing. Joint research programs, cross-border isotope distribution, and growing installation of self-shielded cyclotrons accelerate adoption across regional medical and research institutions.
Asia-Pacific
Asia-Pacific captures a 22% share and represents the fastest-growing region, driven by rising cancer incidence, expanding diagnostic imaging capacity, and government support for nuclear medicine infrastructure. China and India increase hospital-based cyclotron installations to expand PET-CT access, reduce isotope shortages, and support new radiopharmaceutical manufacturing. Japan and South Korea advance medical cyclotron technology through research and commercial isotope production. Growing investment from private imaging chains and pharmaceutical companies strengthens market momentum. The region’s shift toward localized radiotracer supply and broader adoption of precision oncology continues to create significant long-term growth opportunities.
Latin America
Latin America holds a 5% share of the Medical Cyclotron market, with growth supported by expanding PET imaging access and public healthcare upgrades. Brazil and Mexico lead installations due to increasing adoption in oncology diagnosis and efforts to reduce dependency on imported isotopes. Limited availability of skilled personnel and higher capital costs remain challenges, yet government and private sector partnerships improve infrastructure. Emerging radiopharmacy hubs, combined with training programs in nuclear medicine, are driving gradual regional adoption. Enhanced cancer care programs and rising patient awareness support increased cyclotron demand across key cities.
Middle East & Africa
The Middle East & Africa region accounts for a 3% share, driven by gradual nuclear medicine adoption and rising investment in advanced cancer diagnostics. Gulf countries, including the United Arab Emirates and Saudi Arabia, expand cyclotron and PET-CT installations through healthcare modernization initiatives. Africa shows slower growth due to limited isotope production facilities and cost constraints, although South Africa supports the region with established radiopharmacy capabilities. Partnerships with global radiopharmaceutical companies and new cancer treatment centers improve future prospects. Training programs and government support are expected to strengthen clinical cyclotron deployment over time.
Market Segmentations:
By Type
- Low-energy Cyclotrons
- Medium-energy Cyclotrons
- High-energy Cyclotrons
By Product Type
- PET Cyclotrons
- SPECT Cyclotrons
By Application
- Oncology
- Cardiology
- Neurology
- Others
By End User
- Hospitals & Specialty Clinics
- Diagnostic Centers
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Medical Cyclotron market features strong competition among leading companies, including IBA Radiopharma Solutions, Siemens Healthineers, GE HealthCare, Sumitomo Heavy Industries, Advanced Cyclotron Systems, Best Cyclotron Systems, PMB-Alcen, TRIUMF Innovations, Ion Beam Applications, and Varian Medical Systems. These players compete on technology innovation, energy efficiency, production capacity, and system integration for PET and SPECT isotope manufacturing. Companies focus on compact, self-shielded designs that enable hospital-based installations and reduce radiation infrastructure requirements. Strategic partnerships with radiopharmacies, pharmaceutical companies, and diagnostic networks strengthen supplier positions in key growth markets. Several manufacturers invest in automation, remote monitoring, and advanced target systems to increase isotope yield and operational safety. After-sales service, maintenance contracts, and regulatory support remain critical differentiators as healthcare providers prioritize reliable isotope supply for oncology, neurology, and cardiology diagnostics. Continuous research on new radiotracers and rising demand for theranostic applications are expected to influence future competitive strategies.
Key Player Analysis
- IBA Radiopharma Solutions
- Siemens Healthineers
- GE HealthCare
- Sumitomo Heavy Industries, Ltd.
- Advanced Cyclotron Systems Inc.
- Best Cyclotron Systems, Inc.
- PMB-Alcen
- TRIUMF Innovations
- Ion Beam Applications S.A. (IBA)
- Varian Medical Systems
Recent Developments
- In May 2025, Ion Beam Applications S.A. (IBA) signed a contract with PET Pharm Bio in Taiwan to install its high-energy “Cyclone IKON” cyclotron for PET and SPECT isotope production, enabling production of isotopes such as Iodine-123 and Zirconium-89.
- In February 2025, IBA also entered a Memorandum of Understanding with Framatome to develop a global network of alpha-emitting cyclotrons for production of the radioisotope Astatine-211, aimed at supporting targeted alpha therapies for oncology.
- In December 2024, Siemens Healthineers completed the acquisition of Advanced Accelerator Applications Molecular Imaging from Novartis, adding a European manufacturing and distribution network of PET radiopharmaceuticals to its portfolio.
Report Coverage
The research report offers an in-depth analysis based on Type, Product Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see wider adoption of compact and self-shielded cyclotrons in hospital radiopharmacies.
- Demand for isotopes used in oncology imaging and therapy will continue to grow.
- Theranostics will drive investments in new radiopharmaceutical production capabilities.
- Automation and digital monitoring will improve isotope yield and operational safety.
- More decentralized and regional production hubs will reduce dependence on imported isotopes.
- Partnerships between cyclotron makers and radiopharmaceutical companies will expand isotope portfolios.
- Skilled workforce development in nuclear medicine will become a priority for healthcare systems.
- Regulatory frameworks will evolve to support faster cyclotron approvals and safer operations.
- Advancements in PET tracer research will increase applications beyond oncology into cardiology and neurology.
- Growing nuclear medicine infrastructure in Asia-Pacific and Latin America will create new market growth opportunities.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Medical Cyclotron market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Cyclotron market projected to grow between 2025 and 2032?
Which Medical Cyclotron market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medical Cyclotron market?
Who are the leading companies in the Medical Cyclotron market?
Which region commanded the largest share of the Medical Cyclotron market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 228.15 million → 2032: USD 369.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Cyclotron Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Cyclotron Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Cyclotron Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Cyclotron Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Cyclotron Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Cyclotron Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Cyclotron Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Cyclotron Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 228.15 million → 2032: USD 369.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Cyclotron Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Cyclotron Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Medical Cyclotron Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Medical Cyclotron Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

