
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Electrodeposited Copper Foils Market Size 2024 | USD 3394.07 million |
| Europe Electrodeposited Copper Foils Market, CAGR | 10.85% |
| Europe Electrodeposited Copper Foils Market Size 2032 | USD 7735.32 million |
Market Overview:
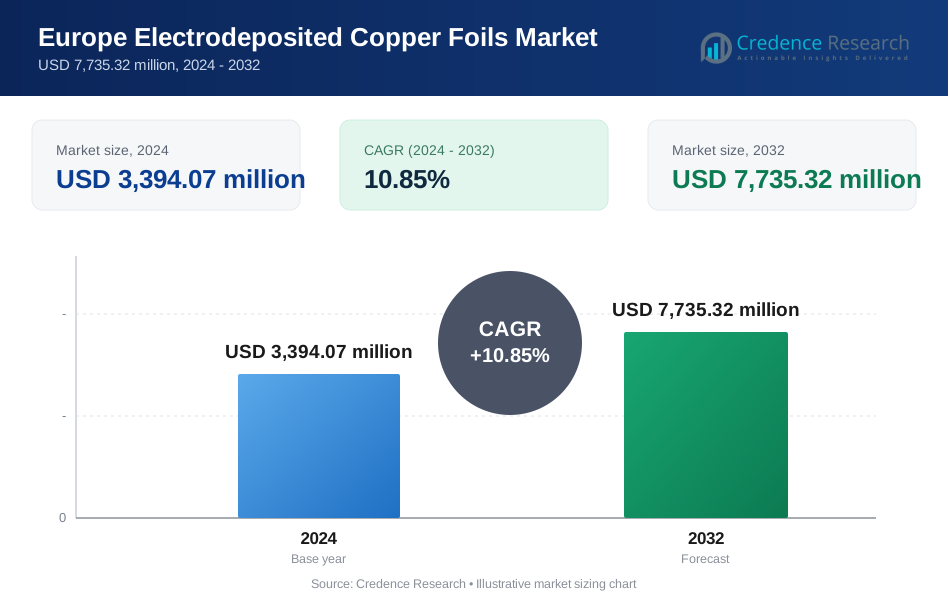
The Europe Electrodeposited Copper Foils Market is projected to grow from USD 3394.07 million in 2024 to an estimated USD 7735.32 million by 2032, with a compound annual growth rate (CAGR) of 10.85% from 2024 to 2032.
The growth of the Europe electrodeposited copper foils market is driven by several key factors, including the rapid expansion of the electronics industry, increasing adoption of electric vehicles (EVs), advancements in renewable energy, and continuous technological innovations. The demand for high-performance printed circuit boards (PCBs) in consumer electronics, such as smartphones, laptops, and wearable devices, is a significant driver, with electrodeposited copper foils being critical for their superior electrical conductivity and durability. Additionally, Europe's strong push towards reducing carbon emissions has led to a surge in EV production, further amplifying the need for efficient lithium-ion batteries where copper foils play an essential role. The region’s commitment to sustainable energy solutions, including solar and wind power, is also contributing to the growing demand for reliable energy storage systems utilizing electrodeposited copper foils. Technological advancements, particularly in flexible electronics and the miniaturization of components, are further expanding the application scope of these foils, enhancing market growth.
Regionally, Germany is leading the Europe electrodeposited copper foils market, projected to register the highest growth rate driven by its advanced automotive sector and strong emphasis on renewable energy initiatives. Germany's commitment to expanding electric vehicle production and sustainable technologies is significantly contributing to market expansion. Other major contributors include France, the United Kingdom, and Italy, where increased investments in renewable energy projects and advancements in electronics manufacturing are driving demand. These regional trends, coupled with a strategic focus on sustainability and technological development, are shaping the market’s growth trajectory across Europe.
Market Insights:
- The Europe Electrodeposited Copper Foils Market is projected to grow from USD 3,394.07 million in 2024 to USD 7,735.32 million by 2032, at a CAGR of 10.85%, driven by expanding applications across industries.
- The increasing demand for high-performance printed circuit boards (PCBs) in consumer electronics, such as smartphones and wearables, is a significant driver of market growth.
- Europe's transition towards sustainable transportation is fueling the demand for electrodeposited copper foils, essential for enhancing the efficiency of lithium-ion batteries in electric vehicles (EVs).
- Growing investments in renewable energy, including solar and wind power projects, are elevating the demand for copper foils used in efficient and durable energy storage systems.
- Continuous advancements in flexible electronics and the miniaturization of electronic components are expanding the application scope of copper foils, driving innovation in the market.
- High production costs and raw material price volatility, coupled with stringent environmental regulations, present challenges that companies must address to ensure long-term profitability.
- Regionally, Germany leads the European market, with strong contributions from France, the UK, and Italy, all driven by advancements in EV production, renewable energy projects, and electronics manufacturing.
Market Drivers:
Expansion of the Electronics Industry
The rapid expansion of the electronics industry in Europe is one of the primary drivers of the electrodeposited copper foils market. As consumer demand for advanced electronic devices such as smartphones, tablets, laptops, and wearable gadgets increases, the need for high-performance printed circuit boards (PCBs) has grown significantly. Electrodeposited copper foils play a critical role in PCB manufacturing due to their superior electrical conductivity, thermal stability, and flexibility. The trend toward more compact, efficient, and powerful devices is pushing manufacturers to source reliable and high-quality copper foils to meet evolving technological demands. Additionally, Europe’s emphasis on smart technologies and the rise of Industry 4.0 have fueled innovation in electronic components, further boosting the demand for copper foils. As the electronics sector continues to advance, it is expected to be a key driver of sustained growth in the electrodeposited copper foils market.
Increasing Adoption of Electric Vehicles (EVs)
The transition towards sustainable transportation solutions in Europe is significantly influencing the electrodeposited copper foils market. As countries across the region strive to meet carbon neutrality targets, the adoption of electric vehicles (EVs) is accelerating. For example, in 2025, approximately 873,000 electric cars are expected to be newly registered in Germany alone, marking a 53% increase compared to 2024. Lithium-ion batteries, which are integral to EVs, rely heavily on high-quality electrodeposited copper foils to ensure efficient conductivity and energy storage. The growing production of EVs and the expansion of battery manufacturing facilities are propelling the demand for these copper foils. Furthermore, government incentives promoting EV adoption, along with investments in charging infrastructure, are fostering market growth. Manufacturers are focusing on enhancing copper foil technologies to improve battery efficiency, longevity, and safety. This sector’s rapid growth is expected to continue as Europe reinforces its commitment to reducing greenhouse gas emissions and promoting sustainable transportation solutions.
Advancements in Renewable Energy Solutions
Europe’s strong emphasis on renewable energy sources is another critical driver of the electrodeposited copper foils market. The shift towards sustainable energy solutions, including solar and wind power, has increased the demand for efficient energy storage systems. For instance, Europe is expected to install 187 GW of new wind power capacity over 2025-2030. Copper foils are integral in the production of batteries and other components that store and transmit energy effectively. The increasing deployment of renewable energy projects across Europe, supported by government policies and investments, is creating consistent demand for electrodeposited copper foils. Moreover, the need for reliable and long-lasting energy storage systems in large-scale renewable projects is driving innovation in copper foil technology. As the region continues to prioritize clean energy and green infrastructure, the demand for high-performance copper foils is expected to rise, thereby contributing to long-term market growth.
Technological Innovations and Product Advancements
Continuous technological advancements and product innovations are shaping the electrodeposited copper foils market in Europe. The trend towards the miniaturization of electronic components and the development of flexible electronics is creating new opportunities for copper foil applications. Manufacturers are investing in research and development to produce thinner, more durable, and higher-performing copper foils that meet the specific requirements of evolving technologies. Advanced deposition techniques and improvements in material properties are enhancing the quality and efficiency of electrodeposited copper foils. Moreover, the growing focus on sustainability is pushing companies to innovate eco-friendly production processes that minimize environmental impact while maintaining product quality. As technology continues to advance across multiple industries, the demand for innovative and high-performance electrodeposited copper foils will remain strong, driving consistent market growth.
Market Trends:
Growing Demand for Ultra-Thin Copper Foils
A notable trend in the Europe electrodeposited copper foils market is the increasing demand for ultra-thin copper foils, driven by the advancements in electronic devices and battery technologies. Modern electronic components, particularly in sectors like flexible electronics and wearables, require thinner materials to enhance device performance and efficiency. Ultra-thin copper foils enable the production of compact, lightweight, and high-performance devices without compromising electrical conductivity. For instance, Solus Advanced Materials has established a significant presence in Europe by producing copper foils for electric vehicle batteries, highlighting the growing demand for such materials in advanced applications. Additionally, the development of smaller and more efficient lithium-ion batteries is further accelerating the need for ultra-thin foils. Manufacturers are investing in advanced manufacturing techniques to meet the demand for high-precision, ultra-thin foils that cater to these evolving industry requirements.
Emphasis on Sustainable Manufacturing Processes
Sustainability has emerged as a critical focus area in the Europe electrodeposited copper foils market. With increasing regulatory pressure and consumer demand for eco-friendly products, manufacturers are prioritizing the development of sustainable production processes. This includes reducing energy consumption, minimizing waste, and adopting recycling initiatives for copper materials. Companies are also investing in cleaner technologies to align with Europe’s strict environmental standards and carbon reduction goals. The adoption of sustainable practices not only enhances corporate responsibility but also provides a competitive edge in the market. Moreover, partnerships and collaborations with green technology firms are enabling companies to innovate and introduce environmentally friendly solutions. As the emphasis on sustainability intensifies, manufacturers focusing on eco-conscious production methods are likely to strengthen their market presence.
Rising Investments in Research and Development
Investments in research and development (R&D) are becoming a key trend in the Europe electrodeposited copper foils market. To stay competitive and meet the growing demand for advanced materials, companies are dedicating resources to enhance product quality and performance. R&D efforts are focused on developing copper foils with improved strength, conductivity, and corrosion resistance, catering to the requirements of high-performance applications. Innovations in deposition techniques and surface treatment processes are contributing to the creation of superior copper foils that meet industry standards. Additionally, companies are exploring alternative materials and composite solutions to diversify their product portfolios. For instance, Circuit Foil has launched a significant research partnership with the Luxembourg Institute of Science and Technology to push the boundaries of copper foil production for emerging technologies. This strong focus on R&D is enabling manufacturers to address technological challenges, improve product efficiency, and tap into emerging market opportunities across sectors such as electronics, automotive, and energy storage.
Increased Focus on Regional Supply Chain Optimization
Another emerging trend in the Europe electrodeposited copper foils market is the increased focus on optimizing regional supply chains. The disruptions caused by global events have highlighted the importance of having a resilient and localized supply chain. European manufacturers are seeking to reduce dependency on international suppliers by enhancing local production capabilities and strengthening partnerships within the region. This approach not only minimizes supply chain risks but also shortens lead times and improves product availability. Additionally, regional optimization is allowing companies to better align with European regulations and consumer demands. The move towards localized sourcing and production is expected to provide long-term benefits, ensuring stability and competitiveness in the electrodeposited copper foils market across Europe.
Market Challenges Analysis:
High Production Costs and Price Volatility
One of the primary restraints affecting the Europe electrodeposited copper foils market is the high cost of production. Manufacturing high-quality copper foils involves complex processes that require advanced technology, precision, and significant energy consumption, all contributing to increased operational costs. Additionally, the volatility in raw material prices, particularly copper, poses a significant challenge. Copper prices are influenced by global supply-demand dynamics, geopolitical factors, and trade regulations. These fluctuations lead to unpredictability in production costs, affecting profit margins and complicating pricing strategies for manufacturers. Companies need to adopt efficient production techniques and establish long-term supplier agreements to mitigate the risks associated with cost volatility.
Stringent Environmental Regulations
The European market is subject to stringent environmental regulations, which pose challenges for copper foil manufacturers. The production process involves the use of chemicals and energy-intensive methods that generate waste and emissions. Regulatory bodies enforce strict guidelines related to waste disposal, emission control, and energy consumption, increasing the compliance burden on manufacturers. For example, new copper foil manufacturing facilities, such as the one planned by Lotte Energy Materials in Spain, face significant environmental scrutiny and must implement comprehensive environmental management systems to minimize potential impacts. Additionally, there is growing pressure to adopt sustainable practices, such as reducing carbon footprints and incorporating eco-friendly technologies. While these practices promote long-term sustainability, they require substantial upfront investments, which can be a barrier for smaller companies. Failure to meet environmental standards can lead to regulatory penalties and impact brand reputation.
Intense Market Competition and Technological Barriers
The electrodeposited copper foils market in Europe is characterized by intense competition, with numerous regional and global players vying for market share. This competition exerts pressure on pricing and compels manufacturers to continuously innovate. Smaller players often face difficulties in keeping up with rapid technological advancements, limiting their ability to scale production or meet evolving industry standards. Moreover, technological barriers such as maintaining consistency in ultra-thin foils and ensuring high-performance standards can challenge even established manufacturers. Continuous investment in research and development is necessary to overcome these barriers, which can strain financial resources and operational capabilities.
Market Opportunities:
The Europe electrodeposited copper foils market presents substantial growth opportunities driven by the increasing demand for advanced electronic devices and the expanding electric vehicle (EV) industry. As Europe continues to position itself as a leader in technological innovation, the demand for high-performance printed circuit boards (PCBs) in sectors such as consumer electronics, telecommunications, and automotive systems is steadily rising. Electrodeposited copper foils, known for their superior conductivity and durability, are integral in manufacturing these PCBs. Additionally, the emergence of flexible electronics and miniaturized devices is creating new avenues for copper foil applications. Manufacturers that invest in advanced production techniques and develop ultra-thin, high-performance foils will be well-positioned to capture emerging market opportunities. Furthermore, the shift towards 5G technology and smart devices is expected to drive long-term demand, offering manufacturers opportunities to innovate and expand their product offerings.
The growing emphasis on sustainability and renewable energy across Europe also presents significant market prospects. With increased investments in solar and wind energy infrastructure, the demand for efficient energy storage systems is accelerating, and electrodeposited copper foils play a vital role in these systems. Moreover, the region's commitment to reducing carbon emissions is fostering rapid adoption of EVs, thereby increasing the demand for high-quality copper foils used in lithium-ion batteries. Manufacturers that align their strategies with these sustainability goals and invest in eco-friendly production practices can tap into this expanding market segment. Additionally, partnerships with energy storage and EV battery producers could further strengthen market positioning and unlock long-term growth opportunities across the European landscape.
Market Segmentation Analysis:
The Europe electrodeposited copper foils market is segmented based on material type, process, and end-use industry, each contributing to the market's dynamics and growth trajectory.
By Material Type Segment The market is segmented into ferrous, non-ferrous, and others. The non-ferrous segment dominates the market, driven by the extensive use of copper foils in applications requiring high electrical conductivity and corrosion resistance. Non-ferrous materials, especially copper, are extensively used in electronics, automotive batteries, and renewable energy systems. The ferrous segment, although smaller, is utilized in applications demanding high strength and durability. The ‘others’ segment includes specialty alloys catering to niche industrial needs.
By Process Segment In terms of process, the market is divided into press-and-sinter, metal injection molding, and additive manufacturing. The press-and-sinter process holds a significant market share due to its cost-effectiveness and suitability for mass production. Metal injection molding is gaining traction for producing complex and precision-based components, particularly in the electronics and automotive sectors. Additive manufacturing, while still emerging, offers opportunities for customized production and is expected to witness gradual growth in advanced industrial applications.
By End-Use Industry Segment The market is diversified across automotive, aerospace, healthcare, electrical & electronics, and industrial sectors. The electrical & electronics segment leads, driven by the high demand for copper foils in printed circuit boards and battery components. The automotive segment is rapidly expanding due to the growing production of electric vehicles. Aerospace and healthcare industries contribute to the demand for precision-engineered copper components, while the industrial sector utilizes copper foils for various manufacturing processes and energy storage systems.
Segmentation:
By Material Type Segment
- Ferrous
- Non-Ferrous
- Others
By Process Segment
- Press-and-Sinter
- Metal Injection Molding
- Additive Manufacturing
By End-Use Industry Segment
- Automotive
- Aerospace
- Healthcare
- Electrical & Electronics
- Industrial
Regional Analysis:
The Europe electrodeposited copper foils market is a significant segment of the global copper foil industry, reflecting the region's robust industrial base and technological advancements. In 2023, Europe accounted for approximately 14.1% of the global copper foil market revenue, underscoring its substantial contribution to the industry.
Germany
Germany stands as a pivotal player in Europe's electrodeposited copper foils market, driven by its advanced automotive and electronics industries. The country's strong emphasis on electric vehicle (EV) production has escalated the demand for high-quality copper foils used in lithium-ion batteries. Additionally, Germany's leadership in industrial automation and electronics manufacturing further bolsters the consumption of electrodeposited copper foils. This strategic focus positions Germany as a key contributor to the regional market's growth.
France
France contributes significantly to the electrodeposited copper foils market, propelled by its expanding renewable energy sector and electronics industry. The country's commitment to sustainable energy solutions, including solar and wind power projects, has increased the need for efficient energy storage systems that utilize copper foils. Furthermore, France's growing electronics manufacturing sector enhances the demand for high-quality copper foils, reinforcing its role in the regional market.
United Kingdom
The United Kingdom plays a notable role in the electrodeposited copper foils market, supported by its advancements in technology and renewable energy initiatives. The UK's focus on smart technologies and the development of flexible electronics has created opportunities for copper foil applications. Additionally, the country's investments in renewable energy infrastructure, such as offshore wind farms, have driven the demand for reliable energy storage solutions, further stimulating the copper foils market.
Italy
Italy's electrodeposited copper foils market benefits from its strong industrial base and growing emphasis on renewable energy. The country's manufacturing sector, particularly in electronics and automotive components, relies on high-quality copper foils. Moreover, Italy's initiatives to expand solar energy installations have increased the demand for efficient energy storage systems, contributing to the growth of the copper foils market.
Rest of Europe
Other European countries, including Spain, the Netherlands, and Belgium, also contribute to the electrodeposited copper foils market. These nations are investing in renewable energy projects and enhancing their electronics manufacturing capabilities, thereby increasing the demand for copper foils. Collectively, these countries support the overall growth and diversification of the electrodeposited copper foils market across Europe.
Key Player Analysis:
- Höganäs AB
- GKN Powder Metallurgy European Operations
- Sandvik AB
- Miba AG
- Carpenter Technology Corporation European Division
- Rio Tinto European Operations
- Aubert & Duval
- CEAC Group
- BASF SE
- Plansee Group
Competitive Analysis:
The Europe electrodeposited copper foils market is characterized by intense competition, with the presence of both global and regional players striving to strengthen their market positions. Leading companies focus on enhancing product quality, investing in research and development, and adopting sustainable manufacturing practices to meet evolving industry demands. Innovation in product development, particularly the creation of ultra-thin and high-performance copper foils, is a key competitive factor. Additionally, companies are leveraging strategic partnerships and collaborations to expand their market reach and enhance production capabilities. The competitive landscape is further shaped by efforts to optimize supply chains, reduce production costs, and comply with stringent environmental regulations. Smaller players face challenges in keeping up with rapid technological advancements, while established companies continue to invest in advanced technologies to maintain their competitive edge. Overall, continuous innovation and strategic expansion remain crucial for companies to sustain their market presence in Europe.
Recent Developments:
- In August 2023, SK Nexilis, a South Korean copper foil maker, signed a significant deal with German battery manufacturer Varta A.G.to supply copper foil for Varta's first mass production of electric vehicle (EV) batteries. This partnership highlights the growing demand for high-quality copper foils in the EV sector. SK Nexilis is also in talks with Varta for a potential long-term supply agreement, reflecting the anticipated increase in demand for EV batteries.
Market Concentration & Characteristics:
The Europe electrodeposited copper foils market is moderately concentrated, with a mix of established global players and regional manufacturers. A few key companies dominate the market due to their advanced production capabilities, extensive distribution networks, and focus on technological innovation. The market is characterized by high entry barriers, including significant capital investments, strict regulatory compliance, and the need for advanced manufacturing technologies. Product differentiation is driven by factors such as foil thickness, conductivity, and customization for specific applications like electric vehicles, electronics, and renewable energy systems. Sustainability and eco-friendly production processes are becoming defining characteristics, as companies adapt to stringent European environmental regulations. Continuous investment in research and development is essential for manufacturers to remain competitive, meet evolving industry demands, and align with technological advancements. This competitive landscape underscores the need for strategic innovation and operational efficiency to succeed in the European market.
Report Coverage:
The research report offers an in-depth analysis based on material type, process, and end-use industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Europe electrodeposited copper foils market is expected to witness steady growth, driven by rising demand in electronics and electric vehicle industries.
- Increasing adoption of renewable energy systems will boost the need for high-performance copper foils in energy storage applications.
- Technological advancements, including the development of ultra-thin and flexible copper foils, will create new growth avenues.
- The expansion of electric vehicle manufacturing in key European countries will significantly enhance market demand.
- Growing investments in research and development will lead to innovative product solutions catering to advanced applications.
- Sustainable manufacturing practices will gain importance as companies adapt to stricter environmental regulations.
- Enhanced focus on localizing supply chains will improve production efficiency and reduce dependency on imports.
- Rising demand for miniaturized electronic components will drive the requirement for precision-engineered copper foils.
- Strategic collaborations and partnerships among manufacturers will strengthen market positioning and innovation capabilities.
- Expansion into emerging markets within Europe will offer new opportunities for market penetration and growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Electrodeposited Copper Foils Market
What factors are driving the growth of the Europe Electrodeposited Copper Foils Market?
What are some challenges faced by the Europe Electrodeposited Copper Foils Market?
Which country is leading the Europe Electrodeposited Copper Foils Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Electrodeposited Copper Foils Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Electrodeposited Copper Foils Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,394.07 million → 2032: USD 7,735.32 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Electrodeposited Copper Foils Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Electrodeposited Copper Foils Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Electrodeposited Copper Foils Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Electrodeposited Copper Foils Market Drivers
- 3.3 Europe Electrodeposited Copper Foils Market Restraints & Challenges
- 3.4 Europe Electrodeposited Copper Foils Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Electrodeposited Copper Foils Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Electrodeposited Copper Foils Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Electrodeposited Copper Foils category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Electrodeposited Copper Foils Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Electrodeposited Copper Foils Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Electrodeposited Copper Foils market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Electrodeposited Copper Foils Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Electrodeposited Copper Foils Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Electrodeposited Copper Foils Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Electrodeposited Copper Foils (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Electrodeposited Copper Foils Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Electrodeposited Copper Foils Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Electrodeposited Copper Foils Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Electrodeposited Copper Foils Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Electrodeposited Copper Foils Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Electrodeposited Copper Foils Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Electrodeposited Copper Foils Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Electrodeposited Copper Foils Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Electrodeposited Copper Foils Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
