
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Plastic Welding Equipment Market Size 2024 | USD 2,985.82 Million |
| Europe Plastic Welding Equipment Market, CAGR | 6.49% |
| Europe Plastic Welding Equipment Market Size 2032 | USD 4,938.76 Million |
Market Overview
Europe Plastic Welding Equipment Market size was valued at USD 2,985.82 million in 2024 and is anticipated to reach USD 4,938.76 million by 2032, at a CAGR of 6.49% during the forecast period (2024-2032).
The Europe plastic welding equipment market is driven by the growing demand for lightweight and durable plastic components across automotive, packaging, and construction industries. Stringent environmental regulations encouraging the use of recyclable materials further propel market growth, as plastic welding enables efficient and sustainable manufacturing processes. Technological advancements, such as automation and integration of precision control systems, enhance welding quality and operational efficiency, attracting investment from manufacturers. Additionally, the shift towards electric vehicles and the increasing adoption of high-performance plastics in various end-use applications amplify the need for advanced plastic joining technologies. Trends indicate a rising preference for non-contact welding techniques, including laser and ultrasonic welding, due to their precision and suitability for complex assemblies. Moreover, the expansion of industrial infrastructure and growing focus on energy-efficient production methods contribute to the sustained demand for innovative plastic welding solutions across Europe.
The geographical landscape of the Europe plastic welding equipment market is characterized by strong industrial presence across Western and Central Europe, with countries like Germany, the UK, France, and Italy leading in technological adoption and manufacturing output. These regions benefit from well-established automotive, electronics, and medical device sectors that consistently demand high-quality and efficient plastic welding solutions. Eastern and Northern European countries are also showing increased activity due to infrastructure development and industrial modernization. In terms of key players, the market features a mix of prominent international and regional manufacturers, including Leister Technologies AG, Herrmann Ultraschalltechnik GmbH & Co. KG, Frimo Group GmbH, and LPKF Laser & Electronics AG. These companies are at the forefront of innovation, offering advanced welding technologies such as ultrasonic, laser, and hot plate systems tailored to various industrial applications. Their strategic focus on automation, precision, and energy efficiency is shaping the competitive dynamics of the European market.
Market Insights
- The Europe plastic welding equipment market was valued at USD 2,985.82 million in 2024 and is projected to reach USD 4,938.76 million by 2032, growing at a CAGR of 6.49% during the forecast period.
- The global plastic welding equipment market was valued at USD 11,340.00 million in 2024 and is projected to reach USD 19,842.36 million by 2032, growing at a CAGR of 7.24% from 2024 to 2032.
- The market is driven by increasing demand for lightweight and durable plastic components in industries like automotive, packaging, and construction.
- Stringent environmental regulations and the shift towards sustainable manufacturing practices are promoting the adoption of recyclable and eco-friendly welding solutions.
- Advancements in automation and smart technologies, such as robotic systems and real-time monitoring, are driving operational efficiency and quality control.
- Laser and ultrasonic welding techniques are gaining traction due to their precision, speed, and minimal material waste.
- Key players in the market include Leister Technologies AG, Herrmann Ultraschalltechnik GmbH & Co. KG, and Frimo Group GmbH.
- The market faces challenges including high initial costs and material compatibility issues, which may hinder adoption for small to mid-sized manufacturers.
Report Scope
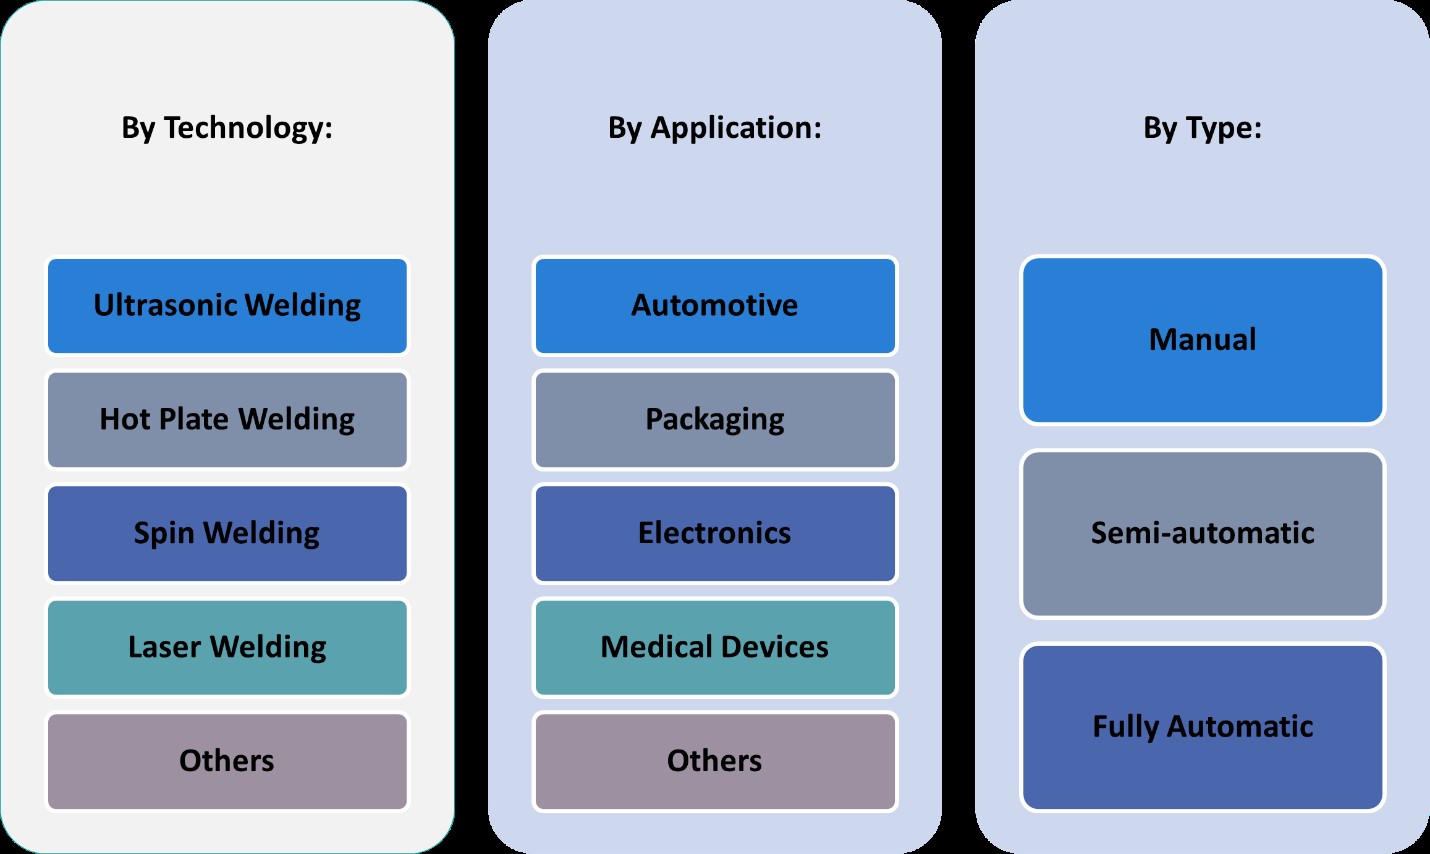
This report segments the Europe Plastic Welding Equipment Market as follows:
Market Drivers
Rising Demand Across Key End-Use Industries
The Europe plastic welding equipment market is significantly driven by rising demand across diverse end-use industries such as automotive, packaging, construction, and electronics. For instance, the European Welding Association highlights the increasing use of plastic welding technologies in automotive manufacturing to assemble lightweight components that improve fuel efficiency. In the automotive sector, the push for lightweight vehicles to improve fuel efficiency and reduce emissions has led manufacturers to increasingly adopt plastic components. Plastic welding equipment is essential for assembling these components reliably and cost-effectively. Similarly, the packaging industry relies on plastic welding for sealing and joining applications, especially with the rise in demand for flexible and durable packaging solutions. In the construction sector, plastic pipes, fittings, and membranes require strong and precise welding, further boosting equipment demand. The versatility and reliability of plastic welding processes make them indispensable across these rapidly evolving industries.
Supportive Environmental Regulations and Sustainability Goals
Stringent environmental regulations across Europe are accelerating the adoption of plastic welding technologies that support recycling and sustainable manufacturing practices. For instance, the European Commission's Plastics Strategy promotes the use of recyclable materials and production techniques that minimize waste. Plastic welding is a cleaner alternative to traditional bonding methods, offering leak-proof and durable joints without the use of solvents or adhesives. Moreover, equipment advancements enable the processing of recycled and biodegradable plastics, aligning with the region’s ambitious sustainability goals. This regulatory environment not only ensures compliance but also incentivizes manufacturers to invest in advanced welding solutions, fostering long-term market growth.
Technological Advancements and Automation Integration
The integration of automation and precision control technologies is a critical market driver, as it enhances the efficiency, quality, and consistency of plastic welding processes. The development of advanced welding systems-such as ultrasonic, laser, and hot plate welding-equipped with real-time monitoring, programmable settings, and robotic arms has revolutionized production lines across Europe. These technologies reduce operational errors, minimize human intervention, and improve repeatability, making them highly attractive for high-volume and precision-driven applications. Additionally, the trend toward Industry 4.0 and smart manufacturing is encouraging further adoption of digitally integrated plastic welding equipment. As manufacturers seek to enhance productivity while maintaining high-quality standards, demand for technologically advanced welding systems continues to surge.
Growth in Electric Vehicles and High-Performance Plastics
The rapid expansion of the electric vehicle (EV) market in Europe is creating substantial demand for plastic welding equipment. EVs utilize a wide range of plastic components for battery housings, connectors, interior panels, and lightweight structural elements, all of which require reliable and high-strength welding. Plastic welding supports the production of intricate and lightweight components critical for improving vehicle range and performance. Furthermore, the increasing use of high-performance plastics in aerospace, medical, and industrial applications necessitates advanced welding technologies capable of handling diverse material properties. This shift is driving manufacturers to invest in equipment that offers precision, material compatibility, and high throughput-key factors fueling the plastic welding equipment market across the region.
Market Trends
Adoption of Non-Contact and Precision Welding Technologies
A prominent trend shaping the Europe plastic welding equipment market is the growing adoption of non-contact welding technologies, particularly laser and ultrasonic welding. For instance, the European Welding Association highlights the increasing use of laser welding in automotive and medical device manufacturing due to its precision and cleanliness. Unlike traditional contact-based techniques, non-contact welding ensures minimal wear and maintenance, while delivering consistent results even with complex geometries. As manufacturers prioritize accuracy and durability, the shift toward these advanced methods is becoming increasingly evident across high-tech production facilities in Europe.
Integration of Automation and Smart Manufacturing
The rise of Industry 4.0 is driving the integration of automation, data analytics, and real-time monitoring in plastic welding equipment. For instance, the European Commission's Factories of the Future initiative promotes the adoption of smart systems equipped with sensors and programmable logic controllers (PLCs) to enhance production efficiency. Automation not only boosts production efficiency but also reduces human error and labor costs. Furthermore, intelligent systems enable predictive maintenance and quality assurance, which are critical for industries with stringent performance standards. This trend is reinforcing the transition toward more agile and data-driven manufacturing environments across the region.
Surge in Demand for Lightweight and Sustainable Materials
The ongoing push for sustainability and lightweight solutions, particularly in the automotive and packaging sectors, is influencing material choices and, consequently, welding technologies. The increasing use of recyclable and high-performance thermoplastics is prompting manufacturers to adapt welding equipment to accommodate new material properties and compositions. Plastic welding enables efficient joining of such materials without compromising strength or integrity, aligning with environmental and regulatory goals. As industries pursue greener alternatives and lightweight designs to reduce emissions and enhance product performance, welding technologies that can support this transition are gaining significant traction.
Expansion of Customization and Application-Specific Solutions
Another emerging trend in the Europe plastic welding equipment market is the growing demand for customized and application-specific solutions. Manufacturers are seeking equipment that caters to niche requirements-ranging from specific weld joint geometries to material compatibility and energy consumption targets. In response, equipment providers are offering modular designs and flexible configurations that can be easily adapted to different production lines. This trend is particularly relevant in industries such as medical devices, consumer electronics, and aerospace, where precision and compliance with stringent standards are paramount. Customization not only enhances operational efficiency but also provides a competitive edge in a market that values innovation and adaptability.
Market Challenges Analysis
High Initial Investment and Maintenance Costs
One of the primary challenges facing the Europe plastic welding equipment market is the high initial capital investment required for advanced welding systems. Sophisticated technologies such as laser and ultrasonic welding machines come with significant upfront costs, making them less accessible to small and medium-sized enterprises (SMEs). Additionally, the integration of automation and smart manufacturing capabilities, while beneficial for long-term efficiency, adds to the overall expense. These systems often require skilled operators and periodic calibration, leading to increased training and maintenance costs. For companies with limited budgets, these financial barriers may delay the adoption of cutting-edge equipment, thereby restraining market growth, particularly in developing regions of Europe.
Technical Limitations and Material Compatibility Issues
Another critical challenge is the technical complexity and material compatibility constraints associated with plastic welding processes. For instance, the European Plastics Converters Association highlights the difficulties in achieving defect-free welds due to varying thermoplastic properties such as melting points and thermal conductivities. Inconsistent weld quality due to poor joint design, contamination, or improper machine settings can lead to product failures, especially in high-performance applications. Furthermore, not all plastic materials are suitable for welding using standard methods, which limits the flexibility of manufacturers in product design and material selection. These limitations necessitate continuous research, testing, and customization-factors that can increase lead times and operational costs. As industries demand more precision and versatility, overcoming these technical hurdles remains a key challenge for manufacturers and equipment providers alike.
Market Opportunities
The Europe plastic welding equipment market presents substantial growth opportunities driven by the accelerating shift toward sustainable manufacturing and increased use of advanced thermoplastics. As industries across Europe intensify efforts to reduce carbon footprints and adopt eco-friendly production practices, plastic welding emerges as a crucial enabler of circular economy principles. The ability of plastic welding technologies to facilitate the repair, reuse, and recycling of plastic components aligns well with EU regulatory frameworks promoting environmental sustainability. This transition encourages manufacturers to invest in welding solutions that support the processing of biodegradable and recyclable materials, opening new avenues for equipment providers. Additionally, the rising demand for lightweight components in sectors such as automotive and aerospace is prompting the development of innovative welding systems capable of handling next-generation materials with high precision and efficiency.
Further opportunities lie in the expanding applications of plastic welding within emerging industries and the growing demand for customized solutions. Sectors such as medical devices, electronics, and renewable energy are increasingly relying on high-performance plastics for critical components, creating a need for highly specialized and reliable welding equipment. Equipment manufacturers that offer flexible, application-specific systems with features like real-time monitoring, adaptive controls, and compact designs are well-positioned to capitalize on this trend. Moreover, the digital transformation of manufacturing processes, supported by Industry 4.0 technologies, presents opportunities for integrating smart welding equipment with automated production lines. As companies seek to enhance productivity and maintain competitive advantage, the demand for intelligent, efficient, and user-friendly plastic welding solutions is expected to grow steadily. These evolving requirements create fertile ground for innovation and market expansion throughout Europe.
Market Segmentation Analysis:
By Type:
The Europe plastic welding equipment market is segmented by type into manual, semi-automatic, and fully automatic systems, each catering to distinct operational needs. Manual equipment, while offering cost-effectiveness and flexibility, is primarily used in small-scale applications or by industries with limited production volumes. It remains popular among workshops and SMEs due to its low maintenance and ease of use. Semi-automatic systems strike a balance between manual labor and automation, making them ideal for medium-scale operations requiring consistent quality with moderate throughput. However, the fully automatic segment is witnessing the fastest growth, driven by the need for high-speed production, precision, and reduced human intervention. These systems are increasingly adopted in large manufacturing setups, especially in automotive and packaging sectors, where efficiency and repeatability are critical. With growing emphasis on smart manufacturing and the integration of Industry 4.0 technologies, demand for fully automatic plastic welding equipment is expected to dominate the market in the coming years.
By Application:
Based on application, the Europe plastic welding equipment market spans across electronics, packaging, automotive, medical devices, and other industrial uses. The automotive sector holds a significant share due to the rising demand for lightweight, high-strength plastic components that contribute to fuel efficiency and vehicle performance. Packaging also represents a major application area, driven by the need for durable, airtight seals in food, beverage, and consumer goods packaging. In the electronics industry, precise and clean welding is essential for assembling delicate plastic housings and connectors, further boosting demand. The medical device segment is growing steadily, fueled by the increased production of disposable instruments and components requiring hygienic and reliable welds. Additionally, applications in renewable energy, agriculture, and construction are emerging as niche yet promising areas. As innovation and material science continue to advance, plastic welding equipment is finding broader utility across diverse sectors, creating opportunities for market expansion and product specialization in Europe.
Segments:
Based on Type:
- Manual
- Semi-automatic
- Fully Automatic
Based on Application:
- Electronics
- Packaging
- Automotive
- Medical Devices
- Others
Based on Technology:
- Ultrasonic Welding
- Hot Plate Welding
- Spin Welding
- Laser Welding
- Others
Based on the Geography:
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
Regional Analysis
Germany
The Germany market holds the largest share in the Europe plastic welding equipment market, accounting for approximately 23% of the regional revenue in 2024. As Europe’s leading industrial powerhouse, Germany benefits from a strong presence of automotive, electronics, and machinery manufacturers. The country’s advanced manufacturing infrastructure, high investment in automation, and strong R&D capabilities drive the demand for precision plastic welding equipment. German manufacturers prioritize high-quality, efficient, and sustainable production solutions, leading to widespread adoption of fully automatic and smart welding systems. Moreover, the push for electric vehicle production and increasing use of high-performance thermoplastics in automotive applications further support market expansion. Germany’s established position as a leader in engineering and innovation continues to attract international and domestic investments in plastic welding technology.
United Kingdom
The United Kingdom, contributing around 14% of the Europe plastic welding equipment market, represents another key region with consistent growth potential. The UK’s strong medical devices and packaging sectors are major contributors to plastic welding demand, particularly in the context of increased healthcare investment and consumer goods packaging innovations. Additionally, the nation’s automotive industry-despite facing post-Brexit adjustments-remains a significant consumer of advanced welding technologies. British manufacturers are progressively adopting automated and semi-automated equipment to enhance efficiency and meet evolving quality standards. The UK's commitment to environmental sustainability and reduced industrial emissions also fosters the adoption of energy-efficient and recyclable plastic processing technologies, reinforcing market momentum in the coming years.
France
France, with a market share of approximately 12%, plays a vital role in the region due to its growing focus on lightweight materials in automotive, aerospace, and electronics manufacturing. The country is investing in smart industrial technologies, supporting demand for advanced welding solutions such as laser and ultrasonic systems. France’s medical and pharmaceutical sectors are also increasing reliance on precision plastic welding for the production of sterile, single-use components. Government initiatives aimed at boosting domestic manufacturing and innovation are encouraging local players to modernize their equipment. As manufacturers shift toward automation and digital integration, France continues to emerge as a dynamic market with rising adoption of application-specific welding equipment.
Rest of Europe
The Rest of Europe, comprising countries such as Austria, Sweden, Poland, Denmark, Switzerland, Belgium, the Netherlands, and Russia, collectively accounts for around 38% of the Europe plastic welding equipment market. These regions demonstrate varying levels of industrial development but collectively show strong potential for growth. Poland and Austria, for example, are expanding their automotive supply chains, while Sweden and Denmark focus on advanced electronics and renewable energy sectors. Switzerland is notable for its precision engineering and high-end manufacturing requirements, particularly in medical technology. Meanwhile, Russia shows growing interest in domestic manufacturing capabilities, despite geopolitical and economic uncertainties. As these countries invest in infrastructure modernization and localized production, demand for high-quality plastic welding equipment is set to increase, particularly among mid-sized manufacturers seeking flexible and cost-effective solutions.
Key Player Analysis
- Leister Technologies AG
- Herrmann Ultraschalltechnik GmbH & Co. KG
- Bielomatik Leuze GmbH & Co. KG
- Frimo Group GmbH
- RITMO S.p.A.
- LPKF Laser & Electronics AG
- Telsonic AG
- HPT Hochwertige Plastikteile GmbH
- Mecasonic Group
- CEMAS Elettra
Competitive Analysis
The Europe plastic welding equipment market is highly competitive, with several prominent players leading the charge in technological innovation and market share. Key players in this market include Leister Technologies AG, Herrmann Ultraschalltechnik GmbH & Co. KG, Bielomatik Leuze GmbH & Co. KG, Frimo Group GmbH, RITMO S.p.A., LPKF Laser & Electronics AG, Telsonic AG, HPT Hochwertige Plastikteile GmbH, Mecasonic Group, and CEMAS Elettra. These players continually invest in research and development to enhance product capabilities, improve energy efficiency, and offer customizable solutions tailored to diverse industrial applications. Automation and smart technology integration have become central to competitive strategies, with manufacturers offering advanced features such as real-time monitoring, process control, and predictive maintenance. Many companies are also expanding their presence across different European regions through partnerships, acquisitions, and localized production to better serve regional markets. Additionally, there is a strong emphasis on sustainability, prompting companies to develop equipment compatible with recyclable and eco-friendly plastics. This evolving landscape encourages continuous innovation and strategic agility to maintain a competitive edge.
Recent Developments
- In March 2025, Leister transferred its laser plastic welding business to Hymson Novolas AG, a subsidiary of Hymson Laser Technology Group Co. Ltd. The transition ensures continuity and further development of existing product lines, with a new Laser Technology Center established in Switzerland. Leister will now focus more on its core competencies: plastic welding (hot air, infrared) and industrial process heat.
- In February 2025, Herrmann continues to set industry standards with its ultrasonic welding solutions, particularly for medical devices and sensitive components. The company emphasizes individualized process development, intelligent process control, and digital quality monitoring for reproducible, high-strength welds. Herrmann will showcase new applications and integration options at K 2025, focusing on automation and sustainability in medical and packaging industries.
- In January 2025, Dukane highlighted its patented Q-Factor, Melt-Match®, Low Amplitude Preheat, and Ultra-High Frequency (260–400 Hz) vibration welding technologies, emphasizing their leadership in process control and diagnostics.
- In May 2024, Emerson launched the Branson™ GLX-1 Laser Welder, designed for the automated assembly of small, intricate plastic parts. The GLX-1 features a compact, modular design suitable for cleanroom environments, advanced servo-based actuation, and the ability to “un-weld” plastics for closed-loop recycling. It uses Simultaneous Through-Transmission Infrared® (STTlr) laser-welding technology for high efficiency, weld strength, and aesthetics. Enhanced connectivity, security, and data collection features support Industry 4.0 integration.
Market Concentration & Characteristics
The Europe plastic welding equipment market exhibits a moderate to high level of market concentration, with a few key players dominating the landscape through strong brand presence, technological expertise, and diversified product portfolios. Companies such as Leister Technologies AG, Herrmann Ultraschalltechnik GmbH & Co. KG, and LPKF Laser & Electronics AG play a pivotal role in shaping market dynamics, often setting industry benchmarks for innovation and quality. The market is characterized by rapid technological advancements, a growing shift toward automation, and an increasing emphasis on sustainability and precision manufacturing. Equipment providers are focused on offering tailored solutions across various industries, including automotive, packaging, medical, and electronics, where high-performance plastic joining is critical. Additionally, the market is marked by strong customer demand for durability, operational efficiency, and compliance with environmental standards. As a result, competition revolves around innovation, service reliability, and the ability to meet application-specific requirements in an evolving regulatory and industrial landscape.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to experience sustained growth driven by advancements in laser and ultrasonic welding technologies, enhancing precision and efficiency in manufacturing processes.
- Integration of artificial intelligence (AI) and Internet of Things (IoT) technologies is expected to revolutionize plastic welding equipment, enabling real-time monitoring and predictive maintenance.
- The automotive industry's shift towards electric vehicles (EVs) will increase demand for lightweight plastic components, thereby boosting the need for advanced plastic welding solutions.
- Growing emphasis on sustainability and eco-friendly practices will lead to the development of environmentally responsible welding equipment and processes.
- Expansion of the medical devices sector will require high-precision welding equipment to meet stringent quality and safety standards.
- The packaging industry will continue to adopt plastic welding technologies to improve product durability and shelf life.
- Emerging markets in Eastern Europe are anticipated to witness increased adoption of plastic welding equipment due to industrialization and infrastructure development.
- Customization and personalization trends will drive manufacturers to offer tailored welding solutions catering to specific industry needs.
- Collaborations and partnerships among key players will facilitate innovation and expansion into new application areas.
- Continuous investment in research and development will be crucial for companies to stay competitive and address evolving market demands.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Lightweight and Durable Components
Automotive, packaging, and construction industries in Europe are increasingly using plastic welding equipment to assemble lightweight and durable plastic parts, which improves fuel efficiency and product performance.
Stringent Environmental Regulations and Sustainability Goals
European regulations promoting recyclable materials and eco-friendly manufacturing are accelerating the adoption of plastic welding technologies that support sustainable production and circular economy initiatives.
Technological Advancements and Automation Integration
The integration of automation, precision control, and smart manufacturing technologies is enhancing welding quality, operational efficiency, and repeatability, making advanced plastic welding equipment attractive for high-volume and precision-driven industries.
Growth in Electric Vehicles and High-Performance Plastics
The rapid expansion of the electric vehicle market and increased use of high-performance plastics in sectors like automotive and medical devices are driving demand for advanced plastic welding solutions capable of handling complex and diverse material requirements.
Adoption of Non-Contact and Precision Welding Techniques
Manufacturers are increasingly shifting to non-contact welding methods such as laser and ultrasonic welding, which offer higher precision, speed, and suitability for complex assemblies, supporting innovation in high-tech and regulated industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Plastic Welding Equipment?
What factors are driving the growth of the Europe Plastic Welding Equipment?
What are the key segments within the Europe Plastic Welding Equipment?
What are some challenges faced by the Europe Plastic Welding Equipment?
Who are the major players in the Europe Plastic Welding Equipment?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Manual
- 1.2.2 Semi-automatic
- 1.2.3 Fully Automatic
- 1.3 By Technology
- 1.3.1 Ultrasonic Welding
- 1.3.2 Hot Plate Welding
- 1.3.3 Spin Welding
- 1.3.4 Laser Welding
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Automotive
- 1.4.2 Packaging
- 1.4.3 Electronics
- 1.4.4 Medical Devices
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,985.82 million → 2032: USD 4,938.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Europe Plastic Welding Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Europe Plastic Welding Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Europe Plastic Welding Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Europe Plastic Welding Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Europe Plastic Welding Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Europe Plastic Welding Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Europe Plastic Welding Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Europe Plastic Welding Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,985.82 million → 2032: USD 4,938.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Europe Plastic Welding Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Manual
- 12.3.7.2 Semi-automatic
- 12.3.7.3 Fully Automatic
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ultrasonic Welding
- 12.4.7.2 Hot Plate Welding
- 12.4.7.3 Spin Welding
- 12.4.7.4 Laser Welding
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Packaging
- 12.5.7.3 Electronics
- 12.5.7.4 Medical Devices
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Europe Plastic Welding Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Europe Plastic Welding Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Europe Plastic Welding Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Europe Plastic Welding Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Leister Technologies AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Herrmann Ultraschalltechnik GmbH & Co. KG
- 18.4 Bielomatik Leuze GmbH & Co. KG
- 18.5 Frimo Group GmbH
- 18.6 RITMO S.p.A.
- 18.7 LPKF Laser & Electronics AG
- 18.8 Telsonic AG
- 18.9 HPT Hochwertige Plastikteile GmbH
- 18.10 Mecasonic Group
- 18.11 CEMAS Elettra
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

