
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
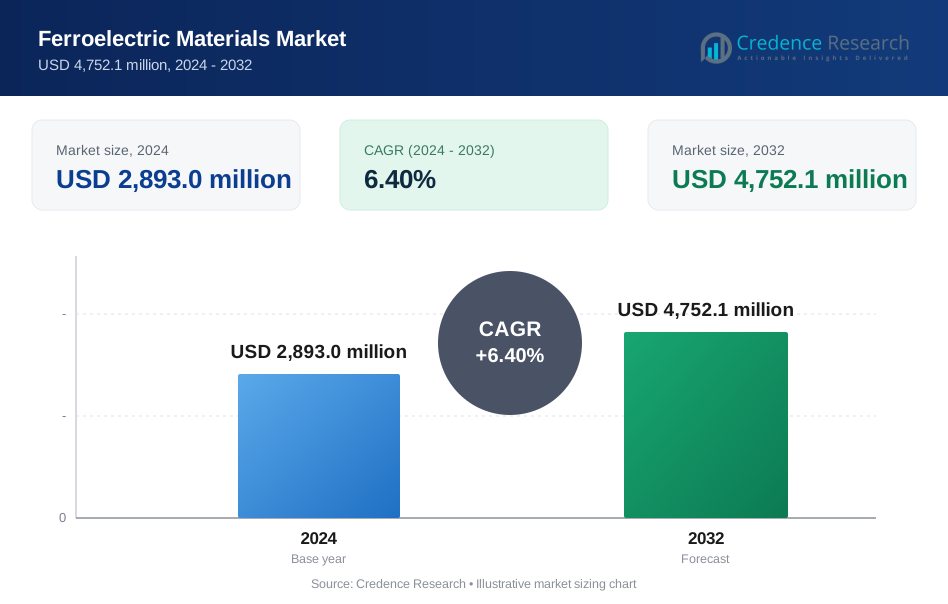
| Ferroelectric Materials Market Size 2024 | USD 2,893.0 million |
| Ferroelectric Materials Market, CAGR | 6.40% |
| Ferroelectric Materials Market Size 2032 | USD 4,752.1 million |
Market Overview
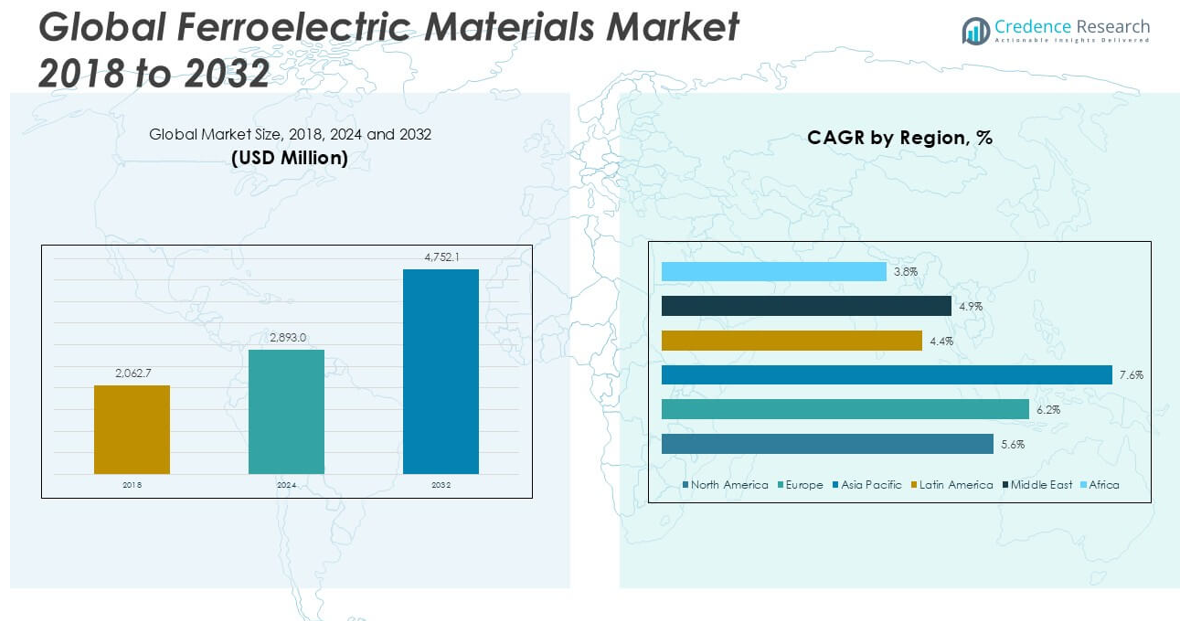
The Ferroelectric Materials market size was valued at USD 2,062.7 million in 2018, increased to USD 2,893.0 million in 2024, and is anticipated to reach USD 4,752.1 million by 2032, at a CAGR of 6.40% during the forecast period.
The Ferroelectric Materials market is led by key players such as Murata Manufacturing Co., Ltd., TDK Corporation, KYOCERA Corporation, KEMET Corporation, CTS Corporation, and PI Ceramic GmbH, each known for their strong technological capabilities and diversified product offerings. These companies maintain a competitive edge through continuous innovation, strategic partnerships, and expansion across high-growth sectors like consumer electronics and automotive. Asia Pacific holds the dominant position in the global market, accounting for approximately 36.9% of the total market share in 2018, driven by robust manufacturing bases in China, Japan, and South Korea. The region benefits from high demand for electronic devices, rapid industrialization, and favorable production economics, making it the most influential contributor to market growth. North America and Europe follow, supported by technological advancements and increasing adoption of eco-friendly, lead-free ferroelectric materials.
Market Insights
- The Ferroelectric Materials market was valued at USD 2,062.7 million in 2018, reached USD 2,893.0 million in 2024, and is expected to grow to USD 4,752.1 million by 2032, registering a CAGR of 6.40% during the forecast period.
- The market is driven by increasing demand for ceramic capacitors and PTC thermistors in consumer electronics, automotive, and energy storage sectors, with Barium Titanate holding the largest segment share due to its superior dielectric properties.
- Rising trends include the shift towards lead-free ferroelectric materials and growing integration in non-volatile memory devices, with manufacturers focusing on sustainable and high-performance solutions.
- Competitive intensity is high with key players like Murata Manufacturing, TDK Corporation, and KYOCERA Corporation expanding through R&D, partnerships, and global distribution networks.
- Asia Pacific leads the market with a 36.9% share in 2018, followed by Europe and North America, while growth in Africa remains limited due to slower technology adoption.
Market Segmentation Analysis:
By Type:
In the Ferroelectric Materials market, the Barium Titanate segment holds the dominant market share owing to its extensive application in multilayer ceramic capacitors, thermistors, and electro-optic devices. Barium Titanate’s superior dielectric properties, high permittivity, and cost-effectiveness are key drivers supporting its widespread adoption across consumer electronics and telecommunication sectors. Its ability to offer excellent temperature stability further boosts its demand in various precision electronic components. The "Others" segment, which includes alternative ferroelectric materials like lead zirconate titanate, contributes moderately, driven by specialized applications requiring higher piezoelectric performance.
- For instance, Murata Manufacturing has developed Barium Titanate-based multilayer ceramic capacitors with capacitance values reaching up to 470 µF, supporting the miniaturization of high-density electronic circuits.
By Application
The Ceramic Capacitor segment leads the Ferroelectric Materials market, holding the largest share due to the rising demand for compact, high-capacitance electronic components in smartphones, automotive electronics, and industrial equipment. Ceramic capacitors made from ferroelectric materials like Barium Titanate offer high reliability, miniaturization capabilities, and stable performance across a wide temperature range, fueling their market dominance. The PTC Thermistor segment follows, driven by its crucial role in overcurrent protection and temperature sensing applications. The "Others" category accounts for a smaller share, catering to niche uses in memory devices and sensors.
- For instance, KYOCERA Corporation offers high-capacitance ceramic capacitors with rated voltages up to 100 V and capacitance values exceeding 100 µF, specifically designed for automotive powertrain modules.
Market Overview
Rising Demand from Consumer Electronics
The increasing use of ferroelectric materials in consumer electronics, such as smartphones, tablets, and wearable devices, is a significant growth driver. These materials are essential in the production of ceramic capacitors and memory chips, which support device miniaturization and enhanced performance. The expanding electronics market, particularly in Asia-Pacific, further accelerates demand. As consumers seek faster, more reliable devices, manufacturers are increasingly adopting ferroelectric materials to meet stringent performance standards and ensure compact, energy-efficient electronic components.
- For instance, Samsung Electronics utilizes ferroelectric capacitors in their Galaxy smartphone series to stabilize power supply circuits, supporting memory modules with data transfer rates up to 6400 MT/s.
Growing Automotive Applications
The rapid adoption of electronic components in modern vehicles is propelling the ferroelectric materials market. Ferroelectric capacitors and sensors are widely used in advanced driver-assistance systems (ADAS), electric vehicles (EVs), and infotainment systems, which require stable and durable components. The automotive industry’s shift toward electrification and autonomous technologies enhances the need for high-performance materials capable of withstanding varying temperatures and mechanical stresses, positioning ferroelectric materials as crucial components in next-generation automotive designs.
- For instance, Murata’s ferroelectric capacitors are used in automotive engine control units (ECUs) that operate reliably at temperatures up to 150°C, critical for under-the-hood applications.
Expansion in Energy Storage and Harvesting Technologies
The growing focus on energy efficiency and renewable energy solutions has led to increased interest in ferroelectric materials for energy storage and harvesting applications. These materials offer excellent energy density and stability, making them suitable for advanced batteries, capacitors, and energy harvesting systems. Research and development efforts are expanding their potential in wearable energy devices and low-power sensors. As industries prioritize sustainable energy solutions, the application of ferroelectric materials in innovative energy systems is expected to rise steadily.
Key Trends & Opportunities
Development of Lead-Free Ferroelectric Materials
Environmental concerns and stringent regulations are driving the development of lead-free ferroelectric materials. Traditional lead-based compounds, such as lead zirconate titanate (PZT), are being gradually replaced by eco-friendly alternatives like barium titanate and potassium sodium niobate. This shift presents significant growth opportunities for companies focusing on green technologies. The development of high-performance, lead-free materials not only addresses regulatory compliance but also appeals to sustainability-focused industries, particularly in Europe and North America.
- For instance, PI Ceramic GmbH has successfully commercialized lead-free piezoelectric ceramics with a d33 coefficient of 250 pC/N, offering comparable performance to traditional PZT materials.
Increasing Integration in Non-Volatile Memory Devices
The integration of ferroelectric materials in non-volatile memory technologies, particularly Ferroelectric RAM (FeRAM), is an emerging market trend. These materials enable faster data processing, lower power consumption, and improved memory retention compared to traditional solutions. The rising demand for efficient memory storage in automotive, healthcare, and industrial applications creates new opportunities for ferroelectric materials. As industries pursue higher speed and reliability, the adoption of FeRAM is poised to contribute significantly to market expansion.
- For instance, Fujitsu Semiconductor has developed FeRAM chips with read/write speeds of 35 nanoseconds and endurance exceeding 10¹² read/write cycles, supporting mission-critical automotive and factory automation systems.
Key Challenges
Complex Manufacturing Processes
The production of ferroelectric materials involves complex, multi-step manufacturing processes that require precise control over material properties and high-purity inputs. These stringent requirements increase production costs and present scalability challenges for manufacturers. Small deviations in processing conditions can significantly impact material performance, leading to higher rejection rates and reduced profitability. Addressing these complexities remains a critical challenge for companies aiming to achieve cost-effective, high-quality mass production.
Environmental and Health Concerns with Lead-Based Materials
The continued use of lead-based ferroelectric materials poses significant environmental and health risks, prompting regulatory restrictions across several regions. Complying with evolving environmental standards, such as the Restriction of Hazardous Substances (RoHS) directive, places pressure on manufacturers to transition toward safer alternatives. However, developing lead-free substitutes with comparable performance remains technically challenging and resource-intensive, delaying widespread adoption and complicating the market landscape.
Intense Competition from Substitute Materials
Ferroelectric materials face competition from alternative materials and technologies, such as high-k dielectrics and advanced polymer-based capacitors. These substitutes offer similar benefits in terms of miniaturization and energy efficiency, potentially reducing the demand for traditional ferroelectric solutions. The rapid pace of material innovation in the electronics and energy storage sectors further intensifies competition, requiring manufacturers to invest continuously in R&D to maintain their market position.
Regional Analysis
North America
In 2018, the North America ferroelectric materials market was valued at USD 515.7 million, accounting for approximately 25.0% of the global market share. By 2024, the market reached USD 650.9 million and is projected to grow to USD 940.9 million by 2032, expanding at a CAGR of 5.6%. Growth in this region is driven by strong demand from consumer electronics, automotive applications, and the adoption of advanced energy storage solutions. The U.S. remains a key contributor, supported by ongoing technological advancements and substantial investments in research and development across ferroelectric material applications.
Europe
The Europe ferroelectric materials market was valued at USD 546.6 million in 2018, holding around 26.5% of the global market share. It reached USD 694.3 million in 2024 and is forecasted to grow to USD 1,021.7 million by 2032, progressing at a CAGR of 6.2%. Europe’s growth is fueled by stringent environmental regulations encouraging lead-free material adoption and increased use of ferroelectric materials in electric vehicles and renewable energy systems. Countries like Germany and France are key markets, driven by robust electronics manufacturing and supportive government policies promoting advanced material development.
Asia Pacific
Asia Pacific dominated the global ferroelectric materials market in 2018 with a value of USD 761.1 million, representing approximately 36.9% of the market share. The market surged to USD 1,186.1 million in 2024 and is expected to reach USD 2,209.7 million by 2032, growing at the highest CAGR of 7.6%. The region’s growth is primarily driven by China, Japan, and South Korea, where the demand for consumer electronics, automotive components, and renewable energy solutions is rapidly increasing. Asia Pacific benefits from a strong manufacturing base, low production costs, and substantial investments in technological innovation.
Latin America
Latin America’s ferroelectric materials market was valued at USD 70.1 million in 2018, accounting for around 3.4% of the global market share. It reached USD 112.8 million in 2024 and is anticipated to grow to USD 213.8 million by 2032, at a CAGR of 4.4%. Growth in this region is supported by the gradual expansion of the electronics and automotive sectors, particularly in Brazil and Mexico. Although the market size is relatively small compared to other regions, increasing investments in manufacturing infrastructure and rising consumer demand for advanced electronics are driving steady market growth.
Middle East
The Middle East ferroelectric materials market held a value of USD 111.4 million in 2018, capturing approximately 5.4% of the global market share. By 2024, the market size reached USD 162.0 million and is projected to grow to USD 280.4 million by 2032, registering a CAGR of 4.9%. Market growth is driven by the increasing adoption of advanced electronic devices and investments in smart infrastructure projects across the Gulf Cooperation Council (GCC) countries. Rising demand for high-performance materials in energy and automotive applications further supports the region’s long-term growth potential.
Africa
Africa’s ferroelectric materials market was valued at USD 57.8 million in 2018, representing around 2.8% of the global market share. The market expanded to USD 86.8 million in 2024 but is expected to slightly decline to USD 85.5 million by 2032, reflecting limited growth potential and a relatively low CAGR of 3.8%. Market progression is restrained by limited industrial infrastructure, lower consumer spending on advanced electronics, and slower adoption of modern automotive technologies. However, small pockets of growth may emerge with gradual technological penetration and regional development efforts across selected African countries.
Market Segmentations:
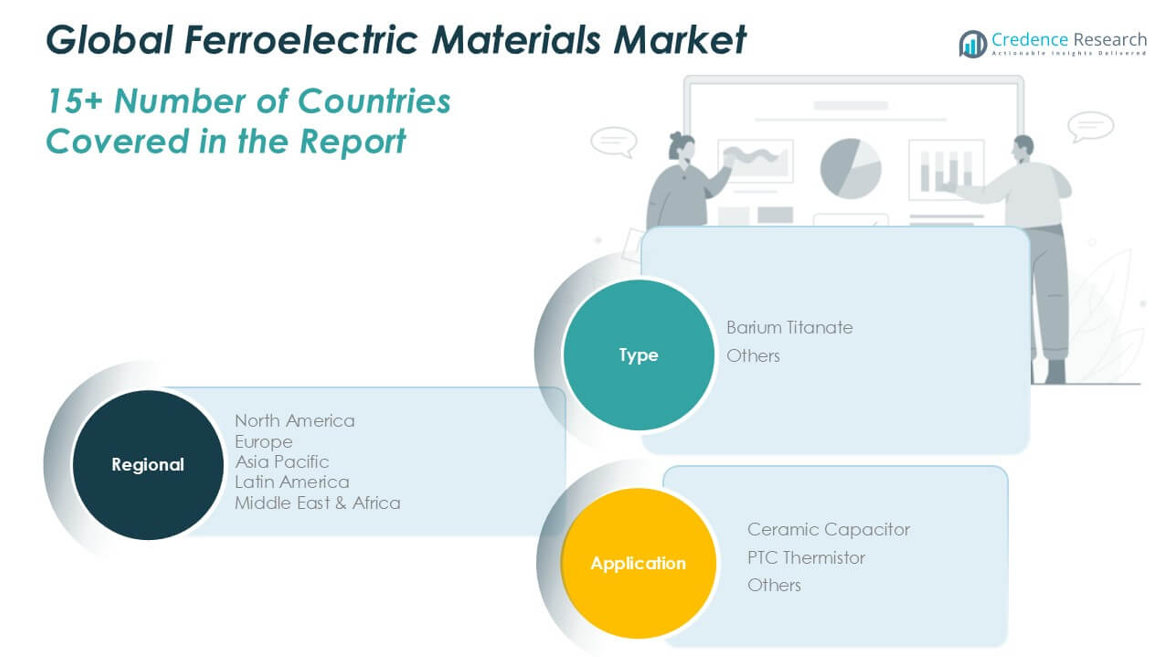
By Type
- Barium Titanate
- Others
By Application
- Ceramic Capacitor
- PTC Thermistor
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Ferroelectric Materials market is characterized by the presence of several established players competing on the basis of product quality, technological innovation, and global reach. Companies such as Murata Manufacturing Co., Ltd., TDK Corporation, KYOCERA Corporation, and KEMET Corporation hold significant market shares due to their strong product portfolios and advanced manufacturing capabilities. These players focus heavily on research and development to introduce lead-free and high-performance ferroelectric materials that comply with stringent environmental regulations. Strategic collaborations, mergers, and acquisitions are common in this market, enabling companies to expand their geographic presence and enhance their technological expertise. Smaller manufacturers and specialized companies, including PI Ceramic GmbH and Sensor Technology Ltd., compete by offering customized solutions for niche applications. The competitive intensity is further driven by the rapid pace of innovation in the electronics and automotive sectors, pushing companies to continuously improve material performance and production efficiency to maintain market relevance.
Key Player Analysis
- Murata Manufacturing Co., Ltd.
- TDK Corporation
- KYOCERA Corporation
- KEMET Corporation
- CTS Corporation
- PI Ceramic GmbH
- APC International, Ltd.
- CeramTec GmbH
- Fuji Ceramics Corporation
- Morgan Advanced Materials
- Sparkler Ceramics Pvt. Ltd.
- TRS Technologies, Inc.
- Morgan Advanced Materials (Duplicate Entry)
- Sensor Technology Ltd.
Recent Developments
- In May 2025, Murata collaborated with the National Institute for Materials Science (NIMS) to create the largest-ever database of dielectric material properties, including seven important ferroelectric material families. This AI-driven project aims to accelerate the development of next-generation electronic materials and energy storage technologies.
- In August 2024, PI Ceramic highlighted its wide selection of piezoelectric ceramic materials based on modified lead zirconate titanate (PZT) and barium titanate, key ferroelectric materials, underscoring their expertise and product range.
- In July 2024, CTS launched a new lead-free piezoceramic materials program with nine distinct materials optimized for various applications, including four new formulations. This represents a significant development in environmentally friendly ferroelectric piezoceramics.
- In June 2024, TDK announced the successful development of a new material for their CeraCharge solid-state battery with 100 times higher energy density than their previous models. This oxide-based solid electrolyte material is safer and intended for wearable devices, which may involve ferroelectric or related dielectric materials in battery technology.
- In March 2023, The Ferroelectric 2D materials can act as a nanoscale switch and motor researched by Rice Unversity scientist Boris Yakobson and his team. They said 2D material is very thin and flexible, and single-layer ferroelectric material builds an anticipated active bending behavior.
- In Sep 2022, a United States scientist develops the properties of ferroelectric, a lead-free perovskite material that can be used in solar cells. It can be made from the germanium tribromide and primary inspection results creates the ferroelectricity.
Market Concentration & Characteristics
The Ferroelectric Materials Market exhibits a moderately consolidated structure, with a few large multinational companies holding significant market shares alongside several regional and specialized players. It is characterized by high technological barriers and a strong reliance on advanced manufacturing processes to achieve precision and material consistency. Companies focus on product innovation, particularly the development of lead-free alternatives, to meet evolving environmental regulations and rising customer preferences for sustainable materials. The market demonstrates steady demand across consumer electronics, automotive, and energy storage sectors, supported by the growing need for miniaturized and high-performance components. It remains highly competitive, with firms actively pursuing research and development, strategic partnerships, and capacity expansions to maintain their position. Strong regional concentration in Asia Pacific, particularly in China, Japan, and South Korea, strengthens the supply base and supports fast-paced manufacturing. Price competition, regulatory compliance, and the need for continuous technological advancements shape its core characteristics and competitive dynamics.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Ferroelectric Materials Market is expected to witness steady growth driven by rising demand in consumer electronics and automotive sectors.
- Increasing adoption of electric vehicles will continue to boost the need for ferroelectric components in power management and sensing applications.
- Development of lead-free ferroelectric materials will gain momentum due to tightening environmental regulations.
- Growing use of ferroelectric materials in energy harvesting and storage solutions will create new market opportunities.
- Advancements in ferroelectric memory technologies like FeRAM will support market expansion across data storage applications.
- Companies will focus on improving manufacturing efficiency to address cost challenges and meet large-scale demand.
- Asia Pacific will remain the dominant region supported by strong electronics manufacturing hubs in China, Japan, and South Korea.
- Europe and North America will grow steadily, driven by the shift toward sustainable and high-performance materials.
- Competition will intensify as key players invest in innovation, strategic alliances, and product diversification.
- Market growth may face challenges from complex processing requirements and rising competition from substitute materials.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Ferroelectric Materials Market?
What are the key segments within the Ferroelectric Materials Market?
What are some challenges faced by the Ferroelectric Materials Market?
Who are the major players in the Ferroelectric Materials Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ferroelectric Materials Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ferroelectric Materials Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,893.0 million → 2032: USD 4,752.1 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ferroelectric Materials Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ferroelectric Materials Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ferroelectric Materials Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ferroelectric Materials Market Drivers
- 3.3 Ferroelectric Materials Market Restraints & Challenges
- 3.4 Ferroelectric Materials Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ferroelectric Materials Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ferroelectric Materials Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ferroelectric Materials category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ferroelectric Materials Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Ferroelectric Materials Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Ferroelectric Materials. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ferroelectric Materials Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ferroelectric Materials Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Ferroelectric Materials Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ferroelectric Materials (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Ferroelectric Materials
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ferroelectric Materials Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Ferroelectric Materials Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ferroelectric Materials Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ferroelectric Materials Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ferroelectric Materials Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ferroelectric Materials Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ferroelectric Materials Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ferroelectric Materials Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
