
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Fertilizer Additives Market Size 2023 | USD 3,718.89 Million |
| Fertilizer Additives Market, CAGR | 2.30% |
| Fertilizer Additives Market Size 2032 | USD 4,460.85 Million |
Market Overview
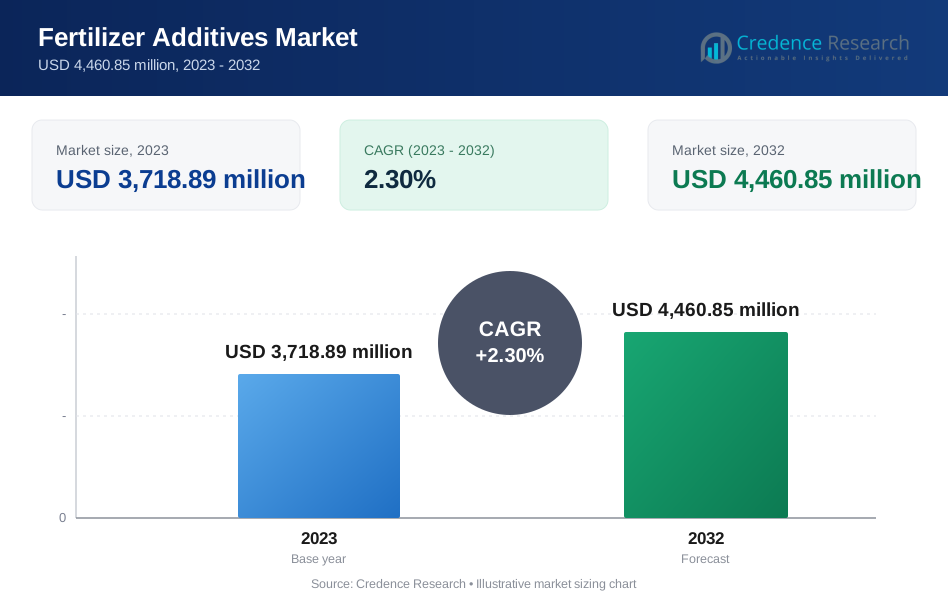
The Fertilizer Additives Market is projected to grow from USD 3,718.89 million in 2023 to an estimated USD 4,460.85 million by 2032, with a compound annual growth rate (CAGR) of 2.30% from 2024 to 2032. This growth is attributed to the increasing demand for enhanced agricultural productivity and the need for efficient fertilizer formulations that minimize losses and environmental impact.
Key drivers for the Fertilizer Additives Market include the global rise in food demand due to population growth, ongoing efforts to improve crop yields, and the need for sustainable agricultural practices. Trends such as the adoption of precision agriculture and increased awareness about the benefits of nutrient-efficient fertilizers also contribute to market expansion. Moreover, stringent regulations on fertilizer quality in various regions push manufacturers to integrate advanced additives, which help in reducing fertilizer wastage and ensuring more targeted nutrient delivery.
Geographically, Asia-Pacific dominates the Fertilizer Additives Market, driven by large agricultural economies like China and India, where there is a strong focus on enhancing crop productivity. North America and Europe follow, with a growing emphasis on sustainable and efficient agricultural practices. Key players in the global fertilizer additives market include BASF SE, Clariant AG, Arkema S.A., and Solvay S.A., who continue to invest in research and development to offer innovative additive solutions and meet the evolving needs of the agricultural sector.
Market Drivers
Growing Global Demand for Food Production
The global population is projected to reach 9.7 billion by 2050, which requires a significant increase in food production to meet rising consumption levels. This demand is pushing agricultural producers to maximize crop yields and improve efficiency. Fertilizer additives are essential in this scenario, as they enhance the quality and effectiveness of fertilizers. They help minimize nutrient loss, reduce caking, and improve granulation, which ensures optimal nutrient delivery to crops. By enabling farmers to use fertilizers more efficiently, these additives contribute to greater food production and increased agricultural productivity. For instance, the UN Food and Agriculture Organization estimates that global food production will need to increase by 70% by 2050 to feed the projected population of 9.7 billion. This trend is expected to fuel the demand for fertilizer additives as agricultural intensification becomes increasingly necessary.
Emphasis on Sustainable Agricultural Practices
Sustainability has become a key focus in modern agriculture, with efforts to reduce the environmental impact of farming activities and promote eco-friendly practices. Fertilizer additives play a crucial role in this shift by helping to lower the ecological footprint of fertilizers. For instance, additives like dust suppressants and anti-caking agents prevent waste and enhance handling safety, while others improve nutrient uptake, thus reducing the need for excess fertilizer application. As a result, the adoption of sustainable farming methods is driving demand for fertilizer additives, which help optimize fertilizer efficiency and reduce harmful run-off into water systems. For instance, a study found that using certain fertilizer additives can reduce nitrogen losses by up to 50%, significantly decreasing environmental impact. This alignment with sustainable agriculture is expected to be a significant driver in the fertilizer additives market.
Technological Advancements in Fertilizer Formulation
Technological innovation is another major driver in the fertilizer additives market. Advances in formulation technologies enable manufacturers to develop more efficient and specialized additives, improving the overall performance of fertilizers. For example, recent developments have led to additives that increase nutrient availability for longer periods and protect fertilizers from harsh environmental conditions. Additionally, the rise of precision agriculture is pushing the development of additives that support site-specific nutrient management. These advancements not only enhance fertilizer effectiveness but also enable farmers to achieve higher yields with fewer resources. For instance, research shows that advanced slow-release fertilizers using polymer coatings can extend nutrient release for up to 6-8 months, compared to just 2-4 weeks for conventional fertilizers. As technologies evolve, the demand for advanced fertilizer additives is expected to grow, as they align well with modern agricultural practices and sustainability goals.
Stringent Regulations on Fertilizer Quality and Environmental Safety
The fertilizer industry is subject to strict regulations regarding product quality and environmental safety. Governments worldwide are increasingly focused on reducing the negative impacts of fertilizer use, such as nutrient runoff, soil degradation, and air pollution. To meet regulatory standards, fertilizer manufacturers are incorporating additives that improve product stability, reduce dust emissions, and enhance nutrient delivery efficiency. For example, in regions like the European Union and North America, regulatory frameworks promote the use of additives that mitigate nitrogen emissions and other environmental concerns. These regulations are encouraging manufacturers to adopt advanced additive solutions, thereby driving growth in the fertilizer additives market as companies strive to comply with stringent environmental standards while meeting the needs of modern agriculture.
Market Trends
Increased Focus on Nutrient Efficiency and Precision Agriculture
One of the key trends in the Fertilizer Additives Market is the increased focus on nutrient efficiency, driven by the adoption of precision agriculture practices. Precision agriculture technologies allow farmers to apply fertilizers more accurately, optimizing nutrient distribution based on the specific needs of crops and soil conditions. Fertilizer additives, such as slow-release agents and stabilizers, are crucial in this context, as they help regulate nutrient release rates, ensuring a sustained nutrient supply to crops over time. This approach minimizes nutrient losses through leaching or volatilization, leading to improved fertilizer use efficiency. For instance, a study conducted across 66 farms in the United States found that precision agriculture techniques combined with nutrient-efficient fertilizer additives reduced nitrogen application rates by an average of 27 kg per hectare while maintaining or improving crop yields. Furthermore, nutrient-efficient additives help reduce the overall amount of fertilizer required, which not only supports cost savings for farmers but also aligns with environmentally sustainable agricultural practices. As precision agriculture continues to gain traction, the demand for advanced fertilizer additives tailored to enhance nutrient efficiency is expected to grow, making it a pivotal trend in the market.
Growing Demand for Environmentally Friendly Additives
With increasing awareness of environmental sustainability, there is a notable shift towards environmentally friendly fertilizer additives. Farmers, regulatory bodies, and consumers are more conscious of the environmental impact of traditional fertilizers, which can contribute to issues like water pollution, soil degradation, and greenhouse gas emissions. As a result, fertilizer additive manufacturers are developing products that minimize these negative impacts. For example, bio-based and biodegradable additives are gaining popularity due to their reduced environmental footprint. Similarly, additives that decrease ammonia volatilization and nitrous oxide emissions are becoming essential for meeting stringent environmental regulations in various regions. Additionally, anti-caking agents and dust suppressants are being formulated with eco-friendly materials that prevent the release of harmful particles into the environment. This shift towards sustainable, low-impact additives is a significant trend in the fertilizer additives market, as it aligns with the global push for more sustainable agricultural practices and regulatory compliance. Consequently, the focus on environmentally friendly additives is expected to drive innovation and growth in the market as agricultural stakeholders prioritize sustainable solutions.
Market Restraints and Challenges
High Costs of Advanced Additives
One of the primary challenges in the Fertilizer Additives Market is the high cost associated with advanced additives, which can limit their adoption, especially among small-scale and cost-sensitive farmers. Specialized additives, such as controlled-release agents and bio-based options, are often more expensive to produce due to the costs involved in research, development, and manufacturing. This can lead to higher product prices, which may deter farmers from incorporating them into their regular agricultural practices. In many developing regions, where farming budgets are often tight, the added expense of fertilizer additives can be a significant barrier. Moreover, price volatility in raw materials used for additive production further compounds this issue, impacting the affordability of these products. Therefore, while advanced additives offer notable benefits, their higher costs remain a key restraint in the market, affecting broader adoption.
Regulatory and Environmental Compliance Challenges
The Fertilizer Additives Market also faces challenges related to stringent regulatory requirements and environmental compliance. In regions such as North America and Europe, regulatory bodies enforce strict guidelines on fertilizer additives to ensure they do not adversely impact human health or the environment. Compliance with these regulations often requires significant investment in product testing, certification, and reformulation, which can be time-consuming and costly for manufacturers. Additionally, environmental concerns surrounding chemical additives have prompted restrictions on certain compounds, compelling companies to develop new formulations that meet evolving regulatory standards. While this pushes manufacturers towards more sustainable and eco-friendly solutions, it also poses challenges, as the reformulation process can lead to increased production costs and delays in bringing products to market. As a result, navigating complex regulatory landscapes and adhering to environmental standards remain substantial challenges for the fertilizer additives industry.
Market Segmentation Analysis
By Type
In the Fertilizer Additives Market, various types of additives cater to specific needs, each playing a crucial role in enhancing fertilizer performance. Anticaking agents prevent clumping, ensuring fertilizers remain manageable and stable, particularly in humid environments, making them a significant market segment with growing demand. Dust suppressors, essential for minimizing dust-related health risks and pollution, are particularly valued in regions with stringent environmental regulations, reflecting an increased focus on safety and compliance. Drying agents are vital in high-humidity areas, as they reduce moisture content, thus enhancing the shelf-life and efficacy of fertilizers-a factor that is gaining traction among farmers and producers. Granulating agents, essential for precision agriculture, improve fertilizer texture and uniformity, enabling accurate nutrient distribution, which is crucial for the rising adoption of precision farming practices. Additionally, the “Others” category includes specialty additives like corrosion inhibitors and binding agents, which, though smaller in market share, are indispensable for specific applications requiring enhanced stability and compatibility. Together, these additives contribute to the overall efficiency and effectiveness of fertilizers, driven by industry innovations and an emphasis on sustainable agricultural practices.
By Application
The application of fertilizer additives spans across several key segments, with nitrogen-based fertilizers leading due to nitrogen's critical role in plant growth. Additives in this segment enhance efficiency by reducing nutrient losses from volatilization and leaching, aligning with the focus on nutrient-use efficiency and sustainable agriculture. For phosphorous pentoxide (P₂O₅) fertilizers, additives are essential in improving phosphorus availability and minimizing soil fixation, especially in phosphorus-deficient regions, driving demand as phosphorus supports root development and energy transfer in plants. Potassium oxide (K₂O) fertilizers also benefit from additives that improve stability, reduce caking, and ensure controlled nutrient release, which is vital for plant resilience against diseases and environmental stresses like drought. Additionally, secondary and micronutrient fertilizers, including calcium, magnesium, and sulfur, utilize specific additives to address nutrient deficiencies and enhance availability, with demand increasing as balanced fertilization practices gain importance in modern agriculture.
Segments
Based on Type
- Anticaking Agents
- Dust Suppressors
- Drying Agents
- Granulating Agents
- Others
Based on Application
- Nitrogen
- Phosphorous Pentoxide
- Potassium Oxide
- Others
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
Asia-Pacific (40%):
Asia-Pacific holds the largest market share in the fertilizer additives market, accounting for approximately 40% of the global market. This dominance is driven by the region’s significant agricultural sector, which includes major food-producing countries like China, India, and Indonesia. These countries face high demand for fertilizers to support large-scale agricultural production and meet the growing food requirements of rapidly expanding populations. Fertilizer additives are increasingly utilized to enhance efficiency and crop yield, making them essential in the region. Furthermore, initiatives promoting sustainable agricultural practices are driving demand for advanced fertilizer additives, particularly in China and India, where government policies encourage improved fertilizer application efficiency.
North America (20%):
North America represents about 20% of the global fertilizer additives market. The United States and Canada are leading users of fertilizer additives due to their advanced agricultural sectors and high adoption rates of precision farming practices. The region’s stringent environmental regulations regarding fertilizer use drive demand for additives that enhance nutrient efficiency and reduce environmental impact. Additionally, farmers in North America are increasingly aware of the benefits of using advanced additives to optimize fertilizer performance, reduce wastage, and improve crop yields. The growing focus on sustainable farming and nutrient management strategies further fuels demand in this market segment.
Key players
- Arkema S.A.
- Fertibon Products Pvt. Ltd.
- ArrMaz
- Timac Agro USA
- Chemipol S.A.
- Neelam Aqua & Speciality Chem (P) Ltd.
- Hubei Forbon Technology Co. Ltd.
- Clariant AG
- Michelman Inc.
- Dorf Ketal
Competitive Analysis
The Fertilizer Additives Market is highly competitive, with key players focusing on product innovation, strategic partnerships, and geographic expansion to gain a competitive edge. Arkema S.A. and Clariant AG lead the market due to their broad product portfolios and substantial research and development investments, which allow them to develop advanced and sustainable fertilizer additives. Companies like ArrMaz and Timac Agro USA emphasize customer-centric solutions by offering tailored products that enhance nutrient efficiency and meet regional regulatory requirements. Emerging players, including Hubei Forbon Technology Co. Ltd. and Neelam Aqua & Speciality Chem (P) Ltd., are gaining traction by expanding their presence in the Asia-Pacific and Latin American markets, where demand for sustainable agricultural inputs is growing. Overall, the market’s competitive landscape is shaped by the need for environmentally friendly solutions and advanced additives that enhance fertilizer effectiveness while meeting evolving regulatory standards.
Recent Developments
- In May 2023, Arkema announced the acquisition of ArrMaz, a US producer of specialty surfactants for crop nutrition and mining, for $570 million. This acquisition is expected to enhance Arkema's specialty chemicals portfolio and is part of their growth strategy in performance additives.
- In May 2023, As mentioned above, ArrMaz was acquired by Arkema S.A..
- In July 2023, Timac Agro USA completed the acquisition of Rainbow Plant Food to enhance its presence and optimize its industrial activities in the United States, focusing on innovative fertilizer technologies and improving market positioning.
- In March 2024, Clariant launched the AmoMax-10 catalyst which is designed to enhance ammonia synthesis processes more efficiently and increase yields of ammonia production, thereby improving fertilizer application and food supply systems.
- In May 2024, Dorf Ketal acquired Impact Fluid Solutions to expand its suite of solutions for oil and gas production, which may include applications that extend to the fertilizer additives sector.
Market Concentration and Characteristics
The Fertilizer Additives Market is moderately concentrated, with a mix of well-established global players and regional firms competing to meet diverse agricultural needs. Key characteristics of the market include a strong focus on product innovation and sustainability, driven by the rising demand for nutrient-efficient and eco-friendly fertilizers. Major players, such as Arkema S.A., Clariant AG, and Timac Agro USA, hold significant market shares due to their broad product offerings and investment in research and development. At the same time, regional companies are gaining ground by addressing specific local needs and compliance with regulatory standards. The market is characterized by ongoing advancements in additive formulations, increased emphasis on reducing environmental impact, and a heightened focus on precision agriculture, which collectively drive demand for specialized and high-performance fertilizer additives.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Fertilizer Additives Market is expected to grow steadily, fueled by the global need for increased agricultural productivity to support population growth.
- As nutrient-use efficiency becomes a priority, the demand for additives that reduce nutrient loss and enhance fertilizer performance will continue to rise.
- With the growing focus on sustainable agriculture, additives that minimize environmental impact, such as bio-based and biodegradable options, are likely to gain traction.
- The adoption of precision agriculture technologies will drive demand for specialized additives that support site-specific nutrient management and controlled nutrient release.
- Emerging economies in Asia-Pacific and Latin America are expected to increase fertilizer additive usage as they strive to boost crop yields and improve food security.
- The shift toward environmentally friendly additives will intensify, with manufacturers investing in green formulations that meet stringent regulatory standards.
- Technological advancements in additive formulations will allow for improved stability, solubility, and efficacy, contributing to more efficient fertilizer solutions.
- As environmental regulations become more rigorous, the demand for additives that enhance compliance, such as dust suppressors and stabilizers, is expected to grow.
- Companies are likely to form partnerships and collaborations to expand their market presence, particularly in regions with high agricultural demand.
- Increased R&D investment will drive innovation in fertilizer additives, leading to more tailored solutions that cater to specific crop and soil requirements, supporting the market’s long-term growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Global Demand for Food Production
The need to feed a rapidly increasing global population is driving agricultural producers to maximize crop yields, making fertilizer additives essential for enhancing fertilizer efficiency and minimizing nutrient loss. This directly boosts demand for additives that help optimize fertilizer performance and support higher food output.
Emphasis on Sustainable Agricultural Practices
Farmers and regulators are prioritizing sustainable agriculture, which requires fertilizers that minimize environmental impact. Fertilizer additives that reduce nutrient runoff, improve nutrient uptake, and lower ecological footprints are increasingly adopted to comply with sustainability goals and regulations.
Technological Advancements in Fertilizer Formulation
Innovations in additive technologies, such as slow-release agents and stabilizers, are enabling more precise and efficient nutrient delivery. These advancements support precision agriculture and allow for higher yields with fewer resources, driving adoption of advanced fertilizer additives.
Stringent Regulations on Fertilizer Quality and Environmental Safety
Tighter regulations in regions like North America and Europe require fertilizers to meet high standards for quality and environmental safety. This compels manufacturers to incorporate additives that improve product stability, reduce emissions, and ensure compliance, thereby increasing market demand.
Adoption of Precision Agriculture
The rise of precision agriculture practices is increasing the need for specialized fertilizer additives that enable site-specific nutrient management and controlled nutrient release. This trend is fueling demand for additives that enhance nutrient efficiency and support modern farming techniques.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Fertilizer Additives Market in 2023 and 2032, and what is the expected CAGR?
What are the main drivers of growth in the Fertilizer Additives Market?
Which regions dominate the Fertilizer Additives Market, and why?
How do fertilizer additives contribute to sustainable agriculture?
What are the primary challenges facing the Fertilizer Additives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Anticaking Agents
- 1.2.2 Dust Suppressors
- 1.2.3 Drying Agents
- 1.2.4 Granulating Agents
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Nitrogen
- 1.3.2 Phosphorous Pentoxide
- 1.3.3 Potassium Oxide
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 3,718.89 million → 2032: USD 4,460.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fertilizer Additives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fertilizer Additives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fertilizer Additives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fertilizer Additives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fertilizer Additives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fertilizer Additives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fertilizer Additives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fertilizer Additives Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 3,718.89 million → 2032: USD 4,460.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fertilizer Additives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Anticaking Agents
- 12.3.7.2 Dust Suppressors
- 12.3.7.3 Drying Agents
- 12.3.7.4 Granulating Agents
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Nitrogen
- 12.4.7.2 Phosphorous Pentoxide
- 12.4.7.3 Potassium Oxide
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fertilizer Additives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fertilizer Additives Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fertilizer Additives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fertilizer Additives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arkema S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Clariant AG
- 18.4 Timac Agro USA
- 18.5 ArrMaz
- 18.6 Dorf Ketal
- 18.7 Fertibon Products Pvt. Ltd.
- 18.8 Chemipol S.A.
- 18.9 Neelam Aqua & Speciality Chem (P) Ltd.
- 18.10 Hubei Forbon Technology Co. Ltd.
- 18.11 Michelman Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

