
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| floor grinding machines market Size 2024 | USD 294.3 million |
| floor grinding machines market, CAGR | 4.3% |
| floor grinding machines market Size 2032 | USD 412.15 million |
Market Overview:
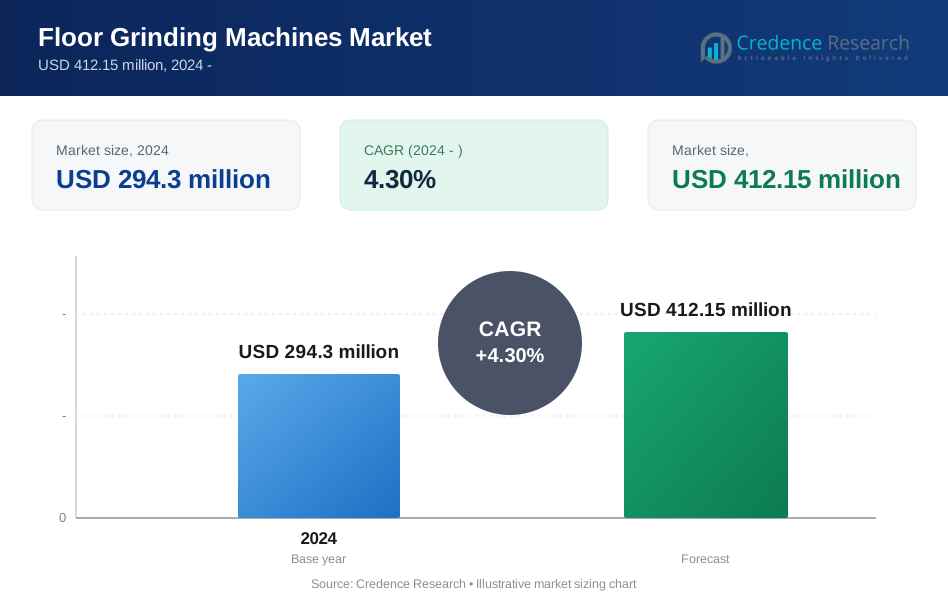
The global floor grinding machines market is projected to grow from USD 294.3 million in 2024 to USD 412.15 million by 2032, at a CAGR of 4.3%. Floor grinding machines are essential for polishing, cleaning, and refurbishing surfaces in commercial, residential, and industrial spaces. Increasing demand for renovation and remodelling, along with advancements in polished concrete flooring, is driving growth. Expanding construction activities and infrastructure projects globally, especially in emerging economies, also contribute to market expansion.
Key market drivers include the rising preference for polished concrete surfaces due to their durability, aesthetics, and low maintenance needs, as well as a growing focus on sustainable building practices. Technological advancements, such as automated and remote-controlled grinders, have further enhanced demand by offering efficiency and precision. The popularity of decorative and polished concrete floors in commercial spaces, including retail and hospitality, is also boosting market growth.
Regionally, North America holds a significant share due to its high demand for concrete renovation and flooring projects in commercial and industrial sectors. Europe follows closely, driven by renovation trends and increasing demand for polished concrete in retail spaces. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth, spurred by rapid urbanization and expanding construction activities in countries such as China and India. This growth reflects the region’s rising focus on durable and aesthetically appealing flooring solutions in residential, commercial, and industrial applications.
Market Drivers:
Increasing Demand for Polished Concrete Surfaces:
The growing preference for polished concrete surfaces in commercial and residential applications is a major driver of the floor grinding machines market. Polished concrete is durable, low-maintenance, and aesthetically pleasing, making it popular in spaces like retail stores, hotels, and corporate offices. For instance, Polished concrete floors demonstrate superior slip resistance with wet DCOF measurements of 0.50 and higher, exceeding the minimum requirement of 0.42 for ceramic floors. The National Floor Safety Institute reports that slip and fall accidents result in over 8 million emergency room visits annually, with financial impacts exceeding $80 billion per year. A 2023 survey by the National Floor Safety Institute reported that over 60% of commercial facilities prefer polished concrete due to its slip resistance and durability, further driving demand for floor grinding machines used in surface preparation.
Expansion in Renovation and Remodelling Activities:
Rising renovation and remodelling activities across developed and emerging markets also fuel demand for floor grinding machines. The U.S. Census Bureau indicated a 15% increase in residential renovation spending in 2022, attributed to aging infrastructure and a growing focus on modernizing spaces. For instance, the home renovation industry has surpassed $400 billion, with homeowners spending $463 billion on renovations in Q1 2024. These projects often require floor refinishing and polishing, supporting the use of floor grinding machines for removing old surfaces, leveling floors, and achieving high-quality finishes in both commercial and residential buildings.
Focus on Sustainable Building Practices:
Sustainable construction practices that emphasize long-lasting and energy-efficient materials further contribute to market growth. Concrete floors, in particular, are recognized for their eco-friendly benefits, as they require fewer resources to maintain and often use recycled materials. The World Green Building Council noted that polished concrete can reduce a building's cooling costs by up to 10%, attracting builders aiming for energy-efficient projects. Floor grinding machines, essential in preparing and maintaining these surfaces, thus see rising demand within sustainable building initiatives.
Advancements in Grinding Technology:
Technological advancements, such as the development of remote-controlled and automated floor grinding machines, enhance efficiency and precision, contributing to their increased adoption. Companies like Husqvarna and HTC have introduced advanced models with enhanced dust collection systems and variable-speed control, allowing operators to work more effectively in large commercial spaces. A 2023 industry survey found that over 70% of contractors prioritize technology-driven equipment to improve productivity and meet client expectations, reflecting the value placed on innovation in floor grinding machinery.
Market Trends:
Growth in Remote-Controlled and Automated Machines:
A prominent trend in the floor grinding machines market is the shift toward remote-controlled and automated machines, which offer enhanced precision and operational efficiency. These machines allow operators to cover larger areas with reduced effort, making them ideal for commercial and industrial applications. For instance, companies like HTC and Husqvarna have introduced models with smart navigation and remote capabilities, enabling operators to monitor the process from a distance, a feature valued in large-scale projects like warehouses and retail centers.
Demand for Dust-Free Grinding Solutions:
Health and safety regulations and growing awareness around indoor air quality are driving demand for dust-free grinding solutions. To comply with standards set by OSHA, many contractors prioritize equipment with advanced dust collection systems to minimize exposure to silica dust, which can pose health risks. For example, a 2022 survey by the Construction Safety Council found that 75% of contractors in the U.S. now use dust-control systems on job sites, reflecting a commitment to safe and compliant practices in floor grinding.
Rise of Environmentally Friendly and Energy-Efficient Machines:
The trend toward environmentally friendly and energy-efficient machinery is gaining traction as construction companies seek sustainable solutions. Floor grinding machines with energy-efficient motors and reduced water consumption contribute to greener building practices. Husqvarna recently launched an eco-friendly model designed to consume up to 30% less power without compromising on performance. This shift supports the goals of the World Green Building Council, which promotes low-impact building solutions across the industry.
Increasing Popularity of Multi-Purpose Floor Grinders:
Multi-purpose floor grinding machines, capable of grinding, polishing, and surface preparation, are becoming more popular due to their versatility and cost-efficiency. Contractors benefit from machines that can handle different flooring materials and project requirements, eliminating the need to invest in multiple machines. For example, Blastrac has developed multi-functional models that allow contractors to transition seamlessly from grinding to polishing, which is particularly valuable for commercial spaces that require multiple finishes in a single project.
Market Challenges Analysis:
High Initial Costs and Maintenance Expenses:
The high initial cost of floor grinding machines is a significant restraint, particularly for smaller contractors and businesses. Advanced models, such as remote-controlled or dust-free systems, are priced substantially higher due to their sophisticated technology and features. This cost can be prohibitive for companies with limited budgets. The U.S. Small Business Administration notes that capital investment constraints often limit small enterprises from acquiring high-tech machinery, impacting their competitiveness and efficiency.
Complexity in Handling and Training Requirements:
Operating floor grinding machines requires specific skills and knowledge, which can create challenges, especially with technologically advanced models. The National Institute for Occupational Safety and Health (NIOSH) reports that improper handling of heavy machinery, like floor grinders, can lead to safety risks on-site. As these machines become more complex, contractors face additional expenses in training personnel to operate them safely and effectively, which can impact productivity and increase operational costs.
Regulatory Compliance for Dust Control:
Strict dust control regulations, particularly from authorities like OSHA in the United States, add compliance pressure. OSHA’s standards for silica dust exposure require contractors to use dust-free grinding systems to protect workers' health. Compliance involves additional expenses for contractors who must either upgrade to dust-controlled machines or invest in supplementary equipment. This regulatory requirement, while beneficial for health, adds to operational costs for companies.
Limited Awareness and Demand in Emerging Regions:
Limited awareness of floor grinding machines' benefits in emerging markets poses a barrier to broader market penetration. In regions where traditional flooring methods are predominant, the adoption of advanced grinding technology is slower. The World Bank highlights that limited access to modern construction technology in certain regions limits the uptake of high-quality grinding solutions, slowing market expansion across developing economies.
Market Segmentation Analysis:
By Type
The floor grinding machines market is segmented by type into single-disc, dual-disc, and planetary grinders. Single-disc grinders are often used for small to medium projects due to their straightforward operation and affordability, making them popular in residential settings. Dual-disc grinders, designed for larger areas, offer higher efficiency and are ideal for commercial applications. Planetary grinders, equipped with multiple rotating discs, provide superior polishing and finishing, catering to high-demand sectors like retail and hospitality.
By Technology
By technology, the market is divided into manual, remote-controlled, and autonomous machines. Manual grinders remain widely used due to their lower cost and simpler operation. Remote-controlled machines are gaining traction, particularly in large-scale commercial projects, as they offer enhanced precision and reduce operator fatigue. Autonomous machines, while limited in availability, represent a growing trend towards automation and efficiency, particularly in expansive commercial or industrial spaces.
By End User
The end-user segment includes residential, commercial, and industrial sectors. The commercial segment holds the largest market share, driven by the high demand for polished concrete in spaces such as shopping malls, airports, and offices. The industrial segment also shows steady demand, particularly for durable, easy-to-maintain flooring in factories and warehouses. The residential sector, while smaller, is expanding as homeowners increasingly favor polished concrete for its durability and aesthetic appeal.
Segmentations:
Type
- Single Disc
- Triple Disc
- Quad Disc
Application
- Marble & Limestone
- Wood
- Concrete
- Granite
- Others
End-Use Industry
- Residential
- Commercial
- Industrial
Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the floor grinding machines market, accounting for approximately 35% of the global market share. This is due to extensive construction and renovation activities across commercial, industrial, and residential sectors in the United States and Canada. The U.S. leads the region’s demand, driven by significant investment in infrastructure development and a high adoption rate of polished concrete surfaces. Additionally, the popularity of sustainable construction practices fuels demand for floor grinding machines, as polished concrete is valued for its durability and low maintenance, aligning with the region’s focus on energy-efficient building practices.
Europe
Europe follows closely with around 30% of the market share, supported by an established commercial construction sector and renovation trends in countries such as Germany, the UK, and France. The European Union’s strict environmental regulations and growing interest in sustainable construction practices boost the demand for floor grinding machines. Polished concrete is particularly favored in retail spaces and high-traffic public areas due to its low environmental impact and aesthetic appeal. Technological advancements in automation and dust control systems, introduced by European manufacturers, further enhance the market by addressing health and safety standards.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth, capturing about 25% of the market share. Rapid urbanization and industrialization in countries like China, India, and Japan drive the demand for floor grinding machines, as these countries invest heavily in infrastructure and commercial real estate. China, being the largest construction market in the region, leads in the adoption of advanced grinding technologies for large-scale projects. Moreover, the rise in high-end retail spaces, shopping malls, and hospitality venues across Asia-Pacific bolsters demand for polished concrete and surface refinement, fueling the need for efficient floor grinding equipment.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively hold around 10% of the global floor grinding machines market. In Latin America, Brazil and Mexico lead, supported by expanding infrastructure projects and a growing focus on modernizing commercial spaces. In the Middle East, high-end infrastructure developments and luxury commercial spaces in the UAE and Saudi Arabia contribute to the demand for polished concrete and, consequently, floor grinding machines. Africa’s market, while smaller, is expected to grow as urbanization and construction activities increase, particularly in South Africa and Nigeria. Overall, these regions are gradually adopting advanced grinding solutions as modernization efforts continue.
Key Player Analysis:
- Husqvarna Group
- HTC Group
- Blastrac
- Klindex
- SASE Company
- National Flooring Equipment
- Superabrasive Inc.
- Schwamborn GmbH
- LAVINA
- Bartell Global
Competitive Analysis:
The floor grinding machines market is highly competitive, with key players like Husqvarna Group, HTC Group, and Blastrac leading through advanced technology and product range. These companies focus on innovations such as remote-controlled and dust-free machines to enhance operator efficiency and comply with health regulations. Emerging players like Superabrasive Inc. and SASE Company contribute to the market with versatile, multi-functional machines suitable for various flooring applications. Established players maintain a competitive edge through strong distribution networks and partnerships with construction firms, allowing them to cater to both large-scale and specialized projects globally.
Recent Developments:
- Husqvarna Construction expanded its product lineup in 2023 by integrating Blastrac’s surface preparation equipment, including scrapers, scarifiers, and heavy-duty grinders, into the Husqvarna brand. This consolidation enhances Husqvarna’s offerings and strengthens its position as a comprehensive provider for surface preparation solutions, meeting the demands of large-scale industrial and commercial projects.
- In 2024, Husqvarna introduced its new ride-on grinder, the BMG 1500, designed for extensive floor grinding projects. This machine features joystick controls, an advanced dust collection system, and a pre-separator, aimed at improving operator efficiency and providing dust-free grinding for larger areas.
- HTC Group launched the DURATIQ 5, a compact but powerful floor grinder, in 2023. This addition to HTC’s DURATIQ line offers enhanced precision and control, making it suitable for high-demand applications that require fine-tuned grinding capabilities in confined spaces.
- In 2022, Blastrac expanded its product line with high-performance dust extraction systems specifically designed to comply with OSHA standards for dust control. This development addresses growing health and safety concerns in construction environments and provides contractors with efficient, safe dust management solutions during grinding and polishing.
Market Concentration & Characteristics:
The floor grinding machines market is moderately concentrated, with a few key players such as Husqvarna Group, HTC Group, and Blastrac dominating due to their extensive product ranges, advanced technologies, and established global presence. These leaders drive market growth through continuous innovation, including remote-controlled and dust-free grinding systems that meet regulatory standards and enhance operational efficiency. High entry barriers, such as the need for significant R&D investment and advanced manufacturing capabilities, contribute to the market’s concentration, limiting new entrants. Additionally, companies like Superabrasive Inc. and Klindex focus on multi-functional and high-performance machines, catering to both specialized and large-scale projects. This competitive landscape is characterized by strong distribution networks, product versatility, and a focus on sustainability, with major players enhancing dust control systems to comply with health regulations and meet contractor demand for safe, efficient surface preparation solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-Use Industry, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for floor grinding machines will increase as infrastructure and construction projects grow worldwide, particularly in emerging economies focused on urbanization.
- Technological advancements, including remote-controlled and automated machines, will drive adoption by improving operational efficiency and reducing operator fatigue.
- Emphasis on sustainable construction will boost demand for energy-efficient grinding machines, as companies prioritize eco-friendly options in their projects.
- Enhanced dust-control systems will become standard, driven by strict regulations on dust exposure and growing awareness of health and safety standards.
- Multi-functional floor grinders that can handle grinding, polishing, and surface preparation will gain popularity, especially among contractors seeking cost-effective, versatile solutions.
- The commercial sector will remain the largest end user, with demand for polished concrete in high-traffic spaces like airports, malls, and hotels.
- Integration of IoT and smart technology in floor grinding machines will enable real-time monitoring and predictive maintenance, improving equipment longevity and performance.
- Growth in residential renovations will support the demand for compact and user-friendly floor grinders suitable for smaller spaces.
- Partnerships between manufacturers and contractors are expected to grow, facilitating tailored solutions that meet the specific requirements of large-scale projects.
- Expansion of aftermarket services, including rental options and maintenance packages, will appeal to smaller businesses seeking flexible and affordable access to advanced equipment.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Polished Concrete Surfaces
The preference for polished concrete in commercial and residential spaces is rising due to its durability, low maintenance, and aesthetic appeal. This trend is driving the adoption of floor grinding machines, which are essential for preparing and finishing polished concrete surfaces.
Expansion in Renovation and Remodelling Activities
Growing renovation and remodelling projects, especially in developed markets, require floor refinishing and surface preparation, boosting demand for floor grinding machines. The surge in home and commercial renovations directly supports market growth.
Focus on Sustainable Building Practices
Sustainable construction trends favor materials like polished concrete, which are energy-efficient and environmentally friendly. Floor grinding machines are critical for preparing these surfaces, aligning with green building initiatives and increasing their market demand.
Advancements in Grinding Technology
Technological innovations such as remote-controlled and automated floor grinders enhance efficiency, precision, and safety. These advancements make floor grinding machines more attractive for large-scale and high-specification projects, accelerating market adoption.
Stricter Health and Safety Regulations
Regulations around dust control and worker safety, particularly in developed regions, are pushing contractors to invest in advanced floor grinding machines with dust-free and compliant features, thereby driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Floor Grinding Machines Market?
What factors are driving the growth of the Floor Grinding Machines Market?
What are some challenges faced by the Floor Grinding Machines Market?
Who are the major players in the Floor Grinding Machines Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Single Disc
- 1.2.2 Triple Disc
- 1.2.3 Quad Disc
- 1.3 By Technology
- 1.3.1 Manual
- 1.3.2 Remote-Controlled
- 1.3.3 Autonomous
- 1.4 By Application
- 1.4.1 Marble & Limestone
- 1.4.2 Wood
- 1.4.3 Concrete
- 1.4.4 Granite
- 1.4.5 Others
- 1.5 By End-Use Industry
- 1.5.1 Residential
- 1.5.2 Commercial
- 1.5.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 294.3 million → 2032: USD 412.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Floor Grinding Machines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Floor Grinding Machines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Floor Grinding Machines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Floor Grinding Machines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Floor Grinding Machines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Floor Grinding Machines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Floor Grinding Machines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Floor Grinding Machines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 294.3 million → 2032: USD 412.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Floor Grinding Machines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single Disc
- 12.3.7.2 Triple Disc
- 12.3.7.3 Quad Disc
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Manual
- 12.4.7.2 Remote-Controlled
- 12.4.7.3 Autonomous
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Marble & Limestone
- 12.5.7.2 Wood
- 12.5.7.3 Concrete
- 12.5.7.4 Granite
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Residential
- 12.6.7.2 Commercial
- 12.6.7.3 Industrial
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Floor Grinding Machines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Floor Grinding Machines Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Floor Grinding Machines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Floor Grinding Machines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Husqvarna Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 HTC Group
- 18.4 Blastrac
- 18.5 Klindex
- 18.6 SASE Company
- 18.7 National Flooring Equipment
- 18.8 Superabrasive Inc.
- 18.9 Schwamborn GmbH
- 18.10 LAVINA
- 18.11 Bartell Global
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

