
Food Additive Market Overview:
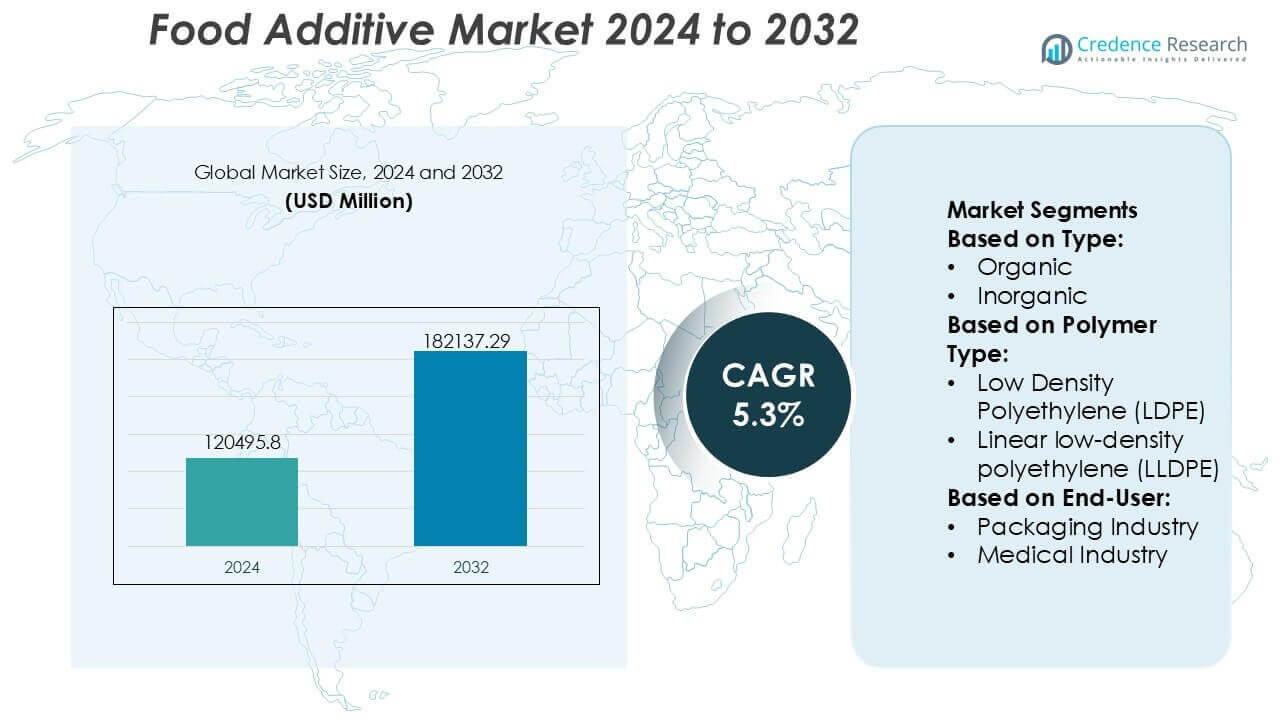
Food Additive Market size was valued USD 120495.8 million in 2024 and is anticipated to reach USD 182137.29 million by 2032, at a CAGR of 5.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Additive Market Size 2024 | USD 120495.8 million |
| Food Additive Market, CAGR | 5.3% |
| Food Additive Market Size 2032 | USD 182137.29 million |
Food Additive Market Insights
- Market growth is primarily driven by increasing consumption of convenience foods, longer shelf-life requirements, and strong demand for functional ingredients, with preservatives and sweeteners together accounting for nearly 40% of total segment share.
- Key market trends include rapid adoption of clean-label additives, fermentation-derived ingredients, and plant-based colorants, alongside growing R&D focus on multifunctional additives that reduce formulation complexity.
- The competitive landscape is moderately consolidated, with leading players leveraging broad portfolios, application expertise, and long-term partnerships with food manufacturers to strengthen pricing power and global reach.
- Regionally, Asia-Pacific dominates with an exact 35% market share, driven by large-scale food processing in China and India, while Europe follows due to strict food safety regulations and high adoption of natural additives.
Food Additive Market Segmentation Analysis:
By Type
The food additive market, by type, is segmented into organic and inorganic additives, with organic additives dominating with an estimated 62% market share. This dominance is driven by strong consumer preference for clean-label, plant-derived, and minimally processed ingredients across food and beverage applications. Organic additives such as natural preservatives, colorants, and flavor enhancers benefit from regulatory support and rising health awareness. Food manufacturers increasingly adopt organic acids, enzymes, and botanical extracts to improve shelf life while maintaining label transparency. In contrast, inorganic additives retain relevance in cost-sensitive applications but face gradual substitution due to tightening regulations and sustainability considerations.
- For instance, Givaudan has expanded its naturals platform through controlled fermentation and extraction technologies, operating industrial fermentation vessels exceeding 10,000-liter batch capacity and developing hundreds of distinct natural flavor and color molecules through bioconversion and enzymatic processes, enabling consistent performance without reliance on synthetic additives.
By Polymer Type
By polymer type, Low Density Polyethylene (LDPE) leads the segment with approximately 28% market share, owing to its flexibility, moisture resistance, and compatibility with food-grade additive incorporation. LDPE is widely used in films and coatings where additives enhance barrier properties, thermal stability, and processing efficiency. Linear low-density polyethylene (LLDPE) follows closely, supported by its superior tensile strength and puncture resistance. Demand for BOPP and HDPE is also growing, driven by lightweight packaging trends, while PVC usage remains limited due to regulatory and environmental scrutiny in food contact applications.
- For instance, Cargill has advanced polymer-compatible food additive delivery by developing lipid-based carrier systems processed through industrial spray-cooling lines exceeding 6,000 kilograms per hour, enabling uniform dispersion of antioxidants and stabilizers in polyethylene films while maintaining thermal stability at processing temperatures above 180 °C.
By End-User
The end-user segment is led by the packaging industry, accounting for nearly 45% of total market share, supported by high demand for additives that improve durability, safety, and shelf life of packaged foods. Additives such as antioxidants, antimicrobials, and stabilizers play a critical role in maintaining food quality during storage and transportation. The medical industry represents a smaller but growing segment, driven by strict hygiene requirements and specialized food formulations. Automotive and other industries contribute marginally, mainly through indirect food-grade material handling and ancillary packaging applications.
Key Growth Drivers
Rising Demand for Processed and Convenience Foods
The food additive market is strongly driven by the global increase in consumption of processed, packaged, and convenience foods. Urbanization, busy lifestyles, and rising disposable incomes have increased reliance on ready-to-eat meals, bakery products, beverages, and snacks that require additives for shelf-life extension, texture stability, and flavor consistency. Preservatives, emulsifiers, stabilizers, and flavor enhancers play a critical role in maintaining product quality during storage and long-distance distribution. This demand is especially pronounced in emerging economies, where modern retail expansion and changing dietary patterns are accelerating packaged food adoption.
- For instance, Ajinomoto has strengthened this demand driver through large-scale amino-acid fermentation technologies, operating production facilities capable of manufacturing over 1 million metric tons of amino acids annually and utilizing continuous fermentation tanks exceeding 500 cubic meters, enabling high-purity flavor enhancers and texture-improving ingredients with consistent performance in processed and convenience food formulations.
Expansion of the Food and Beverage Industry
Continuous expansion of the global food and beverage industry is a major growth driver for food additives. Manufacturers increasingly use additives to improve processing efficiency, product appearance, taste uniformity, and cost optimization across large production volumes. Additives support innovation in dairy alternatives, functional beverages, confectionery, and savory foods by enabling controlled formulations and scalable production. Growth in foodservice chains and private-label brands further reinforces additive demand, as consistency and regulatory compliance are critical for brand reputation and cross-regional product standardization.
- For instance, BASF has strengthened additive supply for food applications through advanced vitamin and carotenoid production, operating dedicated facilities with single-reactor batch capacities exceeding 200 cubic meters and producing thousands of metric tons of food-grade vitamins annually, supported by analytical quality control systems capable of testing more than 100 individual specification parameters per batch to ensure consistency and compliance.
Increasing Focus on Food Safety and Shelf-Life Enhancement
Heightened awareness of food safety and reduction of food waste significantly supports the food additive market. Additives such as antioxidants, antimicrobials, and acidity regulators help inhibit microbial growth and oxidation, extending shelf life while preserving nutritional and sensory attributes. Governments and food producers are emphasizing supply chain efficiency and waste reduction, particularly for perishable products. As global food trade expands, additives become essential to ensure product stability across varied climatic conditions, transportation durations, and storage environments, reinforcing their role in modern food systems.
Key Trends & Opportunities
Shift Toward Clean-Label and Natural Additives
A major trend shaping the food additive market is the shift toward clean-label formulations and naturally derived ingredients. Consumers increasingly prefer recognizable, minimally processed additives sourced from plants, fermentation, or natural extracts. This trend is driving innovation in natural colors, flavors, sweeteners, and preservatives that can replace synthetic counterparts without compromising performance. Manufacturers are investing in advanced extraction and formulation technologies to achieve functional equivalence, creating strong opportunities for suppliers offering transparent labeling and nature-based additive solutions.
- For instance, Ingredion has expanded its clean-label portfolio through proprietary starch and stevia processing platforms, operating wet-milling facilities capable of processing more than 15,000 metric tons of corn per day and deploying high-purity stevia purification systems that achieve steviol glycoside concentrations above 95 grams per 100 grams, supporting consistent performance in reduced-sugar and naturally positioned food formulations.
Growth of Functional and Health-Oriented Food Products
Rising consumer interest in health, wellness, and preventive nutrition presents significant opportunities for food additives. Functional additives such as fortification minerals, vitamins, probiotics, and specialty fibers are increasingly incorporated into everyday foods and beverages. Additives also support sugar reduction, fat replacement, and sodium management strategies without sacrificing taste or texture. This trend aligns with growing demand for fortified foods, sports nutrition, and specialized dietary products, positioning functional additives as a key enabler of value-added food innovation.
- For instance, International Flavors & Fragrances has expanded functional nutrition through its HOWARU probiotic platform, producing clinically documented strains delivered at 10,000,000,000 colony-forming units per serving, supported by large-scale fermentation systems with bioreactor volumes exceeding 100,000 liters, enabling consistent, high-viability probiotic integration into functional dairy, beverage, and nutrition formulations.
Technological Advancements in Food Processing
Advancements in food processing and formulation technologies are creating new opportunities for the food additive market. Improved encapsulation, controlled release systems, and precision blending enhance additive stability and performance under complex processing conditions. These technologies allow manufacturers to optimize dosage, improve bioavailability, and maintain sensory quality throughout a product’s lifecycle. As automation and digital process control expand in food manufacturing, demand grows for high-performance additives that integrate seamlessly into advanced production environments.
Key Challenges
Stringent Regulatory Frameworks and Compliance Costs
The food additive market faces challenges from complex and evolving regulatory frameworks across regions. Approval processes, usage limits, and labeling requirements vary significantly between countries, increasing compliance complexity for manufacturers operating globally. Frequent regulatory updates and safety reassessments can delay product launches and raise development costs. Smaller additive producers often face barriers due to high testing, documentation, and certification expenses, while multinational companies must continuously adapt formulations to meet region-specific standards.
Consumer Skepticism Toward Synthetic Additives
Despite their functional benefits, synthetic food additives continue to face consumer skepticism related to perceived health risks and artificiality. Negative perceptions can influence purchasing decisions and push food manufacturers to reformulate products, sometimes at higher costs or with performance trade-offs. Managing this challenge requires transparent communication, reformulation investments, and education on additive safety and functionality. The need to balance consumer expectations with cost efficiency and product stability remains a persistent challenge for the food additive market.
Regional Analysis
North America
North America dominates the food additive market with an estimated 38% market share, supported by a highly developed food processing industry and strong demand for packaged, convenience, and functional foods. The region benefits from advanced R&D capabilities, high adoption of clean-label and natural additives, and stringent food safety regulations that drive innovation in compliant formulations. Manufacturers increasingly invest in sugar reduction, natural colorants, and preservative alternatives to meet evolving consumer preferences. The United States leads regional consumption, while Canada contributes through growing demand for organic and fortified food products across retail and foodservice channels.
Europe
Europe holds approximately 29% of the global food additive market, driven by strict regulatory oversight, strong consumer awareness, and widespread adoption of clean-label formulations. Demand is particularly strong for natural flavors, emulsifiers, and colorants, supported by mature bakery, dairy, and confectionery industries. The region emphasizes sustainability, traceability, and reduced synthetic ingredient usage, encouraging innovation in plant-based and bio-derived additives. Countries such as Germany, France, and the United Kingdom lead consumption, while Southern Europe contributes through processed meat, beverage, and specialty food segments that require advanced stabilizers and preservatives.
Asia-Pacific
Asia-Pacific accounts for nearly 24% market share and represents the fastest-growing regional market due to rapid urbanization, rising disposable incomes, and expanding processed food consumption. Growth is fueled by strong demand for flavor enhancers, sweeteners, and shelf-life extenders across packaged snacks, instant foods, and beverages. China and India lead regional demand, supported by large populations and expanding food manufacturing bases. Additionally, increasing adoption of Western dietary patterns and improving cold-chain infrastructure further boost additive usage, while local producers scale production to meet cost-sensitive, high-volume demand.
Latin America
Latin America holds around 6% of the global food additive market, supported by steady growth in packaged food and beverage consumption. The region shows strong demand for preservatives, colorants, and flavorings used in bakery, dairy, and processed meat applications. Brazil and Mexico dominate regional consumption due to their large food processing industries and expanding retail networks. While price sensitivity remains a challenge, rising urban populations and improving regulatory harmonization are encouraging greater adoption of standardized food additives. Local manufacturers increasingly focus on cost-efficient formulations tailored to regional taste preferences and climatic storage requirements.
Middle East & Africa
The Middle East & Africa region accounts for approximately 3% market share, driven by growing demand for packaged and shelf-stable foods in urban centers. Expansion of modern retail, rising tourism, and increasing food imports support additive consumption, particularly preservatives, stabilizers, and flavor systems. Gulf Cooperation Council countries lead regional demand due to high per-capita food consumption and reliance on processed imports, while Africa shows gradual growth through expanding food manufacturing in South Africa and North Africa. However, limited local production capacity and regulatory variability continue to restrain faster market expansion.
Food Additive Market Segmentations:
By Type:
- Organic
- Inorganic
By Polymer Type:
- Low Density Polyethylene (LDPE)
- Linear low-density polyethylene (LLDPE)
By End-User:
- Packaging Industry
- Medical Industry
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the food additive market players such as Givaudan, Cargill, Incorporated, Ajinomoto Co., Inc., BASF SE, Ingredion, International Flavors & Fragrances Inc. (IFF), Biospringer, Tate & Lyle Plc, DSM, ADM. the food additive market is characterized by a mix of multinational ingredient producers and specialized solution providers competing on innovation, scale, and application performance. Companies differentiate through broad product portfolios that address taste, texture, shelf life, and nutritional enhancement across diverse food and beverage applications. Competition increasingly emphasizes clean-label, natural, and functional additives, supported by investments in advanced processing, fermentation, and enzyme technologies. Strong R&D capabilities enable rapid customization and co-development with food manufacturers, strengthening long-term customer relationships. In addition, players focus on operational efficiency, supply-chain resilience, and compliance with evolving food safety and labeling regulations across regions. Strategic capacity expansions, sustainability-driven product development, and deeper penetration into emerging markets further shape competitive dynamics. Overall, technological expertise, regulatory know-how, and the ability to deliver consistent quality at scale remain the primary factors influencing competitive positioning in the food additive market.
Key Player Analysis
- Givaudan
- Cargill, Incorporated
- Ajinomoto Co., Inc.
- BASF SE
- Ingredion
- International Flavors & Fragrances Inc. (IFF)
- Biospringer
- Tate & Lyle Plc
- DSM
- ADM
Recent Developments
- In April 2025, Godrej Industries' chemicals business acquired the food additives business of Savannah Surfactants. The Savannah business will be part of the specialty chemicals sector. The addition of this food additives business will expand our specialty offerings and build a larger specialty business going forward.
- In March 2025, Cargill opened a new corn milling plant in Gwalior, Madhya Pradesh, operated by Indian manufacturer Saatvik Agro Processors, to meet increasing demand from India's confectionery, infant formula, and dairy industries.
- In June 2024, Azelis, a leading innovation service provider in the specialty chemicals and food ingredients sector, announced a new distribution agreement with Tate & Lyle. This partnership offers healthier ingredient solutions for food and beverages, targeting customers in Türkiye.
Report Coverage
The research report offers an in-depth analysis based on Type, Polymer Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Food Additive Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Additive Market projected to grow between 2024 and 2032?
Which Food Additive Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Additive Market?
Who are the leading companies in the Food Additive Market?
Which region commanded the largest share of the Food Additive Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 120,495.8 million → 2032: USD 182,137.29 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Additives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Additives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Additives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Additives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Additives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Additives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Additives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Additives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 120,495.8 million → 2032: USD 182,137.29 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Additives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Additives Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Food Additives Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Food Additives Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

