
Market Overview
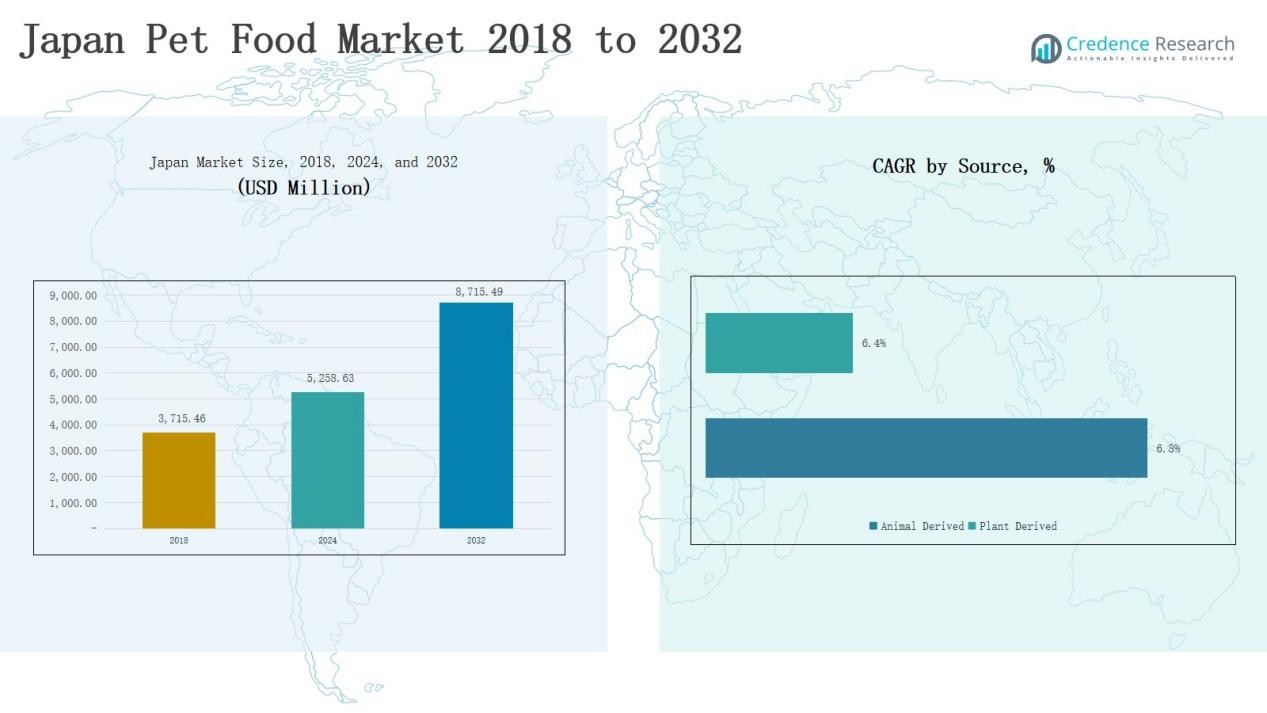
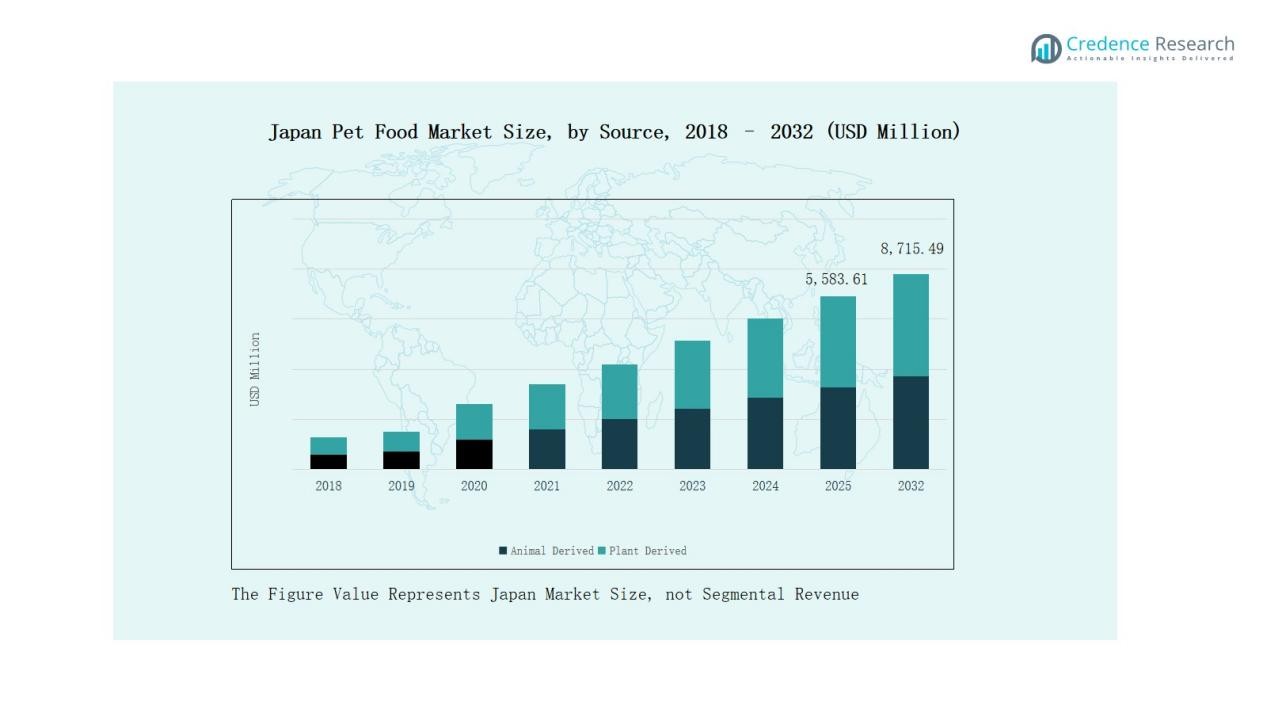
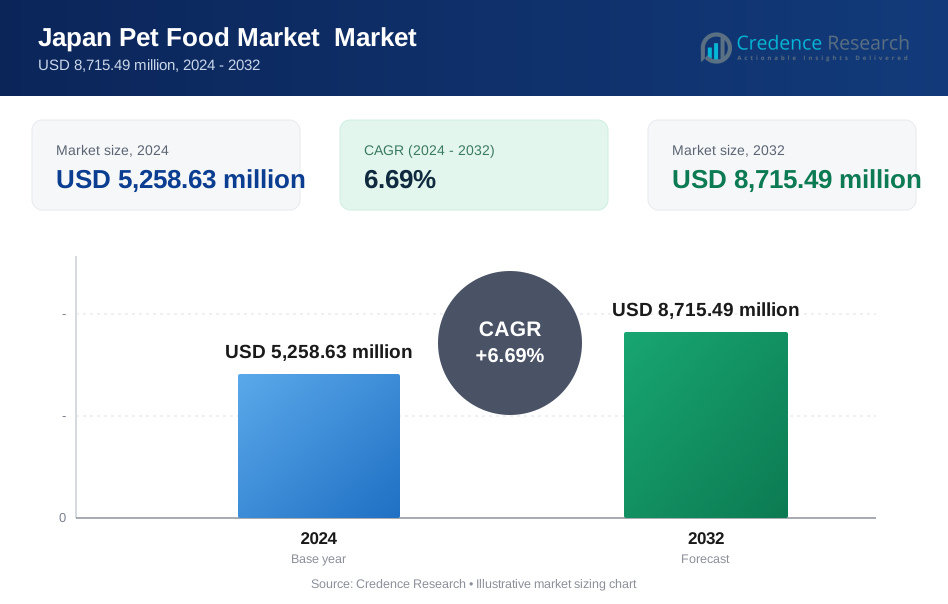
The Japan Pet Food Market was valued at USD 3,715.46 million in 2018, increased to USD 5,258.63 million in 2024, and is expected to reach USD 8,715.49 million by 2032, growing at a CAGR of 6.69% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Japan Pet Food Market Size 2024 | USD 5,258.63 Million |
| Japan Pet Food Market, CAGR | 6.69% |
| Japan Pet Food Market Size 2032 | USD 8,715.49 Million |
The Japan Pet Food Market is led by prominent companies including Unicharm Corporation, Mars, Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition, General Mills, Inc., and NIPPON PET FOOD CO., LTD. These players maintain dominance through product innovation, strong brand portfolios, and extensive retail and online distribution. Their focus on premium, functional, and breed-specific formulations enhances consumer loyalty and market competitiveness. Strategic collaborations with e-commerce platforms and investments in sustainable packaging strengthen brand positioning. The Kanto region leads the market with a 36% share in 2024, driven by high urbanization, strong purchasing power, and the presence of major manufacturers and distributors.
Market Insights
- The Japan Pet Food Market grew from USD 3,715.46 million in 2018 to USD 5,258.63 million in 2024 and is projected to reach USD 8,715.49 million by 2032, expanding at a CAGR of 6.69%.
- Dry pet food led the market with a 47% share in 2024 due to its long shelf life, convenience, and balanced nutrition, appealing strongly to urban and dual-income households.
- Animal-derived products dominated the market with a 64% share, supported by demand for high-protein, meat-based formulations viewed as more natural and nutritious by pet owners.
- The dog segment held the highest share of 52% in 2024, driven by rising dog ownership, premium nutrition demand, and the popularity of small-breed dogs in Japanese urban areas.
- The Kanto region led the market with a 36% share, supported by high urbanization, disposable income, and the presence of key players such as Unicharm, Mars, and Nestlé Purina PetCare.
Market Segment Insights
By Food Type:
Dry pet food dominated the Japan Pet Food Market in 2024 with a 47% share. Its dominance stems from longer shelf life, convenience in storage, and balanced nutritional value. Pet owners prefer dry formulations for easy portion control and reduced spoilage risk. Manufacturers are focusing on high-protein and grain-free variants to meet growing demand for health-focused diets. Increasing urbanization and the rise of dual-income households further drive adoption of dry pet food across Japan’s pet owners.
- For instance, Unicharm introduced the AllWell dry series with 10 essential nutrients targeting adult cats, marketed with resealable packaging for freshness in urban households.
By Source:
The animal-derived segment led the Japan Pet Food Market in 2024, capturing a 64% share. This dominance is due to the preference for protein-rich formulations made from meat, fish, and poultry sources. Consumers view animal-based ingredients as more natural and nutritious for pets. Rising awareness of high-protein diets and strong demand for premium-grade meat-based products sustain growth. Continuous innovations in flavor profiles and digestibility also strengthen the appeal of animal-derived pet food.
- For instance, INABA-PETFOOD Co. Ltd. has been a key player in Japan, focusing on high-protein meat-based recipes that emphasize natural and nutritious ingredients preferred by pet owners for their pets' health.
By Pet Type:
The dog segment accounted for the largest share of 52% in the Japan Pet Food Market in 2024. Rising dog ownership rates and growing preference for specialized nutrition support this trend. Premiumization in dog food-focused on joint health, digestion, and breed-specific formulas-drives market expansion. Increasing adoption of small-breed dogs in urban homes further fuels demand. Manufacturers continue to introduce tailored meal options and functional treats catering to diverse canine dietary needs.
Key Growth Drivers
Rising Pet Humanization and Premiumization
The growing perception of pets as family members fuels premium product demand in Japan. Pet owners increasingly seek high-quality, nutritious, and natural food options. Premium pet food brands emphasize organic ingredients, functional benefits, and human-grade quality. This shift supports market expansion across urban and affluent households. Manufacturers also capitalize on this sentiment by introducing tailored formulations targeting pet health, longevity, and emotional well-being, strengthening brand loyalty and consumer trust within the evolving Japanese pet care landscape.
- For instance, Japan’s ZEN Premium Dog GrainFree Fish uses fresh Japanese sardines and white fish as hypoallergenic ingredients, supported by over 90% domestically sourced materials to ensure quality and food allergy considerations.
Increasing Pet Ownership Among Urban Households
Urbanization and smaller family structures drive higher pet adoption rates in Japan. Single professionals and elderly citizens increasingly adopt pets for companionship, creating consistent food demand. The trend is particularly strong in cities like Tokyo and Osaka, where apartment-friendly pets such as cats and small dogs dominate. Growing awareness of pet nutrition and online product availability enhance accessibility. This urban lifestyle shift continues to create new growth opportunities across retail, online commerce, and specialized pet nutrition categories.
- For instance, PetKonnect is an India-based online pet products and services aggregator that provides a wide array of products and services and sells food from various brands, some of which feature breed-specific formulations, to customers across India.
Expansion of E-commerce and Retail Distribution
The rapid growth of e-commerce platforms has transformed Japan’s pet food distribution landscape. Online sales offer convenience, wider product selection, and subscription-based services for recurring purchases. Leading brands collaborate with digital platforms like Rakuten and Amazon Japan to improve reach and customer engagement. Supermarkets and specialty stores also expand shelf space for premium and functional pet food. The omnichannel retail approach strengthens consumer accessibility and drives steady sales growth across both domestic and international pet food brands.
Key Trends & Opportunities
Growth of Functional and Customized Nutrition
Japanese consumers increasingly favor functional pet food enriched with probiotics, omega-3 fatty acids, and joint-support nutrients. Manufacturers develop breed-specific and age-targeted products addressing health issues such as obesity, allergies, and digestion. Personalized nutrition supported by digital tools and subscription plans enhances customer loyalty. This trend aligns with Japan’s aging pet population, where preventive nutrition and wellness-focused diets present strong opportunities for innovation, differentiation, and sustained market expansion in premium product categories.
- For instance, SquarePet® launched VFS Active Joints dog food, a high-protein diet enriched with natural sources of glucosamine, chondroitin sulfate, and enhanced omega-3 fatty acids DHA & EPA, targeting joint health and mobility in pets.
Shift Toward Sustainable and Ethical Sourcing
Sustainability has emerged as a major opportunity in the Japan Pet Food Market. Consumers are more conscious of ingredient origin, packaging materials, and environmental footprint. Companies respond with eco-friendly packaging, plant-based ingredients, and responsibly sourced animal proteins. Collaborative efforts with sustainability organizations and traceable supply chains enhance transparency. Brands promoting ethical practices gain stronger market preference, aligning with Japan’s growing sustainability goals and consumer emphasis on environmental responsibility in everyday purchasing decisions.
- For instance, Aiken Genki emphasizes nutritional transparency and high-quality natural ingredients, partnering with local veterinarians for expert-backed recommendations, which has built strong consumer trust among health-conscious pet owners.
Key Challenges
High Cost of Premium and Imported Pet Food
Premium pet food prices remain a significant barrier for many Japanese consumers. Imported brands dominate the market but face high import tariffs and distribution costs. Currency fluctuations further increase retail prices, limiting affordability. Local manufacturers struggle to match international quality while maintaining competitive pricing. Balancing cost and quality without compromising nutritional standards remains challenging, particularly in urban markets where consumers demand both premium attributes and accessible price points.
Declining Population and Limited Pet Ownership Growth
Japan’s declining population and aging demographics restrict long-term pet ownership growth. Many elderly individuals hesitate to adopt pets due to health or mobility concerns. Younger generations living in smaller apartments face space and time constraints. This demographic shift slows market expansion despite rising per-pet spending. Industry players must innovate through rental pet services, compact packaging, and low-maintenance nutrition solutions to sustain engagement and counter slower adoption rates in the coming years.
Stringent Regulatory and Safety Compliance
The Japan Pet Food Market faces strict safety and labeling regulations set by the Ministry of Agriculture, Forestry and Fisheries (MAFF). Compliance with ingredient transparency, manufacturing standards, and nutritional claims demands continuous investment. Smaller manufacturers struggle with certification costs and regulatory updates. Frequent product testing and documentation requirements increase operational complexity. While regulations enhance consumer trust, they also limit market entry for emerging brands, creating barriers to competition and innovation in specialized product categories.
Regional Analysis
Kanto Region
The Kanto region dominated the Japan Pet Food Market in 2024 with a 36% share. It remains the center of economic activity and urban living, supporting a dense concentration of pet owners. Rising disposable incomes and smaller household structures drive higher spending on premium and functional pet food. Major cities such as Tokyo and Yokohama record strong demand for dry and wet food variants due to convenience and availability. Retail chains and online platforms expand rapidly in this region. The strong presence of leading manufacturers and distributors continues to strengthen Kanto’s market leadership.
Kansai Region
The Kansai region captured a 24% share of the market in 2024, led by major urban centers including Osaka and Kyoto. Its growing middle-class population and increasing pet adoption support market expansion. Consumers prefer high-quality, protein-rich, and locally sourced pet food. Manufacturers target this region through innovative product packaging and value-added nutrition. Specialty stores and supermarkets account for strong sales growth. It remains an important production and distribution hub due to its developed logistics and regional access.
Chubu Region
Chubu accounted for 18% of the Japan Pet Food Market in 2024. The region benefits from balanced urbanization and high purchasing power in prefectures such as Aichi and Shizuoka. Pet owners emphasize balanced nutrition and natural ingredient-based food. Rising awareness of pet wellness and veterinary recommendations drive adoption of fortified diets. Local brands expand presence through direct retail networks and cooperative stores. The region shows steady demand across both dog and cat food segments supported by an aging pet population.
Kyushu Region
Kyushu represented a 13% share in 2024, supported by rising pet ownership in urban centers like Fukuoka and Kumamoto. The regional market is characterized by a growing shift toward sustainable and organic pet food. Consumers favor locally produced brands with clear ingredient traceability. The availability of modern retail outlets and improved e-commerce delivery networks enhances accessibility. Pet care awareness campaigns by manufacturers and local organizations strengthen adoption of premium and functional pet diets.
Hokkaido and Tohoku Region
Hokkaido and Tohoku collectively held a 9% share of the market in 2024. These northern regions show growing interest in nutritious and weather-suited pet food formulations. Cold climates increase demand for energy-dense diets among dog owners. Local pet stores focus on specialized offerings tailored to regional preferences. Rural households with higher pet ownership rates sustain steady consumption levels. Rising internet penetration and online retail access are helping manufacturers expand distribution across these regions.
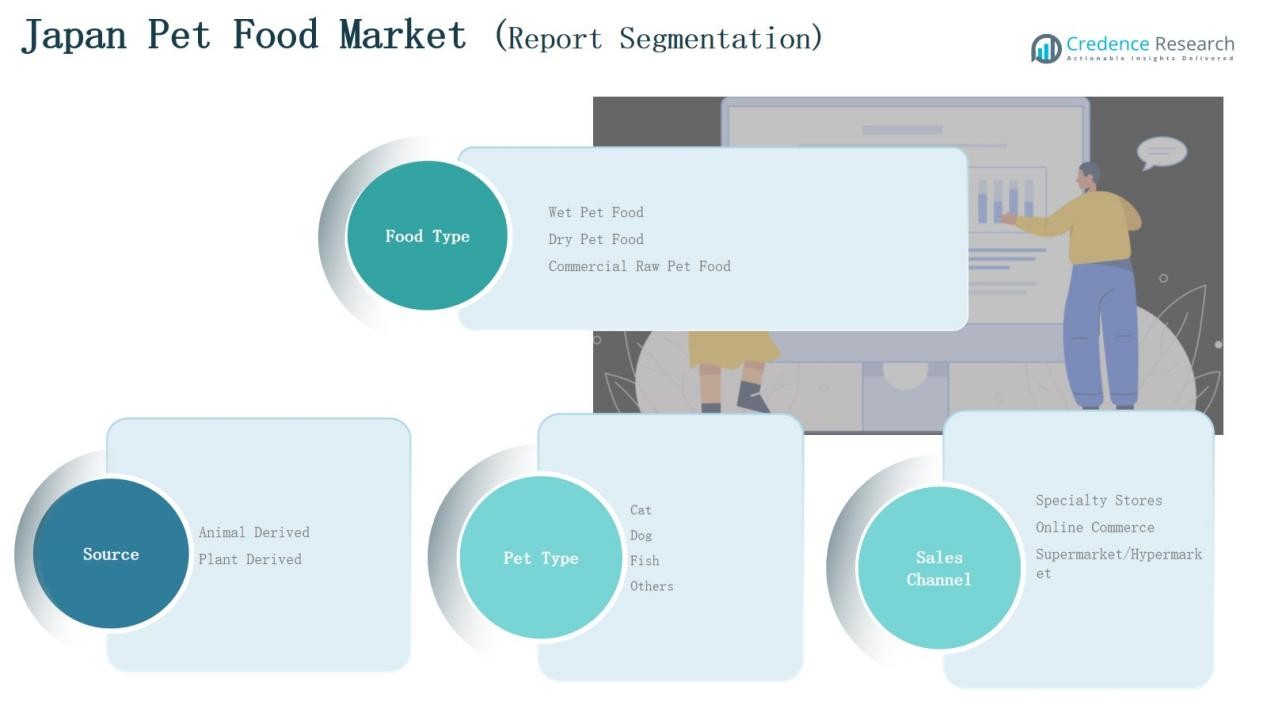
Market Segmentations:
By Food Type:
- Wet Pet Food
- Dry Pet Food
- Commercial Raw Pet Food
By Source:
- Animal Derived
- Plant Derived
By Pet Type:
- Cat
- Dog
- Fish
- Others
By Sales Channel:
- Specialty Stores
- Online Commerce
- Supermarket/Hypermarket
By Region
- Kanto
- Kansai
- Chubu
- Kyushu
- Hokkaido and Tohoku
Competitive Landscape
The Japan Pet Food Market features a moderately consolidated competitive landscape, dominated by global and domestic players focused on innovation, product quality, and distribution strength. Leading companies such as Unicharm Corporation, Mars, Incorporated, and Nestlé Purina PetCare maintain strong market positions through premium formulations, advanced nutritional research, and brand trust. Domestic firms like NIPPON PET FOOD CO., LTD. and INABA-PETFOOD leverage local sourcing and regional preferences to sustain competitiveness. The market emphasizes functional, organic, and breed-specific products to meet evolving consumer demands. E-commerce partnerships with platforms like Rakuten and Amazon Japan strengthen online visibility and sales growth. Companies are also investing in eco-friendly packaging, sustainable ingredients, and personalized nutrition. Continuous product innovation, digital marketing, and expansion into specialty pet categories drive strategic competition. It remains a market where technological advancement and consumer-driven customization define long-term leadership and brand differentiation.
Key Players
- Unicharm Corporation
- Mars, Incorporated
- Nestlé Purina PetCare
- Hill’s Pet Nutrition
- General Mills, Inc.
- NIPPON PET FOOD CO., LTD.
- United Petfood
- Landini Giuntini SPA
- Affinity Petcare
- MG Group
- INABA-PETFOOD
- Other Key Players
Recent Developments
- In July 2025, Maruha Nichiro’s subsidiary AIXIA launched its first frozen dog food line, marking the company’s entry into Japan’s premium frozen pet food segment.
- In December 2024, Toppan Holdings announced the acquisition of Sonoco’s Thermoformed and Flexible Packaging division for USD 1.8 billion, strengthening its position in Japan’s pet food packaging sector.
- In June 2025, Maruha Nichiro established a dedicated Pet Food Business Promotion Office to accelerate domestic and overseas expansion, particularly in Japan and Thailand.
Report Coverage
The research report offers an in-depth analysis based on Food Type, Source, Pet Type, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for premium and functional pet food will continue to increase across urban areas.
- E-commerce platforms will play a greater role in driving pet food accessibility and subscription sales.
- Local brands will expand their share through affordable, nutritionally balanced formulations.
- Sustainable sourcing and recyclable packaging will become key competitive factors.
- Growth in senior and single-person households will support higher cat food consumption.
- Technological advancements will enable customized nutrition and data-driven product development.
- Veterinary recommendations will influence pet food purchases focused on health and longevity.
- International players will increase investments in Japan through partnerships and local production.
- Functional treats and supplements will emerge as new growth categories within the market.
- Rising consumer focus on transparency and clean labeling will shape future product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Japan Pet Food Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Japan Pet Food Market projected to grow between 2025 and 2032?
Which Japan Pet Food Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Japan Pet Food Market?
Who are the leading companies in the Japan Pet Food Market?
Which region commanded the largest share of the Japan Pet Food Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,258.63 million → 2032: USD 8,715.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Japan Pet Food Market Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Japan Pet Food Market Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Japan Pet Food Market Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Japan Pet Food Market Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Japan Pet Food Market Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Japan Pet Food Market Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Japan Pet Food Market Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Japan Pet Food Market Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,258.63 million → 2032: USD 8,715.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Japan Pet Food Market Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Japan Pet Food Market Geographic Market Outlook, 2024-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Japan Pet Food Market Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Japan Pet Food Market Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

