
Food Flavors Market Overview:
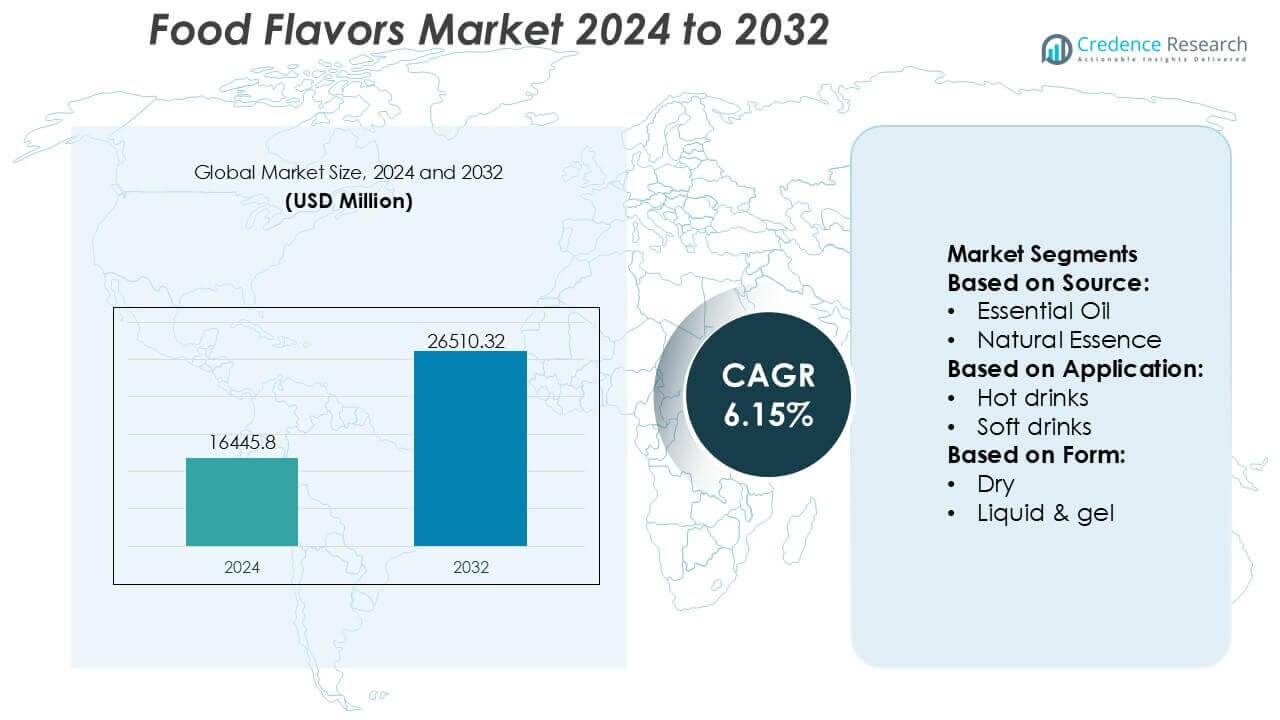
Food Flavors Market size was valued USD 16445.8 million in 2024 and is anticipated to reach USD 26510.32 million by 2032, at a CAGR of 6.15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Flavors Market Size 2024 | USD 16445.8 million |
| Food Flavors Market, CAGR | 6.15% |
| Food Flavors Market Size 2032 | USD 26510.32 million |
Food Flavors Market Insights
- Market growth is driven by increasing consumption of packaged and convenience foods, with natural flavors emerging as the dominant segment holding an estimated 56% share due to clean-label and health-oriented preferences.
- Key trends include rapid adoption of taste-modulation technologies, growing use of ethnic and regional flavors, and rising demand for flavors in functional beverages and plant-based food formulations.
- The competitive landscape is shaped by global manufacturers focusing on broad flavor portfolios, strong application science, and continuous R&D investments to support customization, reformulation, and regulatory compliance.
- Regionally, Asia-Pacific leads the market with an exact 31% share, driven by urbanization, expanding food processing capacity, and high demand for flavored snacks, beverages, and instant foods.
Food Flavors Market Segmentation Analysis:
By Source
The food flavors market by source is segmented into natural and synthetic flavors, with natural flavors dominating at approximately 62% market share. This leadership is driven by strong consumer preference for clean-label, plant-derived ingredients and regulatory support for natural sourcing. Within natural flavors, essential oils form the dominant sub-segment, supported by their high flavor potency, thermal stability, and broad applicability across beverages and bakery products. Rising demand for minimally processed foods and transparency in ingredient labeling continues to accelerate the adoption of natural essences and essential oils, while synthetic and nature-identical flavors remain relevant for cost efficiency and formulation consistency in mass-produced foods.
- For instance, Takasago International Corporation operates advanced natural extraction facilities capable of processing more than 3,000 tons of botanical raw materials annually and has developed proprietary cold-extraction and fractionation technologies that preserve over 95 identifiable volatile aroma compounds in essential oil profiles, enabling high-potency natural flavors with consistent sensory performance across multiple food applications.
By Application
By application, beverages represent the dominant segment with around 34% market share, reflecting high consumption volumes and continuous product innovation. Within beverages, soft drinks lead due to their extensive flavor diversification and frequent new product launches. The segment benefits from strong demand for fruit, botanical, and functional flavor profiles that enhance taste while supporting sugar reduction strategies. Other major applications such as bakery & confectionery and dairy & frozen products also show steady demand, driven by indulgent flavor profiles and seasonal innovations. Savory & snacks are gaining momentum as manufacturers introduce region-specific and umami-rich flavor formulations.
- For instance, Robertet Group operates more than 14 dedicated beverage application laboratories globally and has developed over 1,200 proprietary beverage flavor bases annually, supported by in-house botanical processing capacity exceeding 10,000 tons of natural raw materials per year and advanced CO₂ extraction systems capable of isolating hundreds of distinct aromatic molecules for high-performance beverage and food applications.
By Form
Based on form, liquid flavors hold the leading position with nearly 58% market share, primarily due to their ease of blending, rapid flavor release, and suitability for beverages and dairy applications. Liquid and gel formats dominate because they offer precise dosing and uniform dispersion in large-scale manufacturing. Dry flavors remain important in bakery, confectionery, and snack applications where shelf stability and low moisture content are critical. Growth in liquid formats is further supported by advancements in emulsification and encapsulation technologies, which enhance flavor stability, extend shelf life, and maintain sensory consistency across diverse food matrices.
Key Growth Drivers
Rising Demand for Processed and Convenience Foods
The increasing consumption of processed, packaged, and ready-to-eat foods remains a primary growth driver for the food flavors market. Urbanization, busy lifestyles, and higher disposable incomes are accelerating demand for convenient food and beverage options with consistent taste profiles. Food flavors enable manufacturers to standardize sensory attributes across large production volumes while meeting evolving consumer preferences. The expanding presence of quick-service restaurants, frozen foods, and instant beverages further amplifies flavor usage, positioning flavor systems as an essential component in large-scale food manufacturing and product differentiation strategies.
- For instance, Sensient Technologies Corporation operates more than 40 global manufacturing and application facilities and produces over 25,000 formulated flavor and color solutions annually, supported by advanced spray-drying and encapsulation lines capable of processing batch sizes exceeding 10,000 kilograms per production run to ensure uniform flavor delivery in large-scale processed food and beverage applications.
Shift Toward Clean-Label and Natural Ingredients
Growing consumer awareness around ingredient transparency and health has significantly increased demand for natural and clean-label food flavors. Manufacturers are reformulating products to replace artificial additives with natural extracts, essential oils, and nature-identical compounds. This shift supports the development of flavors derived from fruits, vegetables, herbs, and spices that align with regulatory and consumer expectations. As clean-label positioning becomes a competitive necessity, food flavors play a critical role in preserving taste integrity while complying with stricter labeling norms and clean-ingredient formulations.
- For instance, Huabao Flavours & Fragrances Co., Ltd. operates more than 30 flavor application and R&D centers across China and international markets and develops over 6,000 new beverage and dairy flavor formulations each year, supported by spray-drying and liquid blending lines with single-batch processing capacities exceeding 8,000 kilograms, enabling consistent flavor performance in large-scale beverage and dairy manufacturing.
Expansion of Beverage and Dairy Applications
The rapid expansion of flavored beverages and dairy products strongly drives market growth. Carbonated drinks, functional beverages, flavored milk, yogurt, and frozen desserts increasingly rely on advanced flavor systems to enhance taste complexity and mouthfeel. Flavor innovation supports sugar-reduction initiatives, fortification, and the introduction of novel taste combinations. Continuous product launches in sports drinks, plant-based beverages, and indulgent dairy offerings reinforce demand for both liquid and dry flavor formats, strengthening the market’s application breadth.
Key Trends & Opportunities
Innovation in Flavor Modulation and Taste Masking
Flavor modulation technologies are emerging as a key trend, enabling manufacturers to reduce sugar, salt, and fat without compromising sensory appeal. Advanced taste-masking solutions help neutralize bitterness and off-notes in functional ingredients, plant-based proteins, and fortified foods. This trend creates opportunities for flavor developers to support health-focused formulations while maintaining consumer acceptance. As reformulation pressures increase, flavor systems that enhance sweetness perception or balance complex taste profiles gain strategic importance across food and beverage categories.
- For instance, Kerry Group plc has developed proprietary taste-modulation platforms supported by more than 1,100 sensory scientists and flavor technologists globally and operates over 70 application and innovation centers, where validated masking solutions have demonstrated measurable bitterness reduction across dozens of plant protein matrices using controlled sensory panel protocols with repeatable, statistically robust performance outcomes.
Growing Adoption of Regional and Ethnic Flavors
Consumer interest in global cuisines and authentic taste experiences is driving demand for regional and ethnic flavors. Manufacturers increasingly incorporate Asian, Latin American, Middle Eastern, and African flavor profiles into mainstream products. This trend supports product differentiation and premium positioning in snacks, sauces, bakery, and ready meals. The opportunity lies in developing culturally accurate, scalable flavor systems that meet local taste expectations while supporting global product rollouts across diverse markets.
- For instance, MANE maintains a global network of more than 50 creative flavor studios and operates dedicated regional taste platforms supported by over 900 flavorists and sensory experts, generating thousands of region-specific flavor formulations annually and leveraging proprietary extraction and reaction-flavor technologies capable of reproducing complex spice, roasted, and fermented notes with consistent batch-to-batch sensory fidelity across industrial production runs.
Rising Use of Encapsulated and Dry Flavor Formats
Encapsulation and spray-drying technologies are gaining traction due to their ability to improve flavor stability, shelf life, and controlled release. Dry flavors offer advantages in bakery, confectionery, and snack applications by withstanding high-temperature processing. This trend creates opportunities for manufacturers to enhance performance in complex processing environments while reducing flavor loss. The growing preference for powdered and encapsulated formats supports efficiency, consistency, and extended product life cycles.
Key Challenges
Volatility in Raw Material Availability and Pricing
The food flavors market faces challenges from fluctuating availability and pricing of natural raw materials such as citrus oils, vanilla, spices, and botanical extracts. Climatic variations, agricultural yield uncertainty, and supply-chain disruptions directly impact sourcing stability and cost structures. This volatility pressures manufacturers to manage procurement risks while maintaining consistent quality. Dependence on agricultural inputs also increases exposure to regulatory restrictions and sustainability requirements, complicating long-term supply planning.
Regulatory Compliance and Labeling Complexity
Stringent and evolving food safety regulations present a significant challenge for flavor manufacturers. Compliance with regional standards related to ingredient approvals, allergen declarations, and natural labeling definitions increases formulation complexity. Regulatory divergence across markets complicates global product launches and requires extensive documentation and testing. Meeting clean-label expectations while ensuring regulatory adherence adds operational costs and lengthens product development timelines, particularly for natural and nature-identical flavor systems.
Regional Analysis
North America
North America holds a significant 34% market share in the global food flavors market, driven by high consumption of processed foods, flavored beverages, and convenience products. Strong demand for clean-label, natural, and organic flavors continues to shape product development across food and beverage categories. The region benefits from advanced flavor formulation capabilities, robust R&D investments, and a mature food processing industry. Growth is further supported by the rapid expansion of functional foods, plant-based alternatives, and premium dairy products. Regulatory clarity and high consumer willingness to pay for flavor innovation reinforce North America’s leadership position.
Europe
Europe accounts for approximately 27% market share, supported by strong demand for natural, botanical, and region-specific flavor profiles. Strict regulatory frameworks encourage the adoption of clean-label and sustainably sourced flavors, particularly in bakery, confectionery, and dairy applications. The region demonstrates high consumer sensitivity to ingredient transparency and authenticity, driving innovation in natural extracts and essential oils. Western Europe leads demand due to advanced food manufacturing infrastructure, while Eastern Europe shows steady growth through expanding packaged food consumption. Continuous innovation in taste modulation and reformulation supports long-term regional growth.
Asia-Pacific
Asia-Pacific dominates the food flavors market with an exact 31% market share, driven by rapid urbanization, population growth, and rising consumption of packaged and ready-to-eat foods. Expanding middle-class populations and increasing exposure to Western and fusion cuisines accelerate demand for diverse flavor profiles. Strong growth in flavored beverages, snacks, and instant foods supports high-volume flavor usage. Local taste preferences, including spicy, umami, and ethnic flavors, further boost demand. The region also benefits from cost-efficient manufacturing and expanding food processing capacity, positioning Asia-Pacific as the fastest-growing regional market.
Latin America
Latin America holds nearly 5% market share, supported by increasing demand for flavored beverages, dairy products, and snacks. Rising urbanization and improving retail penetration are expanding the consumption of packaged foods across key economies. Traditional and tropical flavor profiles such as citrus, fruit blends, and spice-based flavors remain highly popular. While price sensitivity influences purchasing behavior, manufacturers increasingly invest in affordable flavor solutions that enhance taste and shelf life. Growing interest in convenience foods and local flavor authenticity continues to drive gradual market expansion across the region.
Middle East & Africa
The Middle East & Africa region accounts for about 3% market share, driven by expanding food processing industries and rising consumption of packaged foods. Demand is supported by population growth, urban lifestyles, and increasing adoption of flavored beverages and bakery products. Regional preferences for sweet, spice-rich, and aromatic flavors influence formulation strategies. While the market remains smaller in scale, improving cold-chain infrastructure and retail modernization support steady growth. Import dependency for flavor ingredients and regulatory variability present challenges, but long-term opportunities remain strong across developing economies.
Market Segmentations:
By Source:
- Essential Oil
- Natural Essence
By Application:
- Hot drinks
- Soft drinks
By Form:
- Dry
- Liquid & gel
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the food flavors market players such as Takasago International Corporation, Robertet Group, Sensient Technologies Corporation, Huabao Flavours & Fragrances Co., Ltd., Kerry Group plc, MANE, Symrise AG, Givaudan, International Flavors & Fragrances Inc., Firmenich SA. the food flavors market is defined by intense competition among large, innovation-driven manufacturers that differentiate through broad portfolios, advanced formulation expertise, and strong customer collaboration. Companies focus on developing customized flavor solutions tailored to specific applications such as beverages, bakery, dairy, and savory foods, while supporting reformulation efforts related to sugar, salt, and fat reduction. Investment in natural and clean-label flavor development remains a central strategy, alongside the use of advanced extraction, encapsulation, and flavor-modulation technologies. Global production footprints, regulatory compliance capabilities, and strong application laboratories enable rapid product localization and scalability. Strategic partnerships with food and beverage producers, combined with continuous R&D investment and sustainability-driven sourcing, further intensify competition and reinforce long-term market positioning.
Key Player Analysis
- Takasago International Corporation
- Robertet Group
- Sensient Technologies Corporation
- Huabao Flavours & Fragrances Co., Ltd.
- Kerry Group plc
- MANE
- Symrise AG
- Givaudan
- International Flavors & Fragrances Inc.
- Firmenich SA
Recent Developments
- In January 2025, McCormick unveils its 2025 Flavor of the Year: Aji Amarillo, a pepper native to South America featuring fruity, tropical notes with moderate heat. This selection reflects the company's commitment to exploring diverse global flavours and catering to evolving consumer tastes.
- In January 2025, PepsiCo India and Tata Consumer Products partnered to create fusion snacks, launching a limited-edition Kurkure Ching's Secret Schezwan Chutney flavor, blending Kurkure's crunch with Ching's Secret's popular Indo-Chinese taste to capture India's booming snack market.
- In January 2025, RECOVER 180™, the leading premium hydration beverage brand, is excited to unveil its newest mouth-watering flavor, Strawberry Banana. This refreshing flavor combines the sweetness of strawberries with the creaminess of bananas, and like all RECOVER 180 drinks, it features organic coconut water, essential vitamins, and minerals for optimal hydration.
- In January 2024, IFF, a global leader in food and beverage, home and personal care, and health, has partnered with Unilever and Wageningen University & Research (WUR) on a collaborative research initiative to tackle flavor challenges in plant-based meat alternatives.
Report Coverage
The research report offers an in-depth analysis based on Source, Application, Form and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for natural and clean-label flavors will continue to increase as consumers prioritize transparency and minimally processed ingredients.
- Flavor innovation will increasingly support sugar, salt, and fat reduction without compromising taste quality.
- Growth in functional foods and beverages will drive the use of advanced taste-masking and flavor-modulation solutions.
- Regional and ethnic flavor profiles will gain wider adoption across mainstream food and beverage categories.
- Encapsulation and controlled-release technologies will improve flavor stability and processing performance.
- Plant-based and alternative protein products will accelerate demand for customized flavor systems.
- Digital tools and data-driven flavor development will enhance speed-to-market and formulation accuracy.
- Sustainability-focused sourcing and production practices will shape long-term flavor development strategies.
- Expansion of ready-to-eat and convenience foods will sustain high-volume flavor consumption globally.
- Regulatory alignment and clean-label compliance will remain critical factors influencing future product innovation.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth of Packaged and Convenience Foods
Urbanization, busy lifestyles, and higher disposable incomes are fueling the consumption of processed, packaged, and ready-to-eat foods, which require consistent and appealing flavor profiles to attract consumers and ensure product differentiation.
Shift Toward Clean-Label and Natural Ingredients
Increasing consumer awareness around health and ingredient transparency is driving manufacturers to reformulate products with natural extracts, essential oils, and plant-derived flavors, boosting demand for clean-label flavor solutions.
Expansion of Beverage and Dairy Applications
Continuous innovation and product launches in flavored beverages, dairy, and plant-based alternatives are increasing the need for advanced flavor systems that enhance taste, support sugar reduction, and deliver novel sensory experiences.
Innovation in Flavor Modulation and Taste Masking
Manufacturers are adopting advanced flavor modulation and taste-masking technologies to reduce sugar, salt, and fat content in foods and beverages without compromising taste, supporting health-focused product development.
Rising Demand for Regional and Ethnic Flavors
Growing consumer interest in authentic global cuisines is prompting manufacturers to incorporate regional and ethnic flavor profiles into mainstream products, expanding the market for diverse and culturally relevant flavor solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Food Flavors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Flavors Market projected to grow between 2024 and 2032?
Which Food Flavors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Flavors Market?
Who are the leading companies in the Food Flavors Market?
Which region commanded the largest share of the Food Flavors Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid & Gel
- 1.2.2 Dry
- 1.2.3 Encapsulated
- 1.3 By Source
- 1.3.1 Essential Oil
- 1.3.2 Natural Essence
- 1.3.3 Synthetic Flavors
- 1.3.4 Nature-Identical Flavors
- 1.4 By Application
- 1.4.1 Beverages
- 1.4.2 Bakery & Confectionery
- 1.4.3 Dairy & Frozen Products
- 1.4.4 Savory & Snacks
- 1.4.5 Ready Meals
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16,445.8 million → 2032: USD 26,510.32 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Food Flavor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Food Flavor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Food Flavor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Food Flavor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Food Flavor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Food Flavor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Food Flavor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Food Flavor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16,445.8 million → 2032: USD 26,510.32 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Food Flavor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid & Gel
- 12.3.7.2 Dry
- 12.3.7.3 Encapsulated
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Essential Oil
- 12.4.7.2 Natural Essence
- 12.4.7.3 Synthetic Flavors
- 12.4.7.4 Nature-Identical Flavors
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Beverages
- 12.5.7.2 Bakery & Confectionery
- 12.5.7.3 Dairy & Frozen Products
- 12.5.7.4 Savory & Snacks
- 12.5.7.5 Ready Meals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Food Flavor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Food Flavor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Food Flavor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Food Flavor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Takasago International Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Robertet Group
- 18.4 Sensient Technologies Corporation
- 18.5 Huabao Flavours & Fragrances Co., Ltd.
- 18.6 Kerry Group plc
- 18.7 MANE
- 18.8 Symrise AG
- 18.9 Givaudan
- 18.10 International Flavors & Fragrances Inc.
- 18.11 Firmenich SA
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

