
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Grade Silica Market Size 2024 | USD 1,888 Million |
| Food Grade Silica Market, CAGR | 4.8% |
| Food Grade Silica Market Size 2032 | USD 2,747 Million |
Market Overview
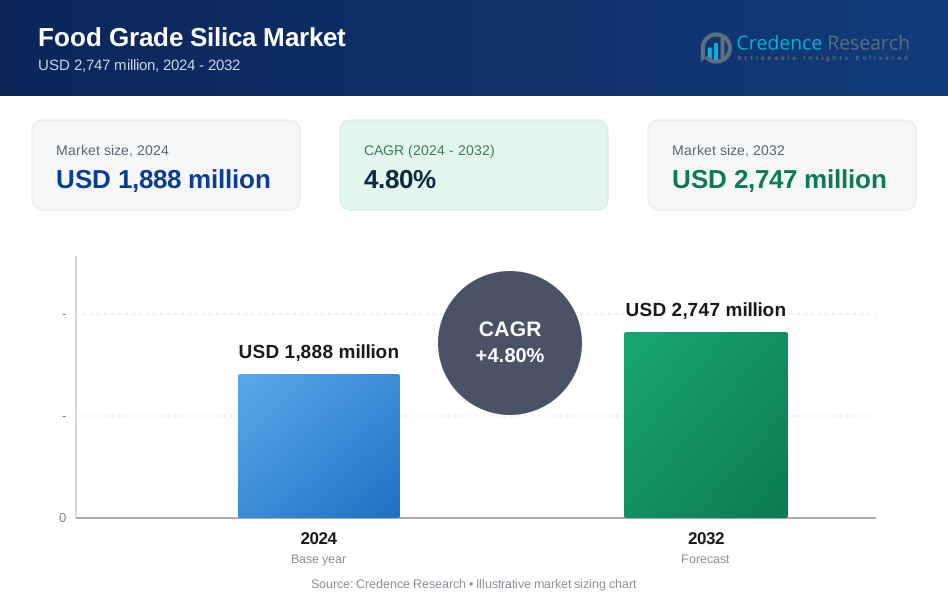
The Food Grade Silica Market is projected to grow from USD 1,888 million in 2024 to USD 2,747 million by 2032, registering a CAGR of 4.8%.
The food grade silica market is experiencing steady growth driven by rising demand for processed and packaged foods, where silica serves as an effective anti-caking, thickening, and stabilizing agent. Increasing health awareness and the push for extended shelf life in food products are encouraging manufacturers to incorporate food-grade additives that ensure quality and safety. Regulatory approvals for silica usage in various food applications further support market expansion. Growth in the global food and beverage industry, particularly in emerging economies, fuels the need for functional ingredients like silica. Trends such as clean-label product demand and the shift toward natural and plant-based food products are influencing innovation in silica formulations. Manufacturers are investing in high-purity, eco-friendly variants to align with sustainable food production practices. Moreover, advancements in nanotechnology and food-grade silica's compatibility with dietary supplements, beverages, and powdered products contribute to its expanding usage. These factors collectively position food grade silica as a critical component in modern food processing.
The food grade silica market demonstrates strong regional presence across North America, Europe, and Asia-Pacific. North America leads with 32% market share, supported by advanced food processing infrastructure and high demand for functional additives. Europe follows with 28%, driven by regulatory standards and preference for natural ingredients. Asia-Pacific holds 25% share, fueled by rising urbanization and processed food consumption in China and India. Key players in the market include BASF SE, Evonik Industries AG, W.R. Grace & Co., PPG Industries Inc., J.M. Huber Corporation, Imerys S.A, Sibelco, Madhu Silica Pvt. Ltd., Hubei Bafang Chemical Industry Co. Ltd., Kraton Corporation, and Silikal GmbH. These companies compete on product innovation, distribution strength, and regulatory compliance. They continue to invest in regional expansions and tailored formulations to meet local food industry requirements, enhancing their competitiveness across all major markets.
Market Insights
- The food grade silica market is projected to grow from USD 1,888 million in 2024 to USD 2,747 million by 2032, registering a CAGR of 4.8%, driven by rising demand for functional additives in food processing.
- Growing consumption of processed and packaged foods globally fuels demand for silica as an anti-caking, thickening, and stabilizing agent to improve product texture and shelf stability.
- Increasing popularity of functional foods and dietary supplements supports market growth, with silica enhancing nutrient stability, packaging efficiency, and consistent dosage in health-focused products.
- Regulatory approvals from agencies like the FDA and EFSA for silica use in food applications provide a strong foundation for global market expansion and compliance confidence among manufacturers.
- Ongoing innovation in silica formulations, including nano-silica and surface-modified variants, expands application in powdered beverages, high-protein snacks, and plant-based products.
- The market faces challenges from complex regulations, rising production costs, and raw material availability, which require investment in compliance, research, and supply chain optimization.
- Regionally, North America leads with 32% market share, followed by Europe at 28% and Asia-Pacific at 25%, with key players including BASF SE, Evonik Industries AG, PPG Industries Inc., and J.M. Huber Corporation.
Market Drivers
Rising Demand for Processed and Packaged Foods
The food grade silica market is witnessing strong growth due to the expanding processed and packaged food sector. Urbanization, busy lifestyles, and growing disposable incomes are fueling consumer preference for convenience foods. Silica acts as an anti-caking and thickening agent in powdered products, sauces, and seasonings, ensuring texture and stability. It helps maintain product quality during storage and transportation. Manufacturers prefer food-grade silica for its efficiency and safety in diverse applications. It plays a critical role in enhancing shelf life without affecting taste or nutritional value.
Growth in Functional Food and Supplement Consumption
The increasing popularity of functional foods and dietary supplements significantly drives the food grade silica market. Consumers seek products that offer added health benefits, and silica supports nutrient stability in vitamins, minerals, and powdered supplements. Its moisture-absorbing and flow-enhancing properties improve the shelf life and packaging efficiency of nutraceuticals. Demand for silica-coated microcapsules and powders is rising among supplement producers. It supports consistent dosage and uniform mixing in blends. The market benefits from silica’s compatibility with health-oriented formulations.
For instance, Vitro Minerals offers RS-50 Pyrogenic Silica, a 100% recycled, hydrophilic silica specifically engineered to improve the stability and handling of powdered supplements by providing excellent flow and anti-caking properties.
Regulatory Approvals and Food Safety Standards
Strict food safety regulations and broad regulatory approvals across regions are encouraging the use of silica in food production. Government agencies recognize silica as safe when used within prescribed limits, supporting its inclusion in processed and fortified foods. It complies with FDA, EFSA, and other international standards, reassuring manufacturers of its quality and performance. The food grade silica market benefits from such endorsements, which reduce barriers to adoption. It aligns with modern food safety requirements and consumer expectations. Its consistent performance makes it suitable for high-volume industrial food processing.
For instance, Evonik’s silica products are approved for use in food by the European Food Safety Authority (EFSA) and other global agencies, with EFSA recently reaffirming the safety of E 551 (synthetic amorphous silica) for all population groups, including infants under 16 weeks.
Innovation in Silica-Based Food Applications
Ongoing innovations in formulation technologies are expanding the scope of food grade silica in new food applications. Advances in particle engineering, nano-silica production, and surface modification improve its efficiency in functional blends. It enables the development of stable emulsions, powdered beverages, and high-protein snack formulations. The market is seeing new product launches using silica for moisture control and flow improvement. It supports clean-label formulations and plant-based alternatives. This continuous innovation strengthens the food grade silica market’s position in modern food manufacturing.
Market Trends
Growing Preference for Clean-Label and Natural Additives
Consumers are increasingly prioritizing clean-label food products with transparent ingredient lists, driving demand for naturally derived and minimally processed additives. The food grade silica market is responding with high-purity, eco-friendly variants suitable for clean-label claims. It enables improved stability, texture, and moisture control in processed foods without compromising product integrity. Brands seek to reduce synthetic additives, and food-grade silica offers a compliant alternative. This trend is particularly evident in bakery, seasoning, and organic product segments. It aligns with consumer interest in healthier, more natural food choices.
For instance, Nestlé launched its YES! snack bars in Europe, highlighting a short ingredient list free from artificial additives and emphasizing natural, plant-based components, which aligns with European consumer demand for transparency and naturalness.
Rising Use in Plant-Based and Alternative Protein Products
The global shift toward plant-based diets is influencing the adoption of food-grade silica in alternative protein products. Manufacturers are incorporating silica into powdered meat substitutes, protein mixes, and plant-based beverages to enhance flowability, prevent clumping, and extend shelf life. The food grade silica market benefits from this development, as it meets the technical requirements of non-animal-based products. It plays a key role in delivering consistent product performance. Increased consumer interest in ethical and sustainable diets strengthens this trend. It ensures quality and handling ease in complex food matrices.
For instance, Evonik Industries AG uses its AEROSIL® and SIPERNAT® silica products to prevent clumping and improve flowability in plant-based protein powders, helping manufacturers maintain consistent product quality.
Adoption in Nutraceutical and Supplement Formulations
Food-grade silica is gaining traction in the growing nutraceutical industry, where precise formulation and moisture resistance are critical. Supplement manufacturers use silica in tablets, capsules, and powdered blends to ensure stability and prevent degradation. The food grade silica market is seeing wider adoption in dietary supplements, especially those targeting immunity, bone health, and sports nutrition. It supports controlled release, uniform particle distribution, and improved packaging efficiency. As demand rises for personalized and functional nutrition, silica’s utility continues to expand. It supports product innovation across multiple health-focused categories.
Technological Advancements in Silica Production and Application
Innovations in silica production methods are enabling finer particle sizes, enhanced porosity, and surface functionalization for superior food applications. These advancements improve silica’s performance in moisture control, dispersion, and emulsion stabilization. The food grade silica market benefits from technologies such as nano-silica and sol-gel synthesis, which provide more efficient and customized solutions. It allows producers to meet specific textural and functional demands in various food types. Manufacturers are adopting automated systems for consistent blending and dosing. These technologies enhance quality assurance in large-scale food production environments.
Market Challenges Analysis
Stringent Regulatory Compliance and Safety Concerns
The food grade silica market faces challenges due to complex regulatory frameworks and evolving safety standards across regions. While silica is generally recognized as safe, manufacturers must meet strict usage limits, labeling norms, and purity benchmarks. Inconsistent global regulations can delay product approvals and increase compliance costs. Concerns over potential health risks from excessive or nano-scale silica exposure have sparked debates and caution among consumers and regulatory bodies. The industry must invest in ongoing toxicological research and transparency to maintain consumer confidence. It must also adapt to shifting standards driven by scientific findings and policy changes.
High Production Costs and Limited Raw Material Availability
The production of high-purity food grade silica involves energy-intensive processes and stringent quality control, which elevate manufacturing costs. Fluctuations in the availability and price of raw materials such as quartz and sodium silicate can disrupt supply chains. Smaller manufacturers often struggle to compete with larger players who benefit from economies of scale. The food grade silica market must navigate these cost pressures while ensuring consistent quality and supply. It also faces rising demand, which can strain existing production capacity and infrastructure. These challenges require strategic investment and supply chain optimization to sustain growth.
Market Opportunities
Expansion in Emerging Economies and Localized Food Manufacturing
Emerging markets present strong growth opportunities for the food grade silica market due to rising urbanization, expanding middle-class populations, and increased consumption of packaged foods. Governments in Asia-Pacific, Latin America, and Africa are investing in food processing infrastructure, driving local demand for functional food additives. Manufacturers are entering these regions through joint ventures and distribution partnerships to capitalize on growing domestic needs. It benefits from the rapid growth of regional food brands seeking reliable, approved additives. Local sourcing and tailored formulations improve cost-effectiveness and product acceptance. These dynamics create fertile ground for sustained market penetration.
Innovation in Specialty Applications and Custom Formulations
The development of specialty food products such as plant-based meals, high-protein snacks, and functional beverages opens new application areas for food grade silica. Customized formulations tailored to specific food matrices, moisture levels, and textural goals offer competitive differentiation. It enables manufacturers to meet evolving consumer expectations around convenience, health, and product consistency. Growth in e-commerce and direct-to-consumer food models further fuels demand for long shelf-life and stable packaging, where silica plays a vital role. Companies investing in R&D and application-specific silica grades are positioned to capture emerging niches. The food grade silica market stands to benefit from these specialized, value-added solutions.
Market Segmentation Analysis:
By Product Type
The food grade silica market includes various product types, with precipitated silica holding the largest share due to its widespread use in food and feed applications for its anti-caking and thickening properties. Fumed silica follows closely, offering high surface area and purity ideal for specialized formulations. Silica gel finds application in moisture control, particularly in packaging. Colloidal silica is used in liquid-based food and beverage products for stabilization. The “Others” category includes custom blends and emerging formulations tailored for niche uses. Each type serves specific processing and performance needs across food sectors.
For instance, PPG’s FLO-GARD™ precipitated silica demonstrated a carrying capacity exceeding 66% by weight when tested with sunflower oil, enabling manufacturers to convert liquids into free-flowing powders for use in animal feed premixes and powdered food products, while also improving production efficiency and reducing packaging and shipping costs.
By Application
In terms of application, animal feed dominates the food grade silica market due to the growing need for flow aids and anti-caking agents in feed formulations. It enhances handling efficiency and nutritional stability. Pet food is another significant segment, driven by rising premiumization and demand for dry and semi-moist formulations. The “Others” segment includes human food and dietary supplements where silica supports consistent texture and extended shelf life. It enables product innovation in health-oriented and fortified foods across multiple regions.
For instance, Evonik’s silica products are specifically engineered to convert liquid feed additives—such as vitamin concentrates—into free-flowing powders, ensuring precise dosing and reducing caking in automated feed systems.
By Distribution Channel
By distribution channel, specialty stores remain a key outlet for food grade silica, especially for industrial buyers and small-scale producers seeking specific grades. Online stores are gaining traction, offering ease of access, variety, and direct delivery to end users. The “Others” category includes offline distributors and B2B bulk supply networks. The market benefits from growing digitalization and improved supply chain integration, which expand product availability across domestic and international markets.
Segments:
Based on Product Type
- Precipitated Silica
- Fumed Silica
- Silica Gel
- Colloidal Silica
- Others
Based on Application
- Animal Feed
- Pet Food
- Others
Based on Distribution Channel
- Online Stores
- Specialty Stores
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the food grade silica market, accounting for 32% of global revenue. The region's dominance is driven by advanced food processing industries, strong regulatory compliance, and high consumption of packaged and functional foods. The United States leads in both production and application of food-grade silica across human food, pet food, and dietary supplements. Manufacturers invest in high-purity silica solutions tailored for health-conscious consumers. Demand continues to rise due to increased adoption in vegan, organic, and clean-label products. It remains a favorable region for innovation and product development supported by robust research infrastructure.
Europe
Europe represents 28% of the global food grade silica market, supported by strict food safety regulations and growing demand for natural additives. Countries like Germany, France, and the Netherlands play a significant role due to their established food and feed sectors. Consumer preference for transparent labeling and sustainable production methods drives demand for silica as a safe and effective additive. The region benefits from consistent government support for food innovation and functional ingredients. Silica is widely used in bakery, dairy, and animal nutrition segments. It maintains steady growth through both local manufacturing and imports.
Asia-Pacific
Asia-Pacific accounts for 25% of the food grade silica market, with rising demand driven by population growth, urbanization, and expansion of the food processing industry. China and India are key contributors, with increasing consumption of processed and convenience foods. Regional governments are investing in infrastructure to support food safety and quality, creating more opportunities for silica applications. It supports formulation needs across a wide range of local and international food products. Growing awareness of nutritional supplements and pet care also supports segment expansion. Asia-Pacific continues to attract global manufacturers seeking high-growth opportunities.
Key Player Analysis
- Silikal GmbH
- R. Grace & Co.
- Madhu Silica Pvt. Lt
- Sibelco
- Imerys S.A
- Evonik Industries AG
- BASF SE
- PPG Industries Inc.
- Kraton Corporation
- Hubei Bafang Chemical Industry Co. Ltd.
- M. Huber Corporation
Competitive Analysis
The food grade silica market features a competitive landscape marked by the presence of global and regional manufacturers focused on innovation, quality, and supply reliability. Leading players such as BASF SE, Evonik Industries AG, PPG Industries Inc., and W.R. Grace & Co. offer a broad portfolio of high-performance silica products tailored to diverse food applications. Companies like Madhu Silica Pvt. Ltd. and Hubei Bafang Chemical Industry Co. Ltd. strengthen regional supply capabilities, while firms such as Imerys S.A and Sibelco invest in sustainable production technologies. Competitive strategies include product customization, expansion into emerging markets, and partnerships with food manufacturers. The market also sees rising investment in R&D for clean-label and specialty formulations. It remains dynamic, with players competing on pricing, regulatory compliance, and technical support. Market leaders continuously optimize production efficiency and logistics to meet growing demand while maintaining consistent quality across global supply chains.
Recent Developments
- In 2024, the European Food Safety Authority (EFSA) reaffirmed the safety of synthetic amorphous silica (E551) as a food additive, including in food for infants. R. Grace & Co., along with other industry producers, contributed safety data and studies to support EFSA's assessment. The reaffirmation confirms that E551 is safe for use at current exposure levels in both general and infant food applications.
- On January 1, 2025, Evonik Industries AG launched its new “Smart Effects” division by merging its Silica and Silanes This strategic move aims to offer integrated, sustainable silica solutions, with applications in various industries including food and infant formula.
- In August 2024, PPG Industries Inc. agreed to sell its silica products business to Qemetica for USD 310 million, transferring production facilities in Louisiana (U.S.) and the Netherlands.
- In November 2024, Qemetica, a Polish chemical group, completed its acquisition of PPG’s precipitated silica business. The deal, initially announced in August 2024, strengthens Qemetica’s position as a major supplier of precipitated silica for food and animal feed across North America and Europe.
Market Concentration & Characteristics
The food grade silica market exhibits a moderately concentrated structure, with a mix of global corporations and specialized regional players shaping competition. Leading firms such as BASF SE, Evonik Industries AG, W.R. Grace & Co., and J.M. Huber Corporation hold significant market shares due to their scale, advanced technology, and global distribution capabilities. It features high entry barriers due to stringent regulatory requirements, technical formulation standards, and the need for consistent product quality. The market is characterized by ongoing innovation, with a strong focus on high-purity, eco-friendly, and application-specific silica grades. Product customization, strong supplier relationships, and compliance with food safety standards define competitive advantage. Regional companies play an important role in supplying cost-effective solutions to local markets, especially in Asia-Pacific. Demand for clean-label ingredients, extended shelf life, and performance in complex formulations further drives differentiation. The food grade silica market maintains steady growth, supported by stable end-use industries and rising global consumption trends.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for food grade silica will continue to rise due to increased consumption of processed and packaged foods.
- Manufacturers will focus on developing high-purity and eco-friendly silica to meet clean-label and sustainable food trends.
- Use of silica in functional foods and dietary supplements will expand with growing consumer interest in health and wellness.
- Innovation in nano-silica and advanced particle engineering will support new product applications in beverages and snacks.
- Regulatory compliance and food safety standards will remain central to product development and global market access.
- Growth in pet food and animal nutrition sectors will create new opportunities for silica-based formulations.
- Regional players in Asia-Pacific and Latin America will gain market share by offering cost-effective and tailored solutions.
- Expansion of e-commerce and direct-to-consumer models will boost demand for silica that supports longer shelf life.
- Strategic collaborations and R&D investments will drive competitive advantage and product differentiation.
- Volatility in raw material costs may influence pricing strategies and encourage supply chain optimization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Food Grade Silica Market?
What factors are driving the growth of the Food Grade Silica Market?
What are the key segments within the Food Grade Silica Market?
What are some challenges faced by the Food Grade Silica Market?
Who are the major players in the Food Grade Silica Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Grade Silica Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Grade Silica Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,888 million → 2032: USD 2,747 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Grade Silica Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Grade Silica Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Grade Silica Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Grade Silica Market Drivers
- 3.3 Food Grade Silica Market Restraints & Challenges
- 3.4 Food Grade Silica Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Grade Silica Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Grade Silica Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Grade Silica category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Grade Silica Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Food Grade Silica Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Food Grade Silica market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Grade Silica Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Grade Silica Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Food Grade Silica Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Grade Silica (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Food Grade Silica Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Grade Silica Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Food Grade Silica Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Grade Silica Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Grade Silica Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Grade Silica Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Grade Silica Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Grade Silica Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Grade Silica Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
