
Market Overview:
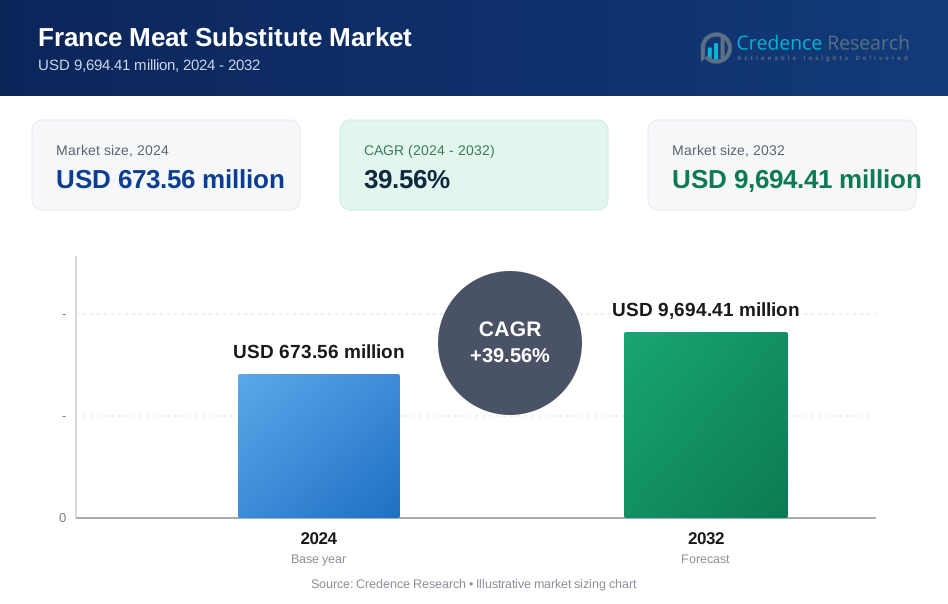
The France Meat Substitute Market size was valued at USD 209.21 million in 2018 to USD 673.56 million in 2024 and is anticipated to reach USD 9,694.41 million by 2032, at a CAGR of 39.56% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Meat Substitute Market Size 2024 | USD 673.56 million |
| France Meat Substitute Market, CAGR | 39.56% |
| France Meat Substitute Market Size 2032 | USD 9,694.41 million |
Consumer interest in plant-based proteins is rising due to health, ethical, and environmental concerns. France’s increasing vegan and flexitarian population is driving sustained demand for meat substitutes. Strong support from foodservice chains, retailers, and innovation in plant-based ingredients also strengthens adoption. Government-backed campaigns on sustainable food choices encourage consumers to switch toward alternatives. Advances in texture and flavor improvements further help in narrowing the gap with traditional meat.
Regional dynamics highlight Paris and other urban centers as the leading markets due to higher consumer awareness and stronger retail networks. Growth in suburban and semi-urban areas is emerging, supported by younger populations adopting plant-based diets. Western regions benefit from established distribution, while southern parts show rising interest driven by cultural openness to Mediterranean plant-rich diets. Increasing presence of international brands and local start-ups ensures geographic expansion across the country.

Market Insights:
- The France Meat Substitute Market was valued at USD 209.21 million in 2018, reached USD 673.56 million in 2024, and is expected to hit USD 9,694.41 million by 2032, registering a CAGR of 39.56% during 2024–2032.
- Western and Southern France hold the largest combined share of 41%, supported by Mediterranean dietary habits, tourism-driven foodservice growth, and rising adoption of pea-based and soy-based substitutes.
- Northern France follows with 32% market share, led by Paris and Lille, where higher disposable income, retail penetration, and early product launches fuel demand.
- Central and Eastern France account for 27% share, representing the fastest-growing region, driven by younger populations, university-led awareness, and expanding online retail accessibility.
- In 2024, tofu and Quorn (mycoprotein-based) together captured over 45% of product share, while seitan and tempeh collectively accounted for nearly 30%, reflecting strong demand for both traditional and innovative substitutes.
Market Drivers:
Rising Health Consciousness and Dietary Shifts
Growing health concerns and dietary awareness are central to demand. Consumers in France are reducing red meat intake due to risks of heart disease, obesity, and cholesterol-related issues. Plant-based proteins offer healthier alternatives, aligning with wellness-focused lifestyles. The France Meat Substitute Market benefits from this transition, supported by younger demographics. It is driven by strong awareness campaigns from public health bodies and NGOs. Retailers and restaurants are promoting healthier menus, further boosting acceptance. This momentum is expected to accelerate with urban populations prioritizing balanced diets.
- For instance, Danone S.A. has launched plant-based protein products incorporating Vertis CanolaPRO, a premium canola protein isolate introduced in November 2022 that enhances protein composition while avoiding common allergens, thereby supporting health-conscious consumer demands.
Strong Growth of Vegan and Flexitarian Populations
Veganism and flexitarianism are expanding rapidly in France, reshaping food preferences. Consumers are actively experimenting with plant-based foods for variety and sustainability. The France Meat Substitute Market is directly fueled by this demographic expansion. It is particularly evident in urban centers like Paris and Lyon, where vegan cafes and plant-based restaurants thrive. Marketing campaigns highlight ethical and ecological benefits, appealing to younger generations. Social media influence reinforces lifestyle choices, making plant-based eating mainstream. Flexitarian households provide significant recurring demand due to their partial but steady adoption.
- For instance, the French retail plant-based market across five key categories showed strong growth in 2024. French consumers purchased 232 million units and 147 million kilograms of these plant-based products, which reflected a 7.9% and 5.1% year-over-year increase, respectively. However, this data represents the market as a whole, and Beyond Meat reported a 4.9% decrease in its overall company net revenue for the full year 2024.
Innovation in Plant-Based Food Technology
Advances in food processing and biotechnology enhance texture, flavor, and nutritional profiles of substitutes. It is driving acceptance by narrowing differences between meat and plant-based products. Companies are investing in pea protein, soy protein, and fermented ingredients for improved authenticity. The France Meat Substitute Market benefits from these advancements as taste and variety grow. Local startups and multinational players launch new products to meet consumer expectations. Distribution expansion into mainstream supermarkets improves accessibility. Continuous innovation ensures higher consumer retention and greater repeat purchases.
Supportive Role of Government and Retail Expansion
French government policies encourage sustainable consumption patterns and reduced carbon footprints. It is creating incentives for consumers to adopt plant-based alternatives. Retail chains are allocating more shelf space for substitutes across categories. The France Meat Substitute Market grows with eco-labeling and sustainability certifications that build trust. Major foodservice providers integrate meat-free options into regular menus. Government-funded campaigns highlight climate-friendly eating, supporting market adoption. Combined efforts from public and private sectors create favorable conditions for long-term expansion.
Market Trends:
Expansion of Ready-to-Eat and Convenience-Based Plant Products
Busy lifestyles in urban France drive demand for convenience-focused plant-based meals. It is pushing manufacturers to launch ready-to-eat, frozen, and microwaveable options. Consumers prefer products that balance health and quick preparation. The France Meat Substitute Market benefits from strong demand in supermarkets and online platforms. Ready-to-eat plant burgers, sausages, and nuggets gain traction across demographics. Foodservice outlets are also expanding quick-serve vegan menus for professionals. This trend ensures long-term growth by combining taste, speed, and accessibility.
- For instance, the plant-based sausage brand Herta, which is now largely owned by the Spanish company Casa Tarradellas in a joint venture, with the vegetarian line retained by Nestlé, has rapidly expanded its vegetarian Knacki range and captured significant market share with convenient plant-based sausages distributed widely in retail and foodservice sectors.
Rise of Premium and Gourmet Plant-Based Segments
French consumers value culinary experience and taste quality in food choices. It is encouraging growth in premium meat substitute categories. The France Meat Substitute Market benefits from gourmet innovations such as plant-based steaks, deli meats, and artisan cheeses. Chefs integrate substitutes into high-end restaurant menus, enhancing acceptance. Premiumization allows brands to capture higher margins and appeal to affluent segments. Innovation focuses on authentic French cuisine adaptations, including pâtés and charcuterie. This trend strengthens cultural integration and broadens market acceptance.
- For instance, Bel Group partnered with Standing Ovation in November 2022 to develop an animal-free casein protein that replicates the nutritional and functional attributes of traditional cheese, allowing premium plant-based cheeses to enter gourmet culinary segments.
Integration of Sustainability in Consumer Decision-Making
Environmental sustainability is becoming a decisive factor in food purchasing. Consumers in France increasingly assess carbon footprints and ecological impacts. The France Meat Substitute Market aligns with these expectations by emphasizing eco-friendly sourcing and packaging. It is driving adoption among eco-conscious buyers seeking reduced environmental harm. Brands highlight regenerative agriculture, recyclable packaging, and local supply chains. Partnerships with sustainability-focused NGOs further strengthen consumer trust. This alignment with environmental goals ensures strong market credibility.
Growth of Online Retail and Direct-to-Consumer Channels
E-commerce expansion significantly boosts visibility and accessibility of plant-based products. It is helping brands reach consumers beyond urban areas. The France Meat Substitute Market is growing through dedicated online vegan stores and supermarket apps. Subscription-based delivery models ensure convenience and loyalty among households. Social media-driven marketing campaigns raise awareness of new launches. Direct-to-consumer models allow better engagement and personalized offerings. This trend supports widespread adoption across both metropolitan and regional markets.

Market Challenges Analysis:
Price Sensitivity and High Production Costs
Pricing remains a significant barrier for broader consumer adoption. Meat substitutes often cost more than traditional proteins due to advanced production methods and specialized ingredients. The France Meat Substitute Market is affected by these challenges, limiting penetration in middle-income households. It is also impacted by price competition between local startups and multinational brands. Distribution costs and reliance on imported raw materials add to consumer prices. Retailers face difficulty balancing affordability with profitability. Unless costs decline through scale, adoption may remain restricted.
Cultural Resistance and Perception Barriers
French food culture values traditional dishes, cheeses, and meat-rich meals. It is creating barriers for plant-based substitutes to fully integrate into mainstream cuisine. The France Meat Substitute Market faces skepticism about taste authenticity and nutritional value. Consumers loyal to traditional meat often resist alternatives, seeing them as artificial. Marketing campaigns face challenges in addressing these perceptions. Generational gaps also affect acceptance, with older populations slower to adopt. Strong culinary traditions require continuous innovation to gain wider trust.
Market Opportunities:
Expansion into Foodservice and Institutional Catering
Foodservice chains, universities, and corporate cafeterias are adding plant-based menus. It is giving brands direct access to a broad consumer base. The France Meat Substitute Market benefits from this institutional adoption, driving volume growth. Partnerships with restaurants and cafes enhance visibility among younger demographics. Catering contracts provide consistent, large-scale demand. These channels strengthen brand positioning and reduce dependence on retail alone. Expanding menus in airlines and hotels also create premium opportunities.
Product Diversification and Localization of Offerings
Adapting substitutes to local French culinary traditions offers strong growth potential. The France Meat Substitute Market benefits when brands tailor products to regional cuisines. It is creating higher acceptance by reflecting cultural authenticity in product lines. Companies introducing plant-based versions of pâté, sausages, or charcuterie appeal to traditional consumers. Regional festivals and gourmet events present strong promotional avenues. Collaborations with chefs enhance consumer trust and interest. Localized innovation is expected to strengthen long-term adoption.
Market Segmentation Analysis:
By Type
Textured protein (TVP) dominates demand due to its versatility in processed foods. Concentrates hold strong share in nutritional products, while isolates gain traction for premium protein-rich applications. The France Meat Substitute Market benefits from diverse use cases across these categories. It is driven by consumer preference for products balancing taste, texture, and nutritional value.
- For instance, Roquette introduced in February 2024 four multi-functional pea proteins designed to improve taste, texture, and formulation flexibility in plant-based meat and nutritional products, enhancing TVP and protein isolate applications.
By Source
Soy protein remains the most widely used source due to established supply chains and affordability. Wheat protein supports bakery and meat-alternative applications, while pea protein grows quickly with its allergen-free profile. Other sources such as fava beans and lentils expand niche offerings. It ensures broader consumer reach across dietary needs.
- For instance, Ingredion Incorporated and Archer Daniels Midland Company actively innovate in pea and soy protein segments to enhance texture and allergen-free options catering to diverse dietary requirements in France.
By Product
Tofu and tempeh maintain strong cultural and nutritional acceptance, while seitan appeals to high-protein consumers. Quorn, a mycoprotein-based option, builds popularity through unique texture and taste. Other products, including plant-based patties and sausages, widen the portfolio. The France Meat Substitute Market benefits from innovation in these categories, ensuring stronger shelf presence.
By Distribution Channel
Retail channels dominate sales, led by supermarkets and hypermarkets offering wide product assortments. Convenience stores and specialty outlets expand accessibility for targeted buyers. Online retail strengthens growth by catering to tech-savvy and urban consumers. Foodservice adoption grows as restaurants, QSRs, and hotels integrate plant-based menus. It reinforces consumer awareness and boosts trial opportunities.

Segmentation:
- By Type
- Textured Protein (TVP)
- Concentrates
- Isolates
- By Source
- Soy Protein
- Wheat Protein
- Pea Protein
- Other Sources
- By Product
- Tofu
- Tempeh
- Seitan
- Quorn (mycoprotein-based)
- Others
- By Distribution Channel
- Retail
- Supermarkets / Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Retail
- Foodservice
- Restaurants
- Quick Service Restaurants (QSRs)
- Hotels & Catering
- Retail
Regional Analysis:
Northern France
Northern France accounts for around 32% of the market share, driven by high population density and strong urbanization. Cities such as Paris and Lille act as major consumption hubs due to health-conscious consumers and higher disposable income. The France Meat Substitute Market benefits from strong retail penetration in supermarkets and hypermarkets across this region. It is further supported by active government initiatives on sustainable food adoption. Local startups and global brands often test launches in this region, leveraging its dynamic consumer base. Growing popularity of flexitarian diets continues to expand product acceptance.
Western and Southern France
Western and Southern France together represent nearly 41% of the market share, supported by cultural openness to plant-rich Mediterranean diets. Cities such as Bordeaux, Toulouse, and Marseille show rising adoption of tofu, tempeh, and pea-based products. The France Meat Substitute Market gains momentum in these regions through a mix of traditional retailers and specialty organic stores. It is further reinforced by strong tourism activity, which supports plant-based offerings in restaurants and hotels. Foodservice adoption is higher, with QSR chains actively introducing plant-based menus. Rising awareness of sustainability further strengthens long-term growth in these regions.
Central and Eastern France
Central and Eastern France account for approximately 27% of the market share, emerging as a key growth frontier. Rural and semi-urban populations are slower adopters, but rising online retail penetration improves access. The France Meat Substitute Market benefits from growing acceptance among younger consumers in cities such as Lyon and Strasbourg. It is also supported by government-led sustainability campaigns and university-led awareness programs. Regional manufacturers experiment with localized flavors to enhance product acceptance. Increasing expansion of convenience stores helps strengthen visibility in suburban and rural areas.
Key Player Analysis:
Competitive Analysis:
The France Meat Substitute Market is highly competitive, shaped by domestic innovators and global leaders. Local companies such as Les Nouveaux Fermiers (HappyVore), Umiami, and La Vie compete with established multinational brands like Roquette and BENEO. It is driven by continuous innovation in plant-based ingredients, product diversification, and retail penetration. Companies are focusing on improving taste and texture to appeal to traditional consumers while ensuring sustainable sourcing practices. Strategic partnerships with foodservice chains and retailers help expand visibility. Startups leverage agility to introduce niche offerings, while established firms invest heavily in R&D and distribution. Competitive intensity is rising as more players enter the market with diverse product portfolios.
Recent Developments:
- Gourmey focuses on cultivated meat delicacies with sustainable and high-quality offerings, although no specific recent product launch, acquisition, or partnership news was identified for 2025 in the France meat substitute market.
- In June 2025, Roquette expanded its NUTRALYS® portfolio with two new textured protein solutions, including its first-ever textured wheat protein, NUTRALYS® T WHEAT 600L, and a large-chunk textured pea protein, NUTRALYS® T PEA 700XC, designed to meet the growing demand for fibrous, chicken-style meat alternatives and hearty dishes, respectively.
Report Coverage:
The research report offers an in-depth analysis based on type, source, product, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for clean-label and allergen-free protein sources will rise steadily.
- Premium and gourmet substitutes tailored to French cuisine will gain traction.
- Expansion into regional cities beyond Paris will fuel adoption.
- Foodservice collaborations with restaurants and QSRs will drive higher visibility.
- E-commerce and direct-to-consumer channels will account for stronger sales.
- Government-backed sustainability campaigns will continue to support growth.
- Price optimization strategies will help reduce adoption barriers.
- Advances in fermentation and biotechnology will enhance product quality.
- Startups will attract strong investment for scaling production capacity.
- Consumer education and awareness programs will strengthen long-term loyalty.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for France Meat Substitute Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Meat Substitute Market projected to grow between 2024 and 2032?
Which France Meat Substitute Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Meat Substitute Market?
Who are the leading companies in the France Meat Substitute Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Meat Substitute Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Meat Substitute Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 673.56 million → 2032: USD 9,694.41 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Meat Substitute Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Meat Substitute Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Meat Substitute Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Meat Substitute Market Drivers
- 3.3 France Meat Substitute Market Restraints & Challenges
- 3.4 France Meat Substitute Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Meat Substitute Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Meat Substitute Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Meat Substitute category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Meat Substitute Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Meat Substitute Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Meat Substitute market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Meat Substitute Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Meat Substitute Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Meat Substitute Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Meat Substitute (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Meat Substitute Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Meat Substitute Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Meat Substitute Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Meat Substitute Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Meat Substitute Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Meat Substitute Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Meat Substitute Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Meat Substitute Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Meat Substitute Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
