
Market Overview
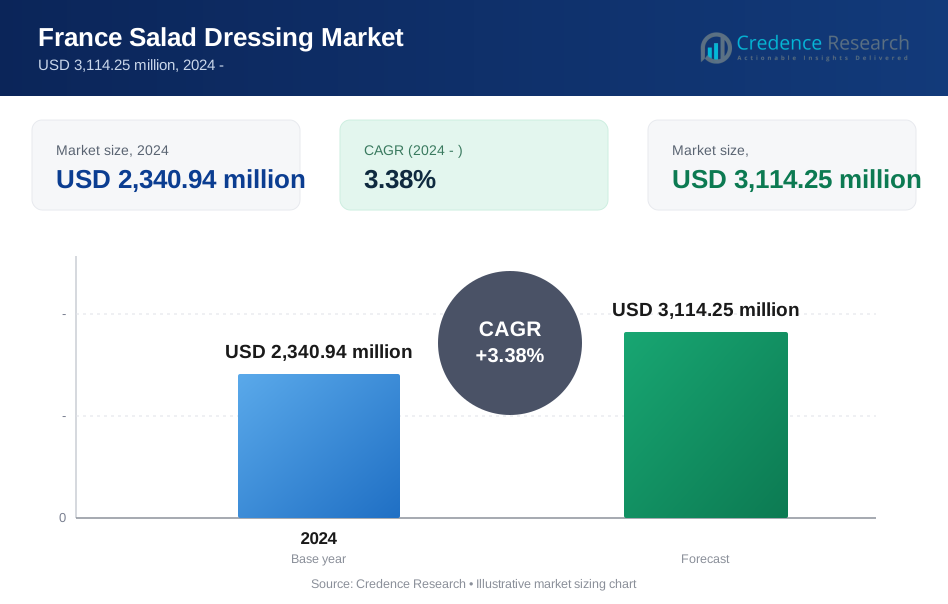
France Salad Dressing Market size was valued at USD 1,865.63 million in 2018 to USD 2,340.94 million in 2024 and is anticipated to reach USD 3,114.25 million by 2032, at a CAGR of 3.38% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Salad Dressing Market Size 2024 | USD 2,340.94 Million |
| France Salad Dressing Market, CAGR | 3.38% |
| France Salad Dressing Market Size 2032 | USD 3,114.25 Million |
The France Salad Dressing Market features strong competition among global and domestic players, with leading companies including Dr. Oetker, Remia, McCormick & Company, Unilever’s Amora-Maille, Lesieur, Paul and Pippa, Cassegrain, Jacquet, Les Moulins de Kleinbettingen, and Glon Sanders. These firms compete through product innovation, wide distribution networks, and diverse portfolios spanning conventional, organic, and premium offerings. Private labels from major retailers further intensify the market landscape, catering to price-sensitive consumers. Regionally, North France leads with a 29% market share, supported by high urban populations, dominance of mayonnaise and sauces, and strong foodservice growth in cities such as Lille. This combination of global presence, regional strength, and evolving consumer preferences shapes the market’s competitive dynamics.
Market Insights
- The France Salad Dressing Market grew from USD 1,865.63 million in 2018 to USD 2,340.94 million in 2024 and will reach USD 3,114.25 million by 2032.
- Mayonnaise dominates with a 36% share, while sauces hold 22% and vinaigrettes capture 16%, reflecting consumer preference for both traditional and healthier options.
- Conventional products lead with 71% share, but organic dressings at 29% are rising due to health awareness and clean-label demand among French consumers.
- Retail stores command 58% share, foodservice contributes 28%, and other off-trade channels at 14% are gaining traction with digital shopping growth.
- North France leads regionally with 29% share, followed by West France at 26%, South France at 24%, and East France at 21%, each reflecting distinct consumer preferences.
Market Segment Insights
By Product Type
Mayonnaise dominates the France Salad Dressing Market with a 36% share, driven by its strong role in traditional French cuisine and wide application in sandwiches, dips, and ready-to-eat meals. Sauces hold a 22% share, supported by consumer demand for variety in flavors. Oil-based dressings, including vinaigrettes, account for 16%, benefiting from health-conscious consumers seeking lighter options. Balsamic dressing captures 10%, boosted by its pairing with premium salads and gourmet dishes. Ranch and Italian dressings together represent 9%, favored among younger consumers influenced by Western dining. Other niche varieties contribute 7%, appealing to experimental and premium buyers.
For instance, Lesieur, a French edible oil brand, launched an 'Apple Honey cider Vinegar' vinaigrette to offer a lower-fat option and capitalize on the consumer appeal of health-conscious ingredients like apple cider vinegar
By Category
Conventional products lead with a 71% share, sustained by affordability and easy availability across supermarkets and hypermarkets. Strong brand loyalty and familiarity further reinforce their dominance. Organic salad dressings, holding 29%, are expanding steadily as health-conscious consumers prioritize clean-label ingredients. The growth of organic retail sections and rising regulatory support for natural food products are accelerating adoption in this segment.
For instance, Litehouse Foods expanded its organic dressings line by adding organic ranch and Caesar flavors, citing increasing demand from natural food retailers like Whole Foods Market.
By Distribution Channel
Retail stores command the largest share at 58%, supported by supermarket penetration, private labels, and promotional strategies that influence consumer purchase decisions. Foodservice contributes 28%, driven by the increasing demand for salad dressings in quick-service restaurants, cafés, and casual dining. Other off-trade channels, holding 14%, including online platforms and specialty outlets, are gaining traction as digital shopping and home delivery trends reshape consumer buying habits.
Rising Demand for Convenience Foods
The increasing preference for ready-to-eat meals and quick-preparation options drives demand for salad dressings in France. Busy lifestyles and dual-income households encourage consumers to choose packaged condiments for convenience. Mayonnaise and sauces benefit most, as they complement fast meals like sandwiches and salads. The expansion of retail outlets further strengthens access to diverse product types. This trend positions salad dressings as essential kitchen staples, boosting their role in everyday consumption.
For instance, Lesieur developed new vegan mayonnaise products to cater to health-conscious and plant-based diet consumers, reflecting changing lifestyle choices and convenience preferences.
Shift Toward Health-Conscious Choices
French consumers are increasingly attentive to nutritional value, pushing demand for lighter and healthier dressing options. Oil-based vinaigrettes and balsamic dressings gain traction due to perceived health benefits and natural positioning. Rising awareness about obesity and cardiovascular risks supports the shift from calorie-dense mayonnaise to organic and low-fat alternatives. Manufacturers are innovating with reduced sugar and salt formulations, appealing to wellness-focused buyers. This driver aligns with broader European health initiatives, further supporting market growth.
For instance, Kraft Heinz has committed to improving the nutritional profiles of its products globally by incrementally reducing sugar, salt, and fat to align with both internal targets and government-backed health guidelines in various markets, including France
Expansion of Foodservice Industry
Growth in the foodservice sector, including quick-service restaurants, cafés, and catering services, significantly contributes to salad dressing consumption. The increasing adoption of salads as main meals in urban dining supports consistent demand. French culinary culture, known for gourmet dishes, boosts the integration of diverse dressing varieties. Partnerships between dressing brands and foodservice operators enhance visibility and customer loyalty. Rising tourism also contributes, as international visitors embrace French cuisine paired with local dressing products.
 Key Trends & Opportunities
Growth of Organic and Clean-Label Products
The organic segment is expanding rapidly, supported by consumer demand for clean-label products. French buyers increasingly value transparency in sourcing, natural ingredients, and eco-friendly packaging. Brands focusing on organic certifications and sustainable production methods gain a competitive edge. Retailers are dedicating shelf space to organic dressings, strengthening visibility. This trend offers opportunities for premium pricing and strong brand differentiation, making it a profitable niche within the wider market.
For instance, Nestlé's overall strategy includes premiumization and diverse pricing strategies. Nestlé has previously implemented premium pricing on certain products, leveraging unique benefits and brand image
Digital Retail and Direct-to-Consumer Expansion
E-commerce platforms and direct-to-consumer strategies are reshaping how salad dressings reach French households. Online grocery platforms, subscription models, and specialty food sites create new growth channels. Consumers value the convenience of doorstep delivery and wider access to niche or imported brands. Manufacturers can leverage digital marketing to target health-conscious and experimental buyers more effectively. This opportunity enhances product reach and supports personalized engagement, further expanding market potential.
For instance, the French online grocery platform Carrefour offers various delivery and subscription-based services for everyday items, utilizing its e-commerce platform to boost brand visibility and convenience with doorstep delivery.
Key Challenges
Intense Competitive Landscape
The France Salad Dressing Market is highly competitive, with local brands and international players vying for share. Price competition is significant, especially in retail channels where private labels exert pressure. Established brands must continually innovate and invest in marketing to differentiate themselves. Smaller players face barriers in distribution and visibility, making it harder to compete effectively. This crowded landscape reduces margins and challenges profitability across the segment.
Regulatory Compliance and Labeling Standards
Strict EU regulations on food safety, labeling, and ingredient transparency pose challenges for manufacturers. Companies must ensure compliance with allergen declarations, nutritional labeling, and clean-label claims. These regulations increase operational costs and require constant monitoring to avoid penalties. Smaller firms often struggle with compliance expenses, slowing expansion. While regulations improve consumer trust, they add complexity to market entry and long-term sustainability strategies.
Shifting Consumer Preferences
Consumer tastes in France are evolving quickly, making demand less predictable for manufacturers. Younger generations favor international flavors and experimental varieties, while traditional buyers remain loyal to mayonnaise and vinaigrettes. Balancing innovation with heritage products becomes a key challenge. Brands that fail to adapt to evolving trends risk losing relevance. This shifting landscape forces continuous product development, which increases costs and shortens product life cycles.
 Regional Analysis
North France
North France holds a 29% share of the France Salad Dressing Market, supported by strong urban populations and a preference for convenience foods. It benefits from the dominance of mayonnaise and sauces, which remain popular in household and foodservice channels. Retail stores play a central role in driving sales, supported by private labels and regional supermarket chains. Growing demand for organic dressings also enhances category diversification in this region. The foodservice industry in cities such as Lille supports higher consumption. It continues to act as a growth hub for both traditional and modern salad dressing categories.
South France
South France accounts for a 24% share, driven by Mediterranean dietary preferences that favor oil-based dressings and vinaigrettes. Consumers in this region prioritize lighter, healthier options, boosting adoption of balsamic and organic products. Tourism contributes to steady sales, with restaurants and hotels incorporating diverse dressing varieties. Retail channels remain the largest contributors, though foodservice is expanding quickly. It demonstrates strong demand for premium and gourmet products that complement local cuisine. The region’s cultural alignment with fresh and healthy foods sustains ongoing growth.
East France
East France represents a 21% share, led by a mix of traditional and modern preferences in salad dressings. Mayonnaise and sauces dominate, though vinaigrettes are gaining momentum due to health trends. Retail stores drive the largest share, supported by established local suppliers and distribution networks. Rising consumer awareness of clean-label products has supported organic adoption in this region. It also benefits from cross-border trade influences that introduce diverse dressing flavors. Continued innovation in packaging and flavors is enhancing its market performance.
West France
West France captures a 26% share, making it the second-largest contributor after North France. Mayonnaise remains the leading product type, supported by household consumption and strong presence in regional cuisines. Foodservice demand is increasing, with cafés and quick-service outlets incorporating ranch and Italian dressings. Organic varieties are steadily penetrating this market, aligned with consumer interest in natural ingredients. It leverages its retail network to ensure widespread product availability. The region’s balanced demand across conventional and organic categories supports sustainable growth in the France Salad Dressing Market.
 Market Segmentations:
By Product Type
- Mayonnaise
- Sauces
- Oil-Based Dressings (Vinaigrettes)
- Balsamic Dressing
- Ranch Dressing
- Italian Dressing
- Others
By Category
- Conventional
- Organic
By Distribution Channel
- Foodservice
- Retail Stores
- Other Off-Trade Channels
By Region
- Northern France
- Southern France
- Eastern France
- Western France
Competitive Landscape
The France Salad Dressing Market is highly competitive, featuring a mix of multinational corporations, regional producers, and private labels. Established players such as Dr. Oetker, Remia, McCormick & Company, and Unilever’s Amora-Maille lead with strong brand recognition, extensive product portfolios, and wide distribution networks. Domestic firms like Lesieur and niche brands including Paul and Pippa add diversity by offering gourmet and organic alternatives. Private labels from major French retailers strengthen competition by targeting price-sensitive consumers. Companies invest in product innovation, introducing low-fat, organic, and clean-label dressings to align with shifting health preferences. Strategic partnerships with foodservice providers and supermarkets enhance visibility, while promotional campaigns support consumer engagement. Competitive intensity remains high as players focus on differentiation through flavor innovation, sustainable packaging, and premium positioning. This environment drives continuous innovation and ensures that both global and local players adapt quickly to evolving consumer demands in the French market.
Key Players
- Remia C.V.
- Oetker
- McCormick & Company
- Lesieur
- Amora-Maille (Unilever)
- Paul and Pippa
- Cassegrain
- Jacquet
- Les Moulins de Kleinbettingen
- Glon Sanders
Recent Developments
- In September 2025, Dole launched its Apple Harvest Premium Salad Kit featuring an apple cider vinaigrette, responding to consumer demand for unique, restaurant-inspired salad experiences at home.
- In August 2024, Bonduelle Group entered exclusive negotiations to sell its packaged salad business in France to Les Crudettes, part of the LSDH Group, amid a structural decline in salad consumption in France.
- In April 2025, Hidden Valley launched seven new ranch flavor varieties along with a redesigned "Easy Squeeze" bottle, catering to flavor innovation and customization trends.
- In April 2025, Taylor Farms and Foodiverse completed the acquisition of Bonduelle’s salad operations in Germany, strengthening their ready-to-eat salads presence.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Category, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for organic and clean-label salad dressings will continue to expand.
- Retailers will strengthen private label offerings to capture price-sensitive buyers.
- Foodservice adoption of diverse dressing varieties will rise with menu diversification.
- Online grocery platforms will increase accessibility for premium and niche products.
- Innovation in low-fat and reduced-sodium dressings will gain stronger consumer interest.
- Sustainable packaging solutions will become a standard expectation among French consumers.
- Regional tastes will drive new flavor introductions tailored to local preferences.
- Partnerships between dressing brands and restaurants will enhance visibility and sales.
- Marketing strategies will focus on health benefits and natural ingredients to build loyalty.
- Competition between global leaders and local brands will intensify, fostering rapid innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for France Salad Dressing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Salad Dressing Market projected to grow between 2025 and 2032?
Which France Salad Dressing Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Salad Dressing Market?
Who are the leading companies in the France Salad Dressing Market?
Which region commanded the largest share of the France Salad Dressing Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Salad Dressing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Salad Dressing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 2,340.94 million → forecast year: USD 3,114.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Salad Dressing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Salad Dressing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Salad Dressing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Salad Dressing Market Drivers
- 3.3 France Salad Dressing Market Restraints & Challenges
- 3.4 France Salad Dressing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Salad Dressing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Salad Dressing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Salad Dressing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Salad Dressing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Salad Dressing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Salad Dressing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Salad Dressing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Salad Dressing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Salad Dressing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Salad Dressing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Salad Dressing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Salad Dressing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Salad Dressing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Salad Dressing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Salad Dressing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Salad Dressing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Salad Dressing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Salad Dressing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Salad Dressing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
