
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Functional Service Providers (FSP) Market Size 2024 | USD 16,945 Million |
| Functional Service Providers (FSP) Market, CAGR | 8.90% |
| Functional Service Providers (FSP) Market Size 2032 | USD 33,515.97 Million |
Market Overview:
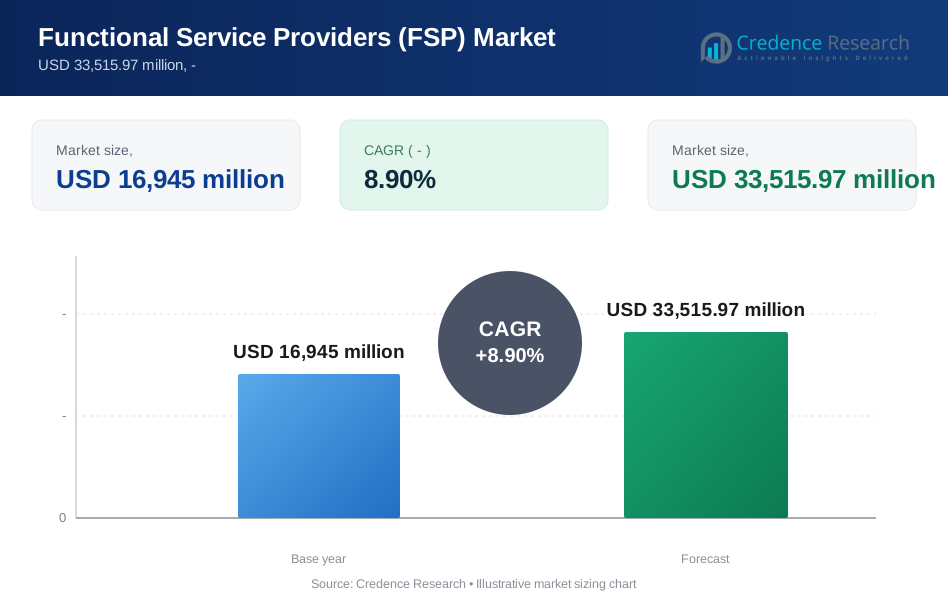
The Functional Service Providers (FSP) Market is experiencing substantial growth, driven by the increasing demand for specialized services in the clinical research and development sector. As of 2024, the global Functional Service Providers (FSP) Market is valued at approximately USD 16,945 million and is projected to grow at a compound annual growth rate (CAGR) of 8.90% over the forecast period, reaching around USD 33,515.97 million by 2032. This robust growth reflects the rising need for efficient and cost-effective solutions in clinical trials, as well as the growing complexity of drug development processes.
Several key factors are propelling the market's expansion. The increasing outsourcing of clinical functions by pharmaceutical and biotech companies is a significant driver, as organizations seek to enhance operational efficiency and focus on core competencies. Moreover, the growing complexity of regulatory requirements and the need for compliance are prompting organizations to engage specialized FSPs to navigate these challenges effectively. The integration of innovative technologies, such as data analytics and real-time monitoring tools, is further contributing to market growth by improving the quality and speed of clinical trials.
Regionally, North America dominates the Functional Service Providers Market, primarily due to the presence of a well-established pharmaceutical industry, significant investments in research and development, and a robust regulatory framework. Europe follows closely, supported by a strong focus on innovation in healthcare and a growing number of clinical trials. The Asia-Pacific region is anticipated to witness remarkable growth during the forecast period, driven by the increasing adoption of FSP services, expanding healthcare infrastructure, and a rising number of clinical trials in emerging economies such as China and India. These markets are expected to offer substantial growth opportunities due to their large populations and increasing investments in healthcare services.
Market Drivers:
Increasing Investment in Healthcare Research:
One of the primary drivers of growth in the Functional Service Providers (FSP) Market is the increasing investment in healthcare research and development. Government bodies and international organizations, such as the World Bank and the International Monetary Fund (IMF), have highlighted the critical importance of investing in healthcare to drive economic growth and improve public health outcomes. For instance, the World Bank reported that global investment in health research is expected to grow by 5% annually through 2025. This uptick in funding supports the need for FSPs to provide specialized services that can help pharmaceutical and biotechnology companies navigate the complexities of clinical trials. As companies allocate more resources to innovative drug development and medical technologies, they increasingly rely on FSPs for expertise in clinical operations, regulatory compliance, and patient recruitment. This growing emphasis on research investment ensures a consistent demand for FSP services, enhancing the overall market landscape.
Regulatory Evolution and Adaptation:
The dynamic nature of regulatory requirements also drives the FSP Market. Regulatory authorities such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) continuously adapt their guidelines to accommodate advancements in technology and evolving healthcare needs. For instance, in 2022, the FDA introduced new frameworks for digital health technologies, which encouraged FSPs to enhance their offerings in digital trial management and data collection. This evolution necessitates that FSPs remain agile and well-informed about regulatory changes, allowing them to provide up-to-date compliance services to their clients. As regulations become more stringent and comprehensive, pharmaceutical and biotechnology companies are increasingly turning to FSPs to ensure that their trials meet all necessary standards, thus driving market growth. The increasing complexity of global clinical trials further amplifies this trend, as companies seek to navigate varying regulations across different jurisdictions effectively.
Focus on Patient-Centric Approaches:
There is a growing emphasis on patient-centric approaches in clinical research, which is significantly driving the FSP Market. Recognizing the importance of patient engagement and retention, regulatory authorities, including the FDA and EMA, have issued guidelines encouraging more inclusive and participatory trial designs. This shift has led to a higher demand for services that focus on improving patient experiences and outcomes throughout the clinical trial process. FSPs play a critical role in this transformation by offering tailored patient recruitment strategies, enhancing communication channels, and leveraging technology to improve patient access to trials. For example, a study conducted by the Patient-Centered Outcomes Research Institute (PCORI) revealed that patient-centered trials could increase enrollment rates by up to 30%. As a result, FSPs that prioritize patient-centric methodologies are likely to gain a competitive edge and attract more clients, further propelling market growth.
Adoption of Advanced Technologies:
The rapid adoption of advanced technologies in clinical trials is another key driver of the FSP Market. As organizations seek to enhance the efficiency and accuracy of their trial processes, they increasingly rely on FSPs to implement innovative solutions, such as artificial intelligence (AI), machine learning, and big data analytics. These technologies facilitate faster patient identification, more efficient data management, and improved trial monitoring, significantly reducing time-to-market for new therapies. According to a report by the International Data Corporation (IDC), investment in AI for healthcare is projected to grow at a rate of 28% annually through 2025. This technological evolution creates substantial opportunities for FSPs to integrate cutting-edge solutions into their service offerings, thereby increasing demand for their expertise. Furthermore, regulatory bodies are recognizing the potential of technology to enhance clinical trials, leading to an increased acceptance of digital tools and methodologies. This trend positions FSPs as essential partners in helping companies navigate the complexities of modern clinical research while ensuring compliance and quality.
Overall, the interplay of these market drivers-rising investments in healthcare research, evolving regulatory landscapes, a focus on patient-centric approaches, and the adoption of advanced technologies-creates a fertile environment for the continued growth of the FSP Market. As these trends unfold, FSPs that can adapt and innovate will be well-positioned to capitalize on the opportunities presented by this dynamic industry.
Market Trends:
Emphasis on Decentralized Clinical Trials:
One of the prominent trends shaping the Functional Service Providers (FSP) Market is the increasing focus on decentralized clinical trials (DCTs). Regulatory authorities, including the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), have issued guidelines that encourage the adoption of DCT methodologies to enhance patient access and improve trial efficiency. DCTs leverage technology to allow remote patient monitoring, virtual visits, and the use of mobile health applications, thereby reducing the burden on participants and increasing enrollment rates. The shift toward decentralized models aligns with the growing demand for patient-centric approaches in clinical research. For Instance, In November 2022, Excelya Group, a well-known CRO partner, announced the opening of a new office in Durham, North Carolina's Research Triangle Park. Since establishing a presence in the U.S. in 2019, Excelya’s new office will further enhance the company's growth and capabilities in North America, enabling it to deliver comprehensive solutions across its Full-Service, Functional Service Provision, and Contract Staff Resourcing business models.
According to a report from the World Health Organization (WHO), implementing decentralized trials can lead to a 20-30% increase in patient retention and engagement, as they reduce logistical challenges and make participation more convenient. As a result, FSPs are increasingly adopting technologies such as telehealth platforms and digital data collection tools to facilitate these trials. This trend not only improves patient experience but also enhances data quality and accelerates the trial timeline. The emphasis on decentralized trials reflects a broader industry movement towards leveraging technology to optimize clinical research processes and meet evolving patient needs.
Integration of Artificial Intelligence and Machine Learning:
Another significant trend in the FSP Market is the integration of artificial intelligence (AI) and machine learning (ML) technologies into clinical trial processes. As organizations seek to harness the power of data analytics, FSPs are increasingly utilizing AI and ML to enhance various aspects of clinical research, from patient recruitment to data analysis. These technologies enable faster identification of suitable candidates, predictive analytics for trial outcomes, and improved monitoring of trial progress. The International Data Corporation (IDC) projects that investments in AI for healthcare will exceed $50 billion by 2025, underscoring the growing reliance on these technologies. Regulatory bodies, such as the FDA, are also recognizing the potential of AI to transform clinical research. For example, in 2021, the FDA launched a pilot program to explore the use of AI and ML in reviewing clinical trial data, signalling a shift towards accepting innovative technologies as part of the regulatory process. The application of AI and ML in clinical trials helps to streamline operations, reduce costs, and enhance decision-making. For example, a study published by the National Institutes of Health (NIH) indicated that using AI-driven analytics could decrease patient enrollment timelines by up to 50%. As FSPs continue to integrate these advanced technologies into their service offerings, they are likely to improve overall trial efficiency and effectiveness. the trends of decentralized clinical trials and the integration of artificial intelligence and machine learning are significantly influencing the FSP Market. As regulatory authorities support these developments and organizations prioritize patient-centric methodologies, FSPs that adapt to these trends will be well-positioned for growth and success in the evolving landscape of clinical research. These trends not only reflect a shift in how clinical trials are conducted but also underscore the industry's commitment to improving patient experiences and outcomes while leveraging technology for enhanced operational efficiency.
Market Challenge Analysis:
Regulatory Compliance and Complexity:
One of the primary challenges facing the Functional Service Providers (FSP) Market is navigating the intricate landscape of regulatory compliance. As clinical trials are subject to rigorous oversight by various regulatory bodies, including the FDA in the United States and EMA in Europe, FSPs must ensure that their operations adhere to a multitude of guidelines and standards. This complexity increases with the globalization of clinical trials, as different countries often have unique regulatory requirements. Consequently, FSPs must invest significant resources in understanding and implementing these regulations to avoid delays, costly fines, or trial rejections. Failure to comply not only jeopardizes specific trials but can also tarnish the reputation of the FSP and its clients, leading to a loss of trust in their services. Additionally, the ongoing evolution of regulations-prompted by advancements in technology and changing healthcare landscapes-demands continuous adaptation. FSPs need to remain agile and proactive in monitoring regulatory updates, necessitating robust compliance management systems and ongoing training for staff.
Data Security and Privacy Concerns:
Another significant challenge impacting the FSP Market is the increasing emphasis on data security and patient privacy. Clinical trials generate vast amounts of sensitive data, including personal health information (PHI) of participants. The rise of data breaches and cyber threats has heightened concerns among stakeholders about safeguarding this information. FSPs must implement stringent data protection measures to comply with regulations such as the Health Insurance Portability and Accountability Act (HIPAA) in the U.S. and the General Data Protection Regulation (GDPR) in Europe. Failure to ensure data security can lead to severe consequences, including legal repercussions and financial losses. Furthermore, breaches can undermine public confidence in clinical research and deter patient participation. As FSPs increasingly leverage advanced technologies, such as cloud computing and artificial intelligence, they must balance innovation with robust security protocols. This necessitates continuous investment in cybersecurity infrastructure and staff training to mitigate risks. The evolving landscape of data protection laws also requires FSPs to stay informed and agile, adapting their practices to meet new requirements while maintaining operational efficiency. Ultimately, addressing these data security and privacy concerns is critical for FSPs to maintain their credibility and ensure the success of clinical trials.
Market Segmentation Analysis:
By Type
The Functional Service Providers (FSP) Market can be segmented by service type into several key categories. Clinical development services constitute a significant portion, focusing on managing the entire process of clinical trials from planning to execution. Data management services are essential for ensuring the integrity and accuracy of clinical data, while biostatistics services provide critical statistical analysis required for trial outcomes. Regulatory affairs services are increasingly important, helping companies navigate complex regulatory environments. Additionally, patient recruitment services play a crucial role in enhancing enrollment rates in clinical trials. Other specialized services, such as pharmacovigilance and post-market surveillance, are also gaining traction as companies seek comprehensive solutions for their clinical research needs.
By Technology
Technological advancements significantly influence the segmentation of the FSP Market. Cloud-based solutions are becoming the preferred choice for many organizations due to their scalability, flexibility, and cost-effectiveness. These solutions facilitate collaboration and real-time data access, which are crucial for managing clinical trials efficiently. On-premise solutions still hold value for organizations with specific data security requirements, while mobile-based solutions are emerging to enhance accessibility and streamline communication among stakeholders. Hybrid solutions, combining both cloud and on-premise technologies, are also gaining popularity as they offer the best of both worlds, allowing organizations to tailor their IT infrastructure according to their needs. Overall, the integration of advanced technologies, including artificial intelligence and machine learning, is transforming the operational landscape of FSPs.
By End-User
The FSP Market is segmented by end-user, primarily encompassing pharmaceutical companies, biotechnology firms, and medical device companies. Pharmaceutical companies represent a significant share, as they heavily rely on FSPs to manage complex clinical trials efficiently. Biotechnology firms are also key players, often seeking specialized services to support innovative drug development. Medical device companies increasingly engage FSPs to navigate the unique challenges of clinical research in their sector. Academic and research institutions represent another important segment, as they often partner with FSPs to conduct trials while leveraging external expertise. Finally, contract research organizations (CROs) themselves are significant end-users, utilizing FSPs to enhance their service offerings and optimize operational efficiencies in clinical research.
Segmentation:
Based on Service Type:
- Clinical Development Services
- Data Management Services
- Biostatistics Services
- Regulatory Affairs Services
- Patient Recruitment Services
- Pharmacovigilance Services
- Other Specialized Services
Based on Region:
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa
Based on Client Type:
- Pharmaceutical Companies
- Biotechnology Firms
- Medical Device Companies
- Academic and Research Institutions
- Contract Research Organizations (CROs)
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America (45%)
North America holds the largest share of the Functional Service Providers (FSP) Market, accounting for approximately 45% of the total market value. This dominance is primarily driven by the presence of a well-established pharmaceutical and biotechnology sector, characterized by significant investment in research and development. The region benefits from a robust regulatory framework, which encourages compliance and quality in clinical trials, making it an attractive hub for FSPs.
In addition, North American companies are increasingly outsourcing clinical functions to optimize operational efficiency and focus on core competencies. The demand for specialized expertise in complex trials further fuels market growth in this region. Major players such as Covance, PAREXEL, and IQVIA have extensive operations in North America, leveraging advanced technologies and comprehensive service offerings to meet the evolving needs of clients. The increasing adoption of innovative solutions, including data analytics and artificial intelligence, is also enhancing the efficiency of clinical trials, further solidifying North America’s leading position in the FSP Market.
Europe (30%)
Europe represents the second-largest market for Functional Service Providers, with a share of approximately 30%. The region is characterized by a strong emphasis on regulatory compliance and patient safety, which drives demand for high-quality FSP services. The presence of numerous pharmaceutical companies and research institutions fosters a competitive environment, where collaboration between FSPs and these organizations becomes increasingly vital.
Key markets within Europe, such as Germany, the United Kingdom, and France, are seeing substantial investments in clinical research. European FSPs are capitalizing on these opportunities by expanding their service offerings to include specialized areas like biostatistics, regulatory affairs, and data management. The region is also experiencing a growing focus on patient-centric approaches, which necessitates innovative trial designs and methodologies.
Emerging trends, such as the increasing integration of digital technologies and the use of real-world evidence, are shaping the competitive landscape. Companies are striving to enhance patient recruitment and retention strategies while addressing the complexities of multi-regional trials. Overall, Europe’s diverse healthcare landscape, coupled with a strong regulatory environment, positions it as a critical player in the global FSP Market.
Asia-Pacific (25%)
The Asia-Pacific region is witnessing rapid growth in the Functional Service Providers Market, capturing approximately 25% of the overall market share. This growth is driven by several factors, including expanding healthcare infrastructure, increasing investments in clinical research, and a rising number of clinical trials being conducted in emerging economies such as China and India.
Governments in the Asia-Pacific region are increasingly focusing on improving healthcare services and investing in research and development initiatives, which fosters a conducive environment for FSPs. The region's large population and diverse patient demographics offer unique opportunities for companies seeking to conduct clinical trials with varied participant profiles.
Moreover, the Asia-Pacific market is characterized by a blend of local and international players, with many global FSPs establishing a presence to tap into this high-growth market. Local firms often offer specialized knowledge of regional regulations and patient populations, making them valuable partners for multinational pharmaceutical companies. The increasing demand for cost-effective solutions, combined with the growing adoption of advanced technologies, such as cloud computing and mobile health applications, is further propelling the market forward.
As the region continues to evolve, FSPs are likely to focus on enhancing their capabilities to manage complex trial designs, navigate regulatory landscapes, and address the unique challenges posed by diverse patient populations. Overall, the Asia-Pacific region presents substantial growth opportunities for Functional Service Providers, driven by its expanding healthcare landscape and increasing focus on innovation in clinical research.
Key Player Analysis:
- IQVIA
- Parexel International Corporation
- ICON plc
- PRA Health Sciences
- Covance Inc.
- Charles River Laboratories International Inc.
- Syneos Health
- Pharmaceutical Product Development LLC (PPD)
- Medpace Holdings Inc.
- LabCorp
- Wuxi AppTec
- Accenture
- Cognizant
- Quanticate
- BioPoint Inc.
Competitive Analysis:
The competitive landscape of the Functional Service Providers (FSP) Market is marked by a diverse array of players, ranging from large multinational corporations to specialized niche firms. Major industry leaders, such as Covance, PAREXEL, and IQVIA, dominate the market, leveraging their extensive resources, comprehensive service offerings, and established reputations to attract a broad client base. These companies excel in providing integrated solutions that encompass various phases of clinical trials, allowing them to meet the complex needs of pharmaceutical and biotech firms effectively. Their robust global networks and technological capabilities further enhance their competitive advantage, enabling them to deliver high-quality services efficiently. In contrast, smaller and mid-sized FSPs often carve out competitive niches by focusing on specialized services, geographic regions, or specific therapeutic areas. These firms can be more agile, offering tailored solutions that address unique client requirements. Additionally, they often emphasize personalized service and flexible engagement models, which can appeal to companies seeking more customized support in clinical development. The market is also witnessing increased collaboration and partnerships, as companies recognize the value of combining expertise to navigate the complexities of clinical trials. This trend not only strengthens the offerings of individual FSPs but also enhances overall market competitiveness. Moreover, technological advancements, such as the integration of artificial intelligence and data analytics, are reshaping the competitive dynamics by enabling faster, more efficient trial processes. As the market evolves, companies that prioritize innovation, strategic partnerships, and responsiveness to client needs will likely maintain a competitive edge. Overall, the FSP Market is dynamic, with ongoing shifts driven by both established players and emerging firms adapting to changing industry demands.
Recent Developments:
- In January 2023, Premier Research, a clinical research organization (CRO), partnered with Centogene N.V., a global leader in genetic diagnostics, to provide end-to-end support for rare disease clinical trials. This strategic collaboration aims to enhance patient identification, stratification, recruitment, and enrollment, ultimately increasing the likelihood of study success.
- In December 2022, Everest Clinical Research, a prominent full-service contract research organization with strong expertise in biostatistics and statistical programming, acquired Brightech International, a leading CRO specializing in complex, value-added biostatistics, programming, and clinical data management services.
- In November 2022, Excelya Group, a well-known CRO partner, announced the opening of a new office in Durham, North Carolina's Research Triangle Park. Since establishing a presence in the U.S. in 2019, Excelya’s new office will further enhance the company's growth and capabilities in North America, enabling it to deliver comprehensive solutions across its Full-Service, Functional Service Provision, and Contract Staff Resourcing business models.
Market Concentration & Characteristics:
The Functional Service Providers (FSP) Market exhibits a moderate level of concentration, characterized by a mix of both large multinational corporations and smaller niche players. Major players often dominate the market due to their extensive resources, established reputations, and comprehensive service offerings that span various phases of clinical trials, from preclinical research to post-market surveillance. Companies like Covance, PAREXEL, and IQVIA leverage advanced technologies and global networks to provide end-to-end solutions, enhancing their competitive edge. In contrast, smaller firms often focus on specialized services or geographic niches, allowing them to cater to specific client needs and regulatory environments. Market characteristics also include a strong emphasis on collaboration and partnerships, as many pharmaceutical and biotech companies seek to leverage the expertise of FSPs to streamline operations and improve efficiency. This trend has been further accelerated by the increasing complexity of clinical trials, which require a diverse set of skills and capabilities. As a result, many FSPs are expanding their service portfolios to include innovative technologies like artificial intelligence, machine learning, and data analytics, thereby improving trial design and patient engagement. Additionally, the market is characterized by rapid technological advancements and evolving regulatory requirements, which compel FSPs to continuously adapt their strategies and offerings. The rising demand for patient-centric approaches and real-world evidence is also shaping service delivery models. Furthermore, geographic diversification is becoming increasingly important, as companies look to tap into emerging markets with growing healthcare investments. Overall, the FSP Market is dynamic and evolving, driven by a combination of competitive strategies, technological innovation, and changing client demands.
Report Coverage:
This report provides a comprehensive analysis of the Functional Service Providers (FSP) Market, covering key trends, growth drivers, challenges, and competitive dynamics from 2024 to 2032. It examines the current market landscape, highlighting the value of the market at approximately USD 16,945 million in 2024, with projections of reaching around USD 33,515.97 million by 2032, reflecting a robust CAGR of 8.90%. The report delves into the factors fueling this growth, such as the increasing outsourcing of clinical functions, advancements in technology, and the rising complexity of regulatory environments. Regional analyses spotlight North America and Europe as the leading markets, while also emphasizing the emerging potential of the Asia-Pacific region. Furthermore, the report addresses market concentration and characteristics, showcasing the balance between large multinational corporations and specialized niche players. It also identifies key challenges facing the market, including regulatory compliance and data security concerns. The report concludes with strategic recommendations for stakeholders, emphasizing the importance of innovation, collaboration, and geographic diversification in navigating the evolving landscape of the FSP Market. By providing actionable insights and detailed forecasts, this report serves as a valuable resource for industry participants, investors, and policymakers seeking to understand the dynamics shaping the future of functional service provision in clinical research.
Future Outlook:
- The Functional Service Providers (FSP) Market is expected to continue its robust growth, from 2024 to 2032.
- Increasing complexity in clinical trials will drive demand for specialized services and expertise.
- Technological advancements, particularly in data analytics and automation, will enhance operational efficiencies.
- Pharmaceutical companies are likely to further outsource non-core functions to focus on innovation and core competencies.
- The Asia-Pacific region is anticipated to witness significant market growth, fueled by expanding healthcare infrastructure and investment.
- Strategic partnerships between FSPs and biotech/pharma companies will become more prevalent to optimize clinical development processes.
- Regulatory changes will necessitate FSPs to adapt quickly, ensuring compliance and quality in clinical trials.
- Increased focus on patient-centric approaches will drive demand for innovative trial designs and methodologies.
- Sustainability and ethical considerations will become integral to FSP operations and service offerings.
- Overall, the FSP Market is poised for continued transformation and expansion, driven by evolving industry needs and technological innovations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Investment in Healthcare Research
Growing funding from governments and international organizations for healthcare R&D is fueling demand for FSPs, as pharmaceutical and biotech companies require specialized expertise to manage complex clinical trials and accelerate drug development.
Regulatory Evolution and Adaptation
Frequent updates and increasing complexity in regulatory requirements are prompting companies to engage FSPs with deep compliance knowledge, ensuring trials meet global standards and avoid costly delays or rejections.
Focus on Patient-Centric Approaches
The shift toward patient-centric clinical trial designs is driving demand for FSPs that can deliver tailored recruitment strategies, improve patient engagement, and leverage technology to enhance trial participation and retention.
Adoption of Advanced Technologies
Rapid integration of AI, machine learning, and data analytics in clinical research is increasing the need for FSPs capable of implementing and managing these technologies, resulting in faster, more efficient, and higher-quality clinical trials.
Outsourcing of Clinical Functions
Pharmaceutical and biotech companies are increasingly outsourcing non-core clinical functions to FSPs to improve operational efficiency, reduce costs, and focus internal resources on innovation and core competencies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current value of the Functional Service Providers (FSP) Market?
How much is the market expected to grow by 2032?
What are the main factors driving market growth?
Which region leads the Functional Service Providers (FSP) Market?
Which region is expected to see significant growth in the coming years?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Cloud-Based Solutions
- 1.2.2 On-Premise Solutions
- 1.2.3 Mobile-Based Solutions
- 1.2.4 Hybrid Solutions
- 1.3 By Client Type
- 1.3.1 Pharmaceutical Companies
- 1.3.2 Biotechnology Firms
- 1.3.3 Medical Device Companies
- 1.3.4 Academic and Research Institutions
- 1.3.5 Contract Research Organizations (CROs)
- 1.4 By Service Type
- 1.4.1 Clinical Development Services
- 1.4.2 Data Management Services
- 1.4.3 Biostatistics Services
- 1.4.4 Regulatory Affairs Services
- 1.4.5 Patient Recruitment Services
- 1.4.6 Pharmacovigilance Services
- 1.4.7 Other Specialized Services
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 16,945 million → Forecast year: USD 33,515.97 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Functional Service Providers (FSP) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Functional Service Providers (FSP) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Functional Service Providers (FSP) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Functional Service Providers (FSP) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Functional Service Providers (FSP) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Functional Service Providers (FSP) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Functional Service Providers (FSP) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Functional Service Providers (FSP) Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 16,945 million → Forecast year: USD 33,515.97 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Functional Service Providers (FSP) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cloud-Based Solutions
- 12.3.7.2 On-Premise Solutions
- 12.3.7.3 Mobile-Based Solutions
- 12.3.7.4 Hybrid Solutions
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Client Type - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceutical Companies
- 12.4.7.2 Biotechnology Firms
- 12.4.7.3 Medical Device Companies
- 12.4.7.4 Academic and Research Institutions
- 12.4.7.5 Contract Research Organizations (CROs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Service Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Clinical Development Services
- 12.5.7.2 Data Management Services
- 12.5.7.3 Biostatistics Services
- 12.5.7.4 Regulatory Affairs Services
- 12.5.7.5 Patient Recruitment Services
- 12.5.7.6 Pharmacovigilance Services
- 12.5.7.7 Other Specialized Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Functional Service Providers (FSP) Geographic Market Outlook
- 13.1 Regional Market Size and Share, 2032
- 13.2 Regional Market Forecast
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Functional Service Providers (FSP) Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Functional Service Providers (FSP) Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2032
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 IQVIA
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Parexel International Corporation
- 17.4 ICON plc
- 17.5 Covance Inc.
- 17.6 Charles River Laboratories International Inc.
- 17.7 Syneos Health
- 17.8 Pharmaceutical Product Development LLC (PPD)
- 17.9 Medpace Holdings Inc.
- 17.10 LabCorp
- 17.11 Wuxi AppTec
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

